
Sargento Celebrates 2025 Achievements in Real Impact Report
Source: PR Newswire
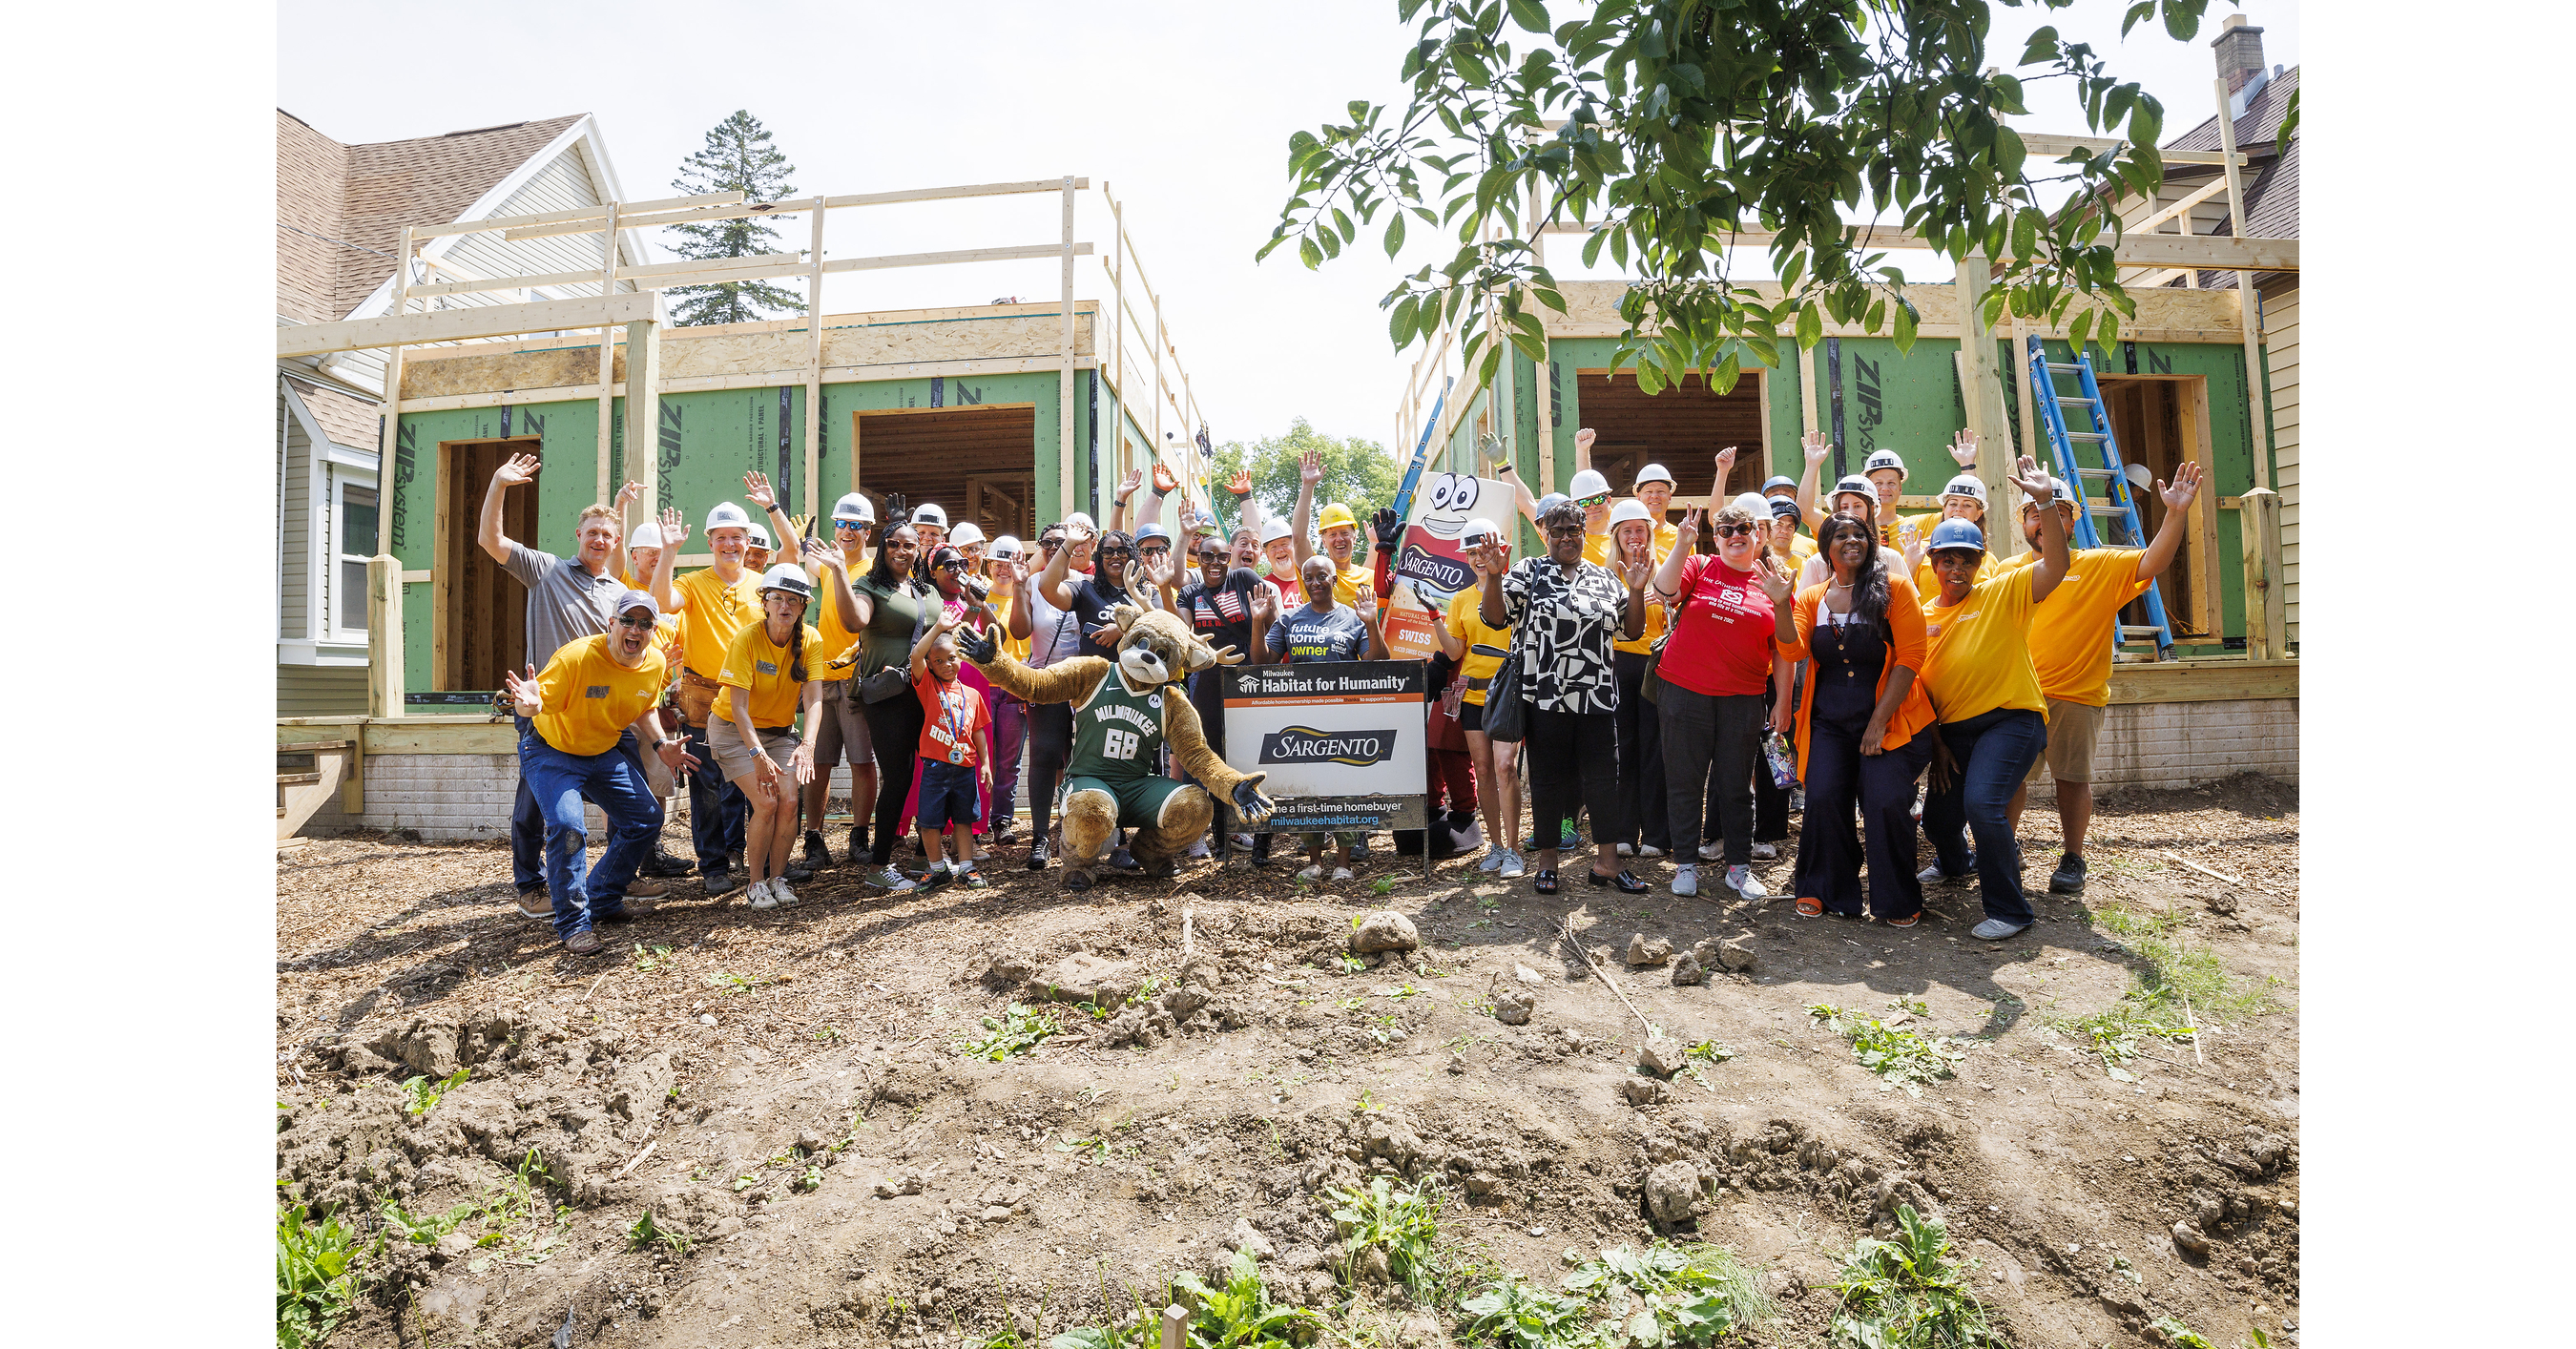
Sargento released its 2025 Real Impact Report, highlighting a record B2B revenue performance in Food Service & Ingredients (41+ years after the segment was created) alongside ESG progress. The report cites 2,962 hours of community service, 689,553 pounds of cheese/food donated, and $2.9M in donations; on the environmental side it claims 12.2M gallons of water saved and 91.4% of facility waste diverted from landfill. New product momentum includes the launch of Sargento Natural American Cheese (five ingredients; 100% natural) and collaborations with Mondelēz (Shareables/Cheese Bakes) and McCormick (Seasoned Shreds), with AA+ food safety ratings from BRC.
Analysis
This reads more like a distribution-and-innovation signal than an ESG event. The only economically relevant takeaway for MDLZ is that branded food players are still using co-developed, premium, clean-label products to defend shelf space and keep velocity in mature categories; that tends to support mix more than absolute unit growth. Near term, the P&L impact is likely immaterial, but it reinforces the idea that the winners in packaged food are the companies that can turn branding into incremental occasions rather than just defend price.
The second-order risk is that “natural” and premiumized cheese continues to expand away from commoditized dairy formats, which pressures private label and lower-tier branded operators more than it helps MDLZ directly. If the collaboration gains traction, the real benefit is better retailer relationships and incremental merchandising leverage, not a step-change in revenue. The more useful read-through is that foodservice/ingredients demand is still healthy, which suggests the category can absorb input-cost volatility without immediate volume collapse.
Consensus is probably overrating the sustainability optics and underweighting the channel signal. This is not a catalyst for multiple expansion on its own; the stock only deserves credit if MDLZ shows this kind of innovation translating into North America mix improvement or share gains over the next 1-3 quarters. The thesis is falsified if MDLZ comments on softer snacking volumes, retailer rationalization, or margin pressure that offsets any premium-product halo.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in MDLZ; treat this as a watch item and wait for evidence in next earnings or Nielsen/IRI checks that co-branded innovation is moving North America mix, not just generating PR.
- If MDLZ pulls back 2-3% on no fundamental news, consider a small tactical long for a 1-3 month horizon; upside is modest but supported by defensive brand quality, while downside is limited unless volume commentary deteriorates.
- Relative-value idea: long MDLZ / short a weaker packaged-food peer over 1-3 months only if channel data confirm premium-snack share gains; target low-single-digit relative outperformance, stop if MDLZ does not mention incremental distribution or mix lift.
- Avoid buying the ESG narrative here; if management does not translate these partnerships into measurable organic growth or margin resilience by the next quarter, fade any enthusiasm in the stock.
More News
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies