
PNC Bank Expands Branch Buildout to More Than 370, Will Build 60 Branches Per Year
Source: PR Newswire
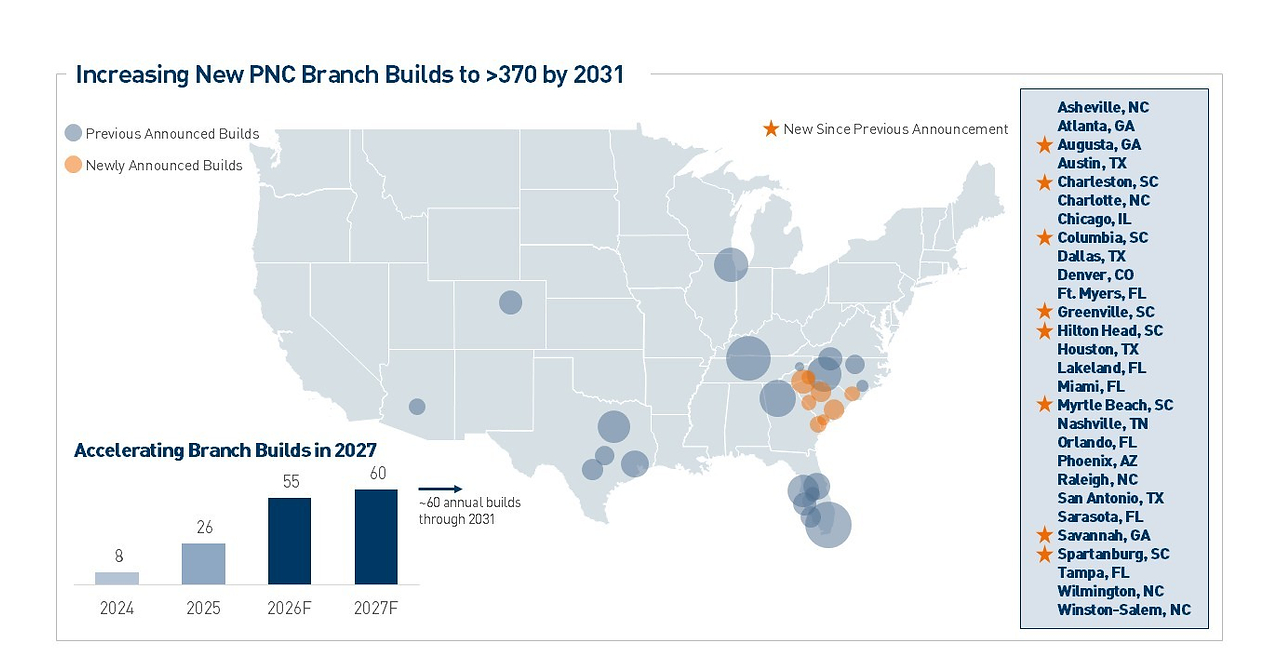
PNC plans to expand to more than 370 new branches by 2031, including over 50 in South Carolina and Georgia and 10 additional locations in Texas, Florida and North Carolina. The roughly $2.5 billion network investment includes plans to open 60 branches annually from 2027 and hire 2,400 employees. PNC also reported 9% year-over-year growth in active digital users in the third quarter.
Analysis
The strategic bet is not simply on branch traffic; it is on acquiring lower-cost, relationship-based deposits and using in-person advice to cross-sell business banking and wealth services. If new locations win primary accounts, the payoff can extend beyond local retail economics. But that benefit is conditional: branch openings create a multi-year fixed-cost burden before deposits and fee income mature, while the mobile-app user growth cited does not establish that digital engagement converts into profitable relationships.
In the near term, expect the market to focus less on the footprint headline than on expense guidance and deposit pricing. Over 1–3 months, monitor whether PNC attributes deposit or account growth to newer markets and whether expense growth pressures its efficiency ratio. In 6–18 months, success depends on branch-level ramp and cross-sell; population growth alone is not proof of attractive returns. Incumbents—including Truist, Bank of America, Wells Fargo and regional banks—may respond with pricing or retention offers, potentially raising PNC’s cost to gather deposits. There is also cannibalization risk where new branches overlap PNC’s existing or planned Southeast presence.
Contrarian read: the expansion may be a disciplined distribution investment, not an endorsement of physical banking replacing digital. Still, management’s positive description of prior-market results is not independently verifiable evidence of branch returns. Without market-level deposit, loan and expense data, this is a modest strategic positive rather than a standalone catalyst; avoid extrapolating the announcement into near-term earnings upside.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the announcement. Keep PNC on a relative-value watchlist; do not initiate a directional position without evidence that new-market deposits and relationship revenue are ramping faster than associated operating costs.
- At the next earnings update, track deposit growth and mix, deposit costs, net interest margin, noninterest expense and the efficiency ratio. Treat improving deposits without expense discipline as insufficient confirmation.
- Set a 1–3 month catalyst check for management disclosure of results in newer Southeast markets. Reassess positively if growth is accompanied by stable funding costs and expense guidance; falsify the thesis if expense growth pressures the efficiency ratio without corresponding deposit or revenue traction.
- Monitor competitor pricing and retention activity in the targeted markets. A material rise in deposit costs or weaker-than-expected local account acquisition would undermine the expected return on the branch buildout.
More News
- Tech stock rout, driven by US AI fears, continues in Asian trading
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- Fox completes its $22B acquisition of Roku
- Elanco Shares Jump After Q3 Beat and Outlook Raise
- Paraguay’s Santiago Pena under arrest, new president Pedro Alliana sworn in
- FIGS Beats Earnings as Demand Outstrips Supply, CEO Trina Spear Says
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- How to Automate Equity Research Workflows: A Control-First Guide