
Sophia Space and SLI Set Terms for $300 Million Asset Financing for 10-Satellite High-Performance Edge Computing Constellation
Source: PR Newswire
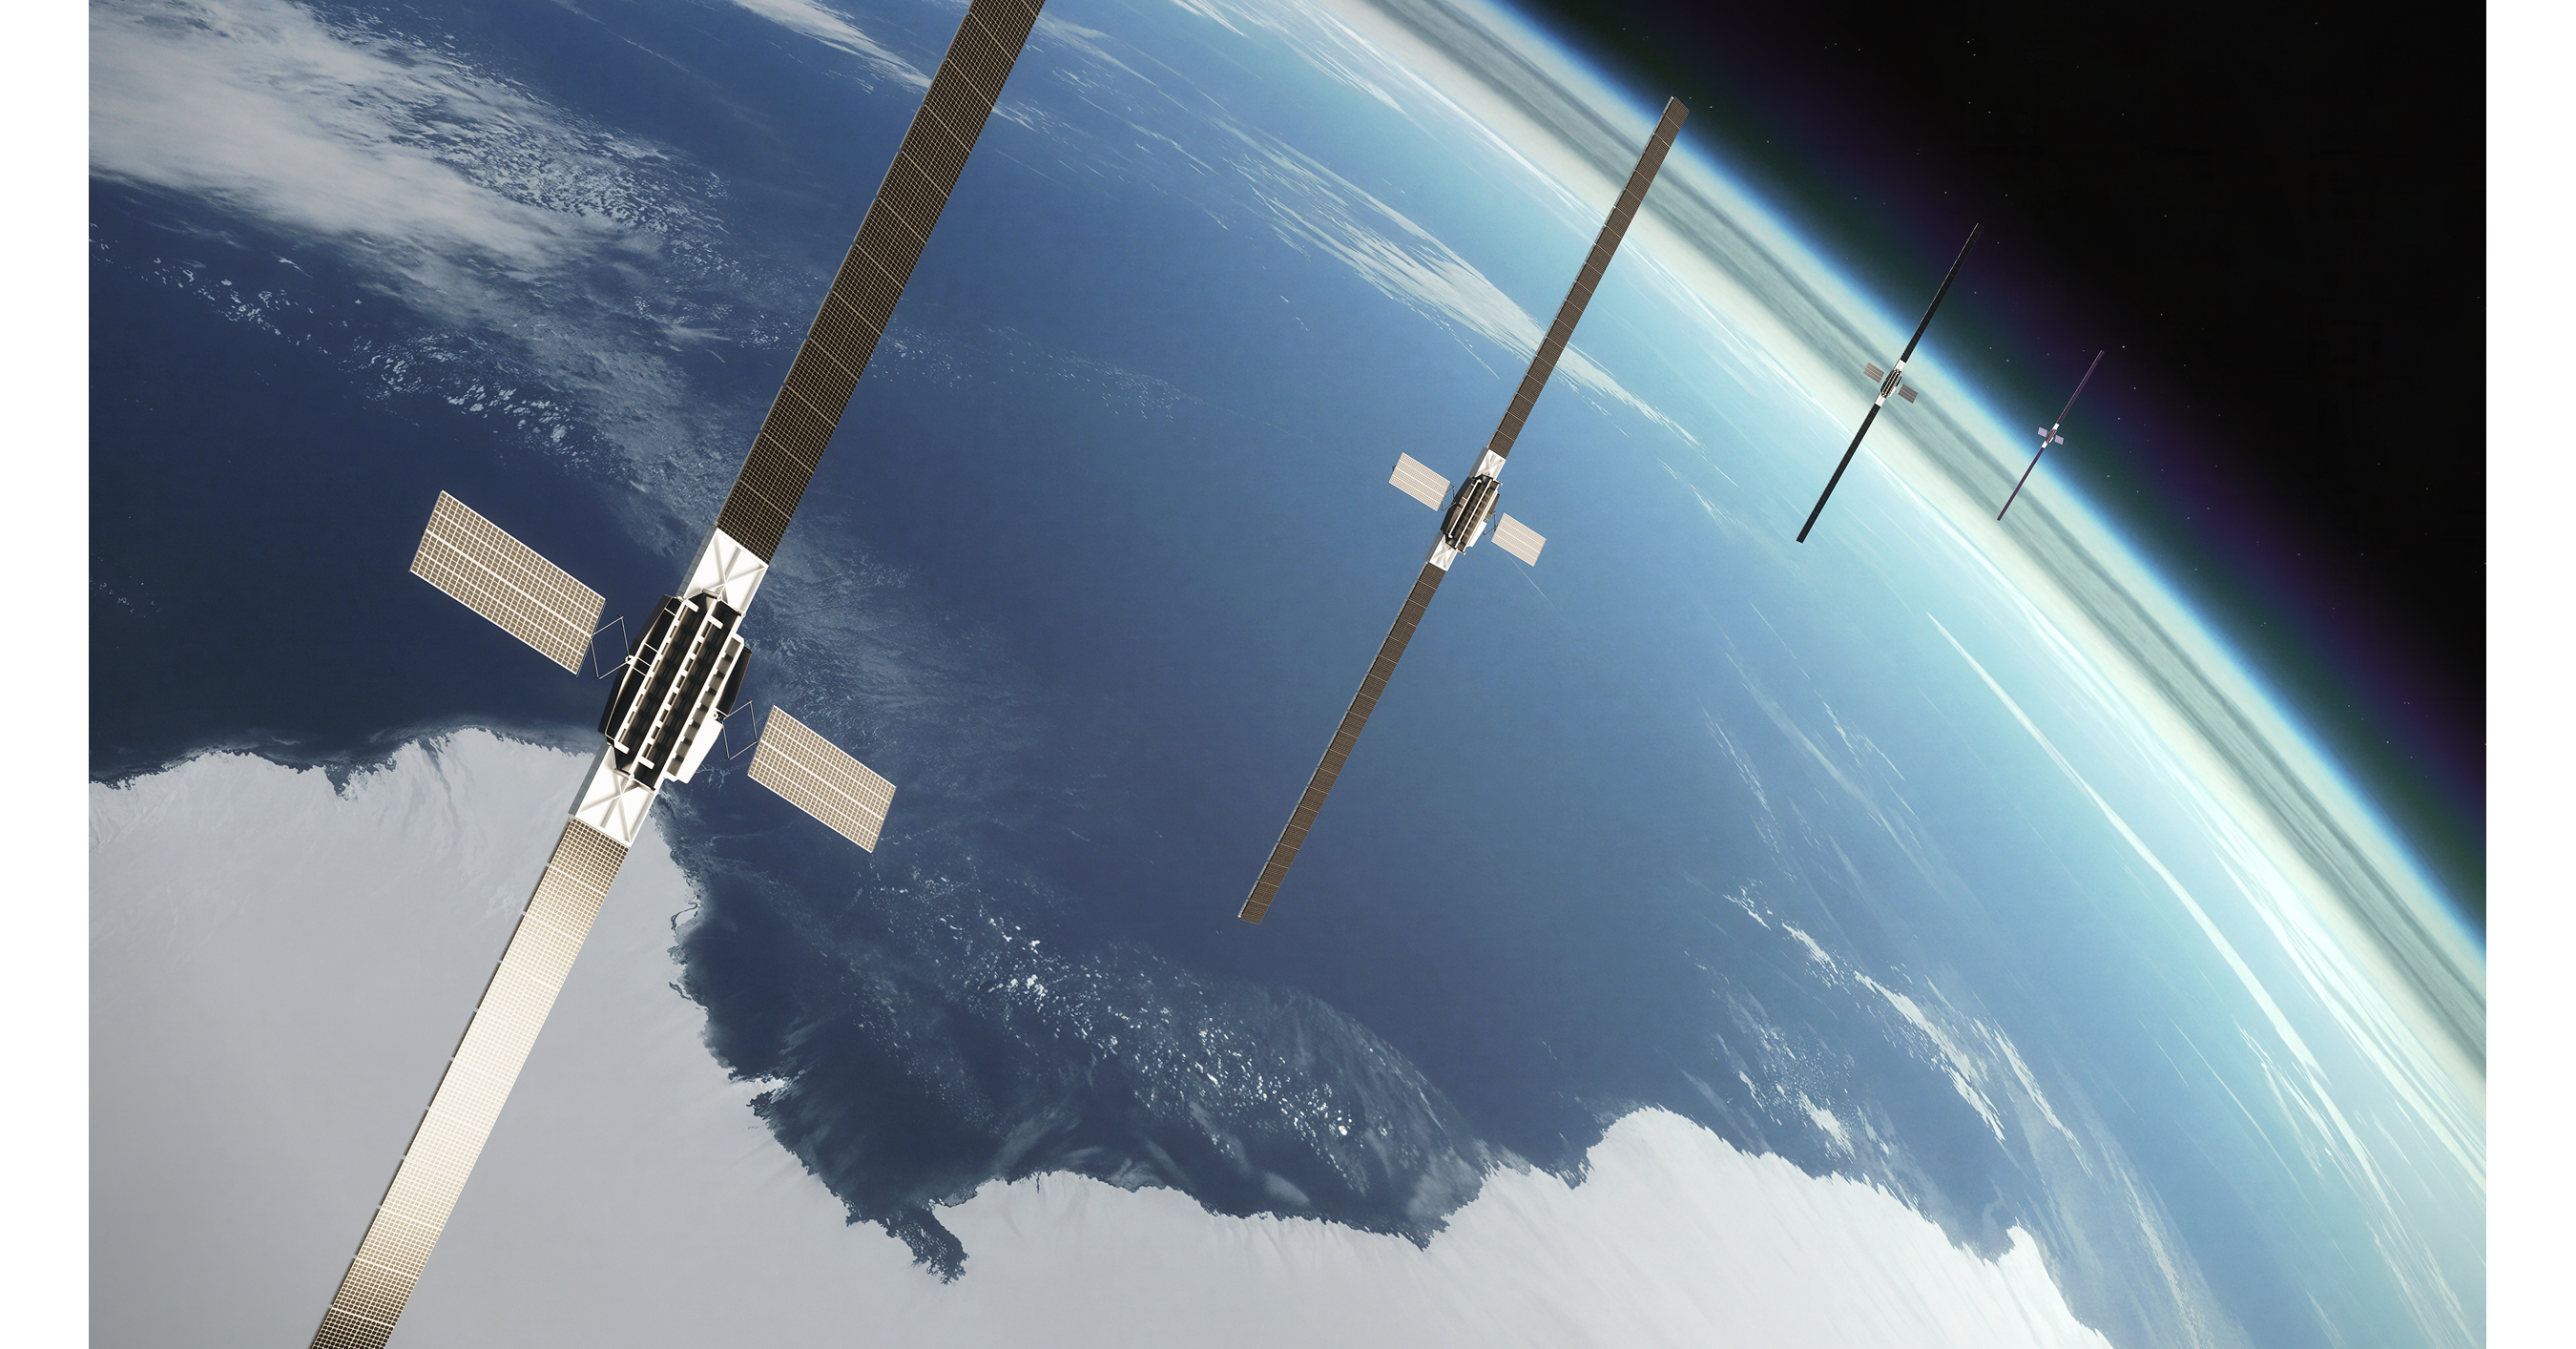
Sophia Space announced a $300 million financing framework with aerospace leasing specialist SLI to fund a planned 10-satellite orbital edge-computing constellation, with launches targeted as early as 2028. Under the non-binding arrangement, SLI would buy Sophia's TILE satellites and lease them to users through fixed payments, providing scalable non-dilutive capital and preserving Sophia's equity for technology development and operations. The proposed constellation would provide computing capacity equivalent to 240 state-of-the-art edge servers for Earth observation, weather, supply-chain, disaster-response, and security applications.
Analysis
The relevant signal is not near-term revenue but whether satellite assets can become financeable against contracted utilization rather than venture equity. If replicated, this lowers the cost of capital for operators with credible launch, insurance, and customer contracts, favoring vertically integrated public suppliers such as Rocket Lab (RKLB) and defense primes with classified/ISR exposure (LHX, NOC) before it benefits speculative satellite operators. The bottleneck shifts from hardware funding to underwriting residual value: satellites have limited secondary-market value after a launch failure, technology obsolescence, or a customer default, so lease economics will require high pricing, insurance coverage, and investment-grade-like counterparties.
This is not independently validated financing until binding commitments, identified lessees, launch contracts, and insurance terms are disclosed. Over the next 1-3 months, the read-through is modestly positive for space-infrastructure valuations but should not materially alter earnings estimates; the 6-18 month catalyst would be multiple comparable lease financings tied to government or commercial take-or-pay contracts. Contrarian view: market enthusiasm may overvalue the "asset-light" label—fixed lease obligations can create more severe downside than equity dilution if utilization ramps slowly, while public remote-sensing names such as BlackSky (BKSY) and Planet Labs (PL) may face added competition only if orbital processing demonstrably reduces customers' data-transmission and latency costs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No direct position in Sophia Space or SLI: both are private and the framework lacks disclosed binding economics, end-customer credit quality, launch provider, and insurance coverage. Create an alert for definitive financing and named contracted capacity rather than extrapolating the stated headline value.
- Maintain a 6-12 month watch-list long bias on RKLB versus AST SpaceMobile (ASTS): RKLB has more diversified spacecraft/component and launch exposure if third-party constellations move from concept to procurement, whereas ASTS remains more dependent on a single capital-intensive network build. Enter only after confirming incremental satellite backlog or guidance; invalidate on material launch-delay or backlog-conversion deterioration.
- For defense exposure, prefer LHX or NOC over pure-play Earth-observation equities on a 12-18 month horizon. Government ISR demand is the most plausible source of creditworthy contracted utilization that can support satellite financing; trim if U.S. defense budget/space procurement guidance weakens or if contract awards fail to convert.
- Avoid chasing BKSY and PL solely on this development. A long thesis requires evidence that in-orbit processing produces measurable improvement in gross margin, revisit rates, or contract win rates; absent this, additional orbital-compute capacity is more likely a competitive input-cost risk than a sector-wide earnings catalyst.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- The UK cuts energy bills, taxes banks and boosts defense in high-stakes budget
- Microsoft's Big Bets on AI Start to Pay Off
- Asian shares fall as Alphabet earnings miss drags Wall St futures lower
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- The Great Divergence: North American Banking at the Crossroads of Monetary Policy and Agentic AI (Q4 2025 Bank Earnings)
- How to Extract KPIs From Earnings Transcripts With AI