
DAR GLOBAL VERZEICHNET IM ERSTEN HALBJAHR 2026 EIN UMSATZWACHSTUM VON 66 %, WÄHREND DER GDV DES PORTFOLIOS 23 Mrd. US-Dollar ERREICHT
Source: PR Newswire
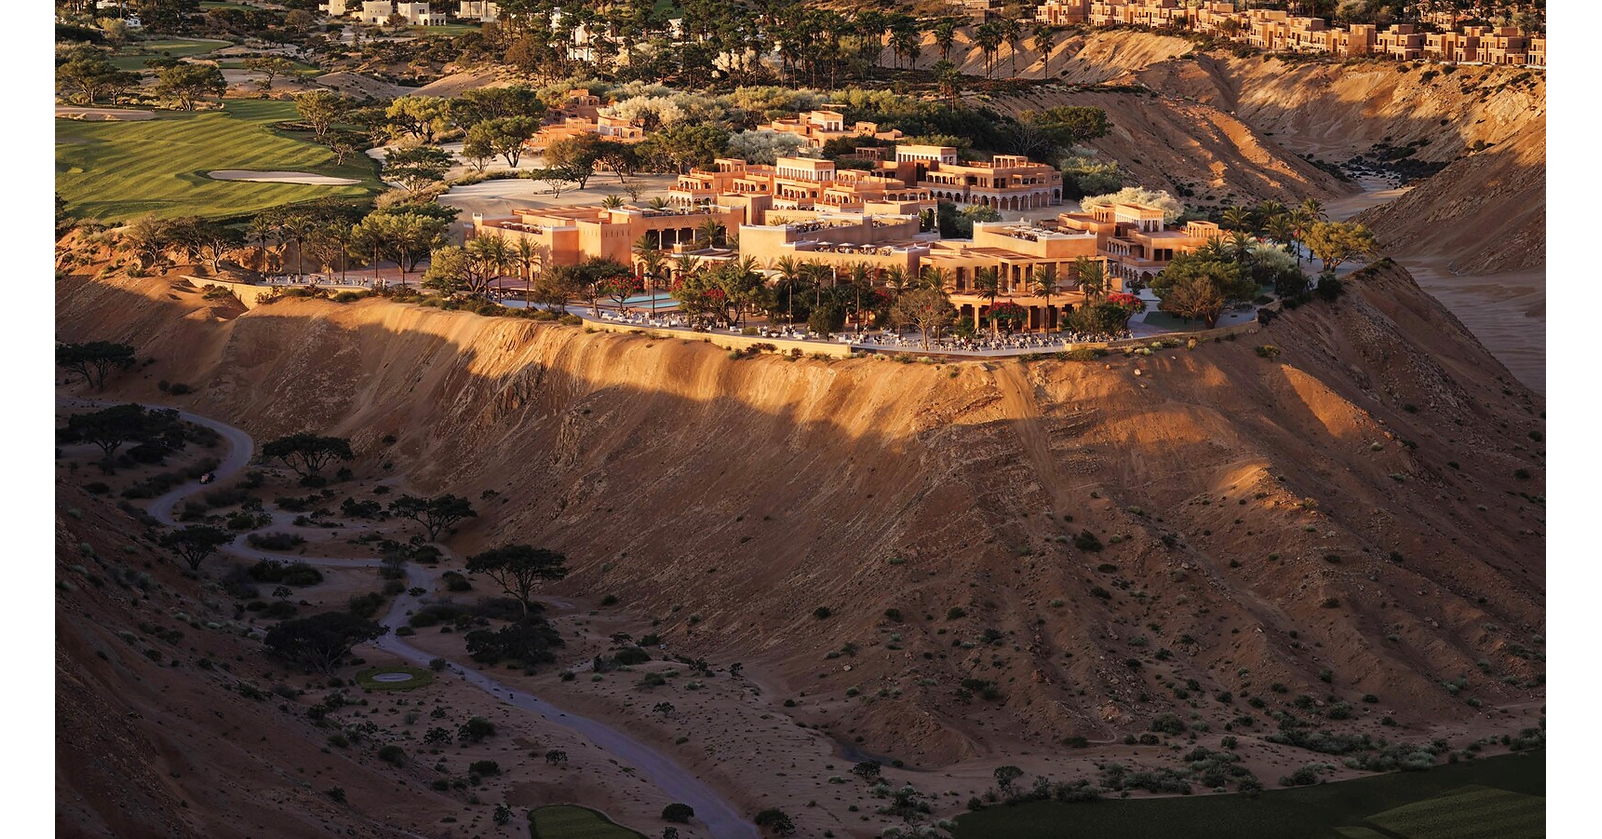
Dar Global reported H1 2026 revenue growth of 66% to $258.0 million, while net profit rose 149% to $30.4 million and EBITDA increased 73% to $46.3 million. Gross margin expanded 300bps to 34%, and portfolio GDV nearly doubled year over year to $23.0 billion, supported by $3.9 billion of contracted revenue across 4,380 units. The luxury developer also reported $579.3 million of available liquidity and completed a $250 million syndicated loan, while advancing major Saudi and Dubai Trump-branded developments.
Analysis
DAR’s earnings quality hinges less on headline presales than on construction-stage conversion, customer collections, and land-payment obligations. The expanded development pipeline creates operating leverage if delivery milestones remain on schedule, but it also increases exposure to cost inflation, contractor execution, and a luxury-buyer demand reversal in Dubai and Saudi Arabia. The key valuation question over the next 6-12 months is whether contracted sales convert into operating cash flow faster than debt and working-capital needs rise.
The Saudi portfolio raises the company’s strategic relevance to Vision 2030-linked luxury development, but concentrates execution risk in a market with a shorter track record of high-end residential absorption than Dubai. Large branded projects can support pricing premiums, yet brand affiliation does not remove demand cyclicality; a softer oil price, weaker regional liquidity, or tighter UAE/Saudi mortgage and residency policy could expose cancellation and collection risk with a lag of 1-3 quarters.
AML has negligible direct earnings sensitivity: branded residences may produce licensing income and marketing value, but they are not material enough to change Aston Martin’s automotive cash-flow or leverage thesis. The more investable second-order implication is for Dubai/Saudi contractors and building-material suppliers if project starts accelerate, although listed pure-play access is limited and individual contract awards should not be extrapolated into recurring margin expansion.
Contrarian view: the market may initially capitalize the enlarged project pipeline as if it were backlog. For developers, pipeline value is not equivalent to equity value; the relevant discount rate should rise if funding costs, construction guarantees, or buyer-payment schedules deteriorate. A re-rating requires independently verifiable cash conversion and stable gross margin through delivery, not further launch announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.74
Ticker Sentiment
Key Decisions for Investors
- Maintain a constructive watch on DAR for a 6-12 month long only after reviewing interim cash-flow, net debt, restricted-cash and receivables disclosures; initiate only if operating cash conversion remains positive while project funding needs are contained. The thesis is falsified by rising receivables/cancellations, margin erosion below the recent delivery profile, or another material debt raise.
- Do not use AML as a sympathy long. Treat branded-residence announcements as commercially positive but financially immaterial unless AML discloses recurring licensing economics large enough to affect EBITDA or deleveraging; its primary valuation drivers remain vehicle volumes, mix, pricing and refinancing.
- For existing DAR exposure, use the next results cycle as the catalyst window: add on evidence that collections and free cash flow track recognized revenue; reduce if construction commitments grow faster than available liquidity. The asymmetric downside is a developer-style multiple compression if presale conversion weakens, even with reported revenue growth.
- Monitor Brent, GCC bank credit conditions and Dubai luxury-residential transaction volumes over the next 1-3 months as leading indicators. A sustained oil-price decline or widening regional credit spreads would warrant lowering DAR exposure before cancellations and lower realized selling prices appear in reported results.
More News
- Ten Reasons Investors Are Driving Government Bond Yields Higher
- Asian stocks dip, bonds in focus after torrid September
- September Ends on a Grim Market Note: Evening Briefing Americas
- China’s Property Crisis: From Evergrande Collapse to Beijing’s Latest Measures
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT