
Grundig stellt auf der IFA 2026 neue Produktpalette vor und läutet damit eine neue Phase der strategischen Partnerschaft ein
Source: PR Newswire
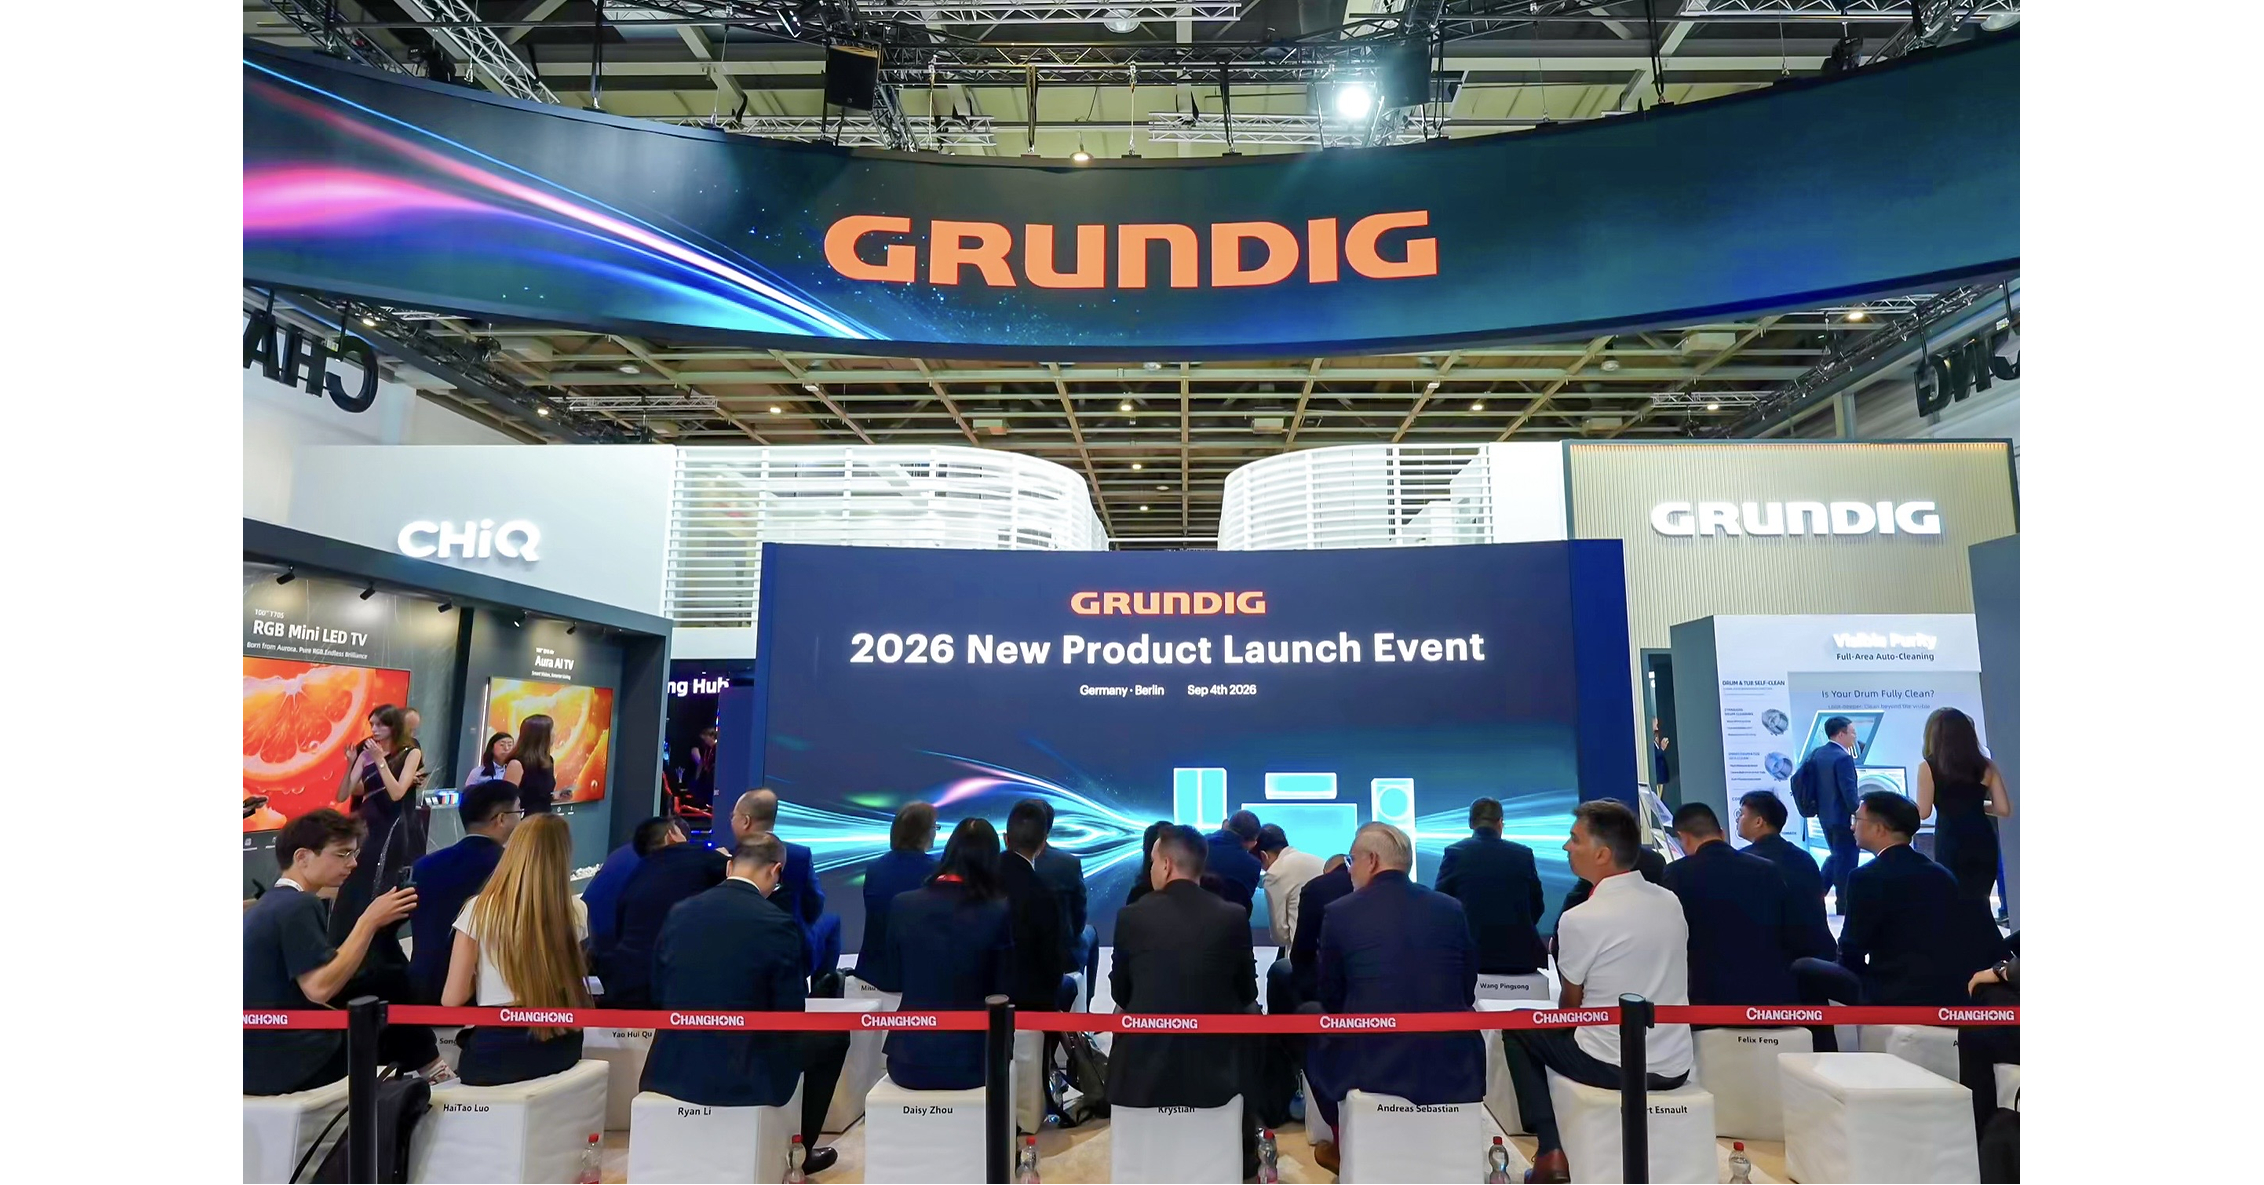
Grundig stellte auf der IFA 2026 eine neue Produktpalette vor und startete damit eine neue Phase der strategischen Partnerschaft mit Beko/Changhong, nachdem Changhong die Lizenz für Grundig in ausgewählten Kategorien und Märkten erhalten hat. Zum Portfolio gehören u.a. der Flaggschiff-TV AURORA 100 mit RGB-Micro-Focusing-LED, 9.720 einzeln steuerbaren Dimmzonen sowie die Kühlschrankserie „Space Pro“ (599 mm Tiefe, 600 Liter) und energieeffiziente Wärmepumpentrockner (45 °C) sowie KI-gesteuerte Klimaanlagen. Die Nachricht ist überwiegend wachstums- und produktgetrieben, ohne konkrete Finanzkennzahlen; potenzieller Effekt bleibt daher eher auf Marken-/Segmentebene begrenzt.
Analysis
The investable read-through is not the launch itself; it is the shift toward a more capital-light go-to-market model. If Beko can monetize the Grundig brand while Changhong absorbs more of the manufacturing and supply-chain burden, the upside is in mix and working-capital efficiency rather than headline unit growth. That kind of structure can support gross margin and free cash flow, but it rarely commands a valuation rerate unless management proves the brand can consistently pull through pricing.
For competitors, the main pressure is on mid-tier appliance and consumer-electronics players that compete on design-plus-value rather than pure premium cachet. Electrolux and Whirlpool are exposed if the partnership accelerates refresh cycles and improves shelf presence in Europe, because those names already face weak pricing power and promotional intensity. The second-order effect is more important than the SKU launch: faster product iteration from a lower-cost Asian manufacturing base can compress industry margins even if end-demand is flat.
Contrarian view: the market may be overestimating earnings impact and underestimating brand-dilution risk. Licensing-led expansion usually adds low-single-digit economics unless sell-through data proves otherwise, and any benefit can be offset by channel discounting or regulatory/tariff friction tied to Chinese manufacturing links. Near term, this is a watch item rather than a high-conviction trade; the thesis only becomes actionable if we see measurable gross-margin expansion or market-share gains in the next 1-2 quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate trade: keep ARCLK on watch for the next earnings print; only get constructive if management quantifies >100 bps gross-margin uplift or material working-capital improvement over 1-2 quarters.
- Relative-value idea: long ARCLK / short WHR on a 6-12 month horizon if European appliance pricing remains soft and Beko shows share gains without higher inventory.
- Secondary pair: long ARCLK / short ELUX-B.ST if channel checks show Grundig/Beko taking shelf space from legacy European brands; invalidate if ELUX restores pricing or volume in its core categories.
- Watch Sichuan Changhong (600839.SS) for any evidence that this European brand access translates into export growth; avoid chasing it now because the thesis depends on sell-through, not the press release.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- Zoom and big financial firms add ‘Proof of Human’ badges from Sam Altman’s World to stop fraud and deep fakes
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit
- AI Research Systems for Hedge Funds: A Pilot Design