
Envision Energy uvádí větrnou turbínu Model T - EN175/8.0 pro pevninské využití, která posouvá hodnotu životního cyklu budoucích energetických systémů
Source: PR Newswire
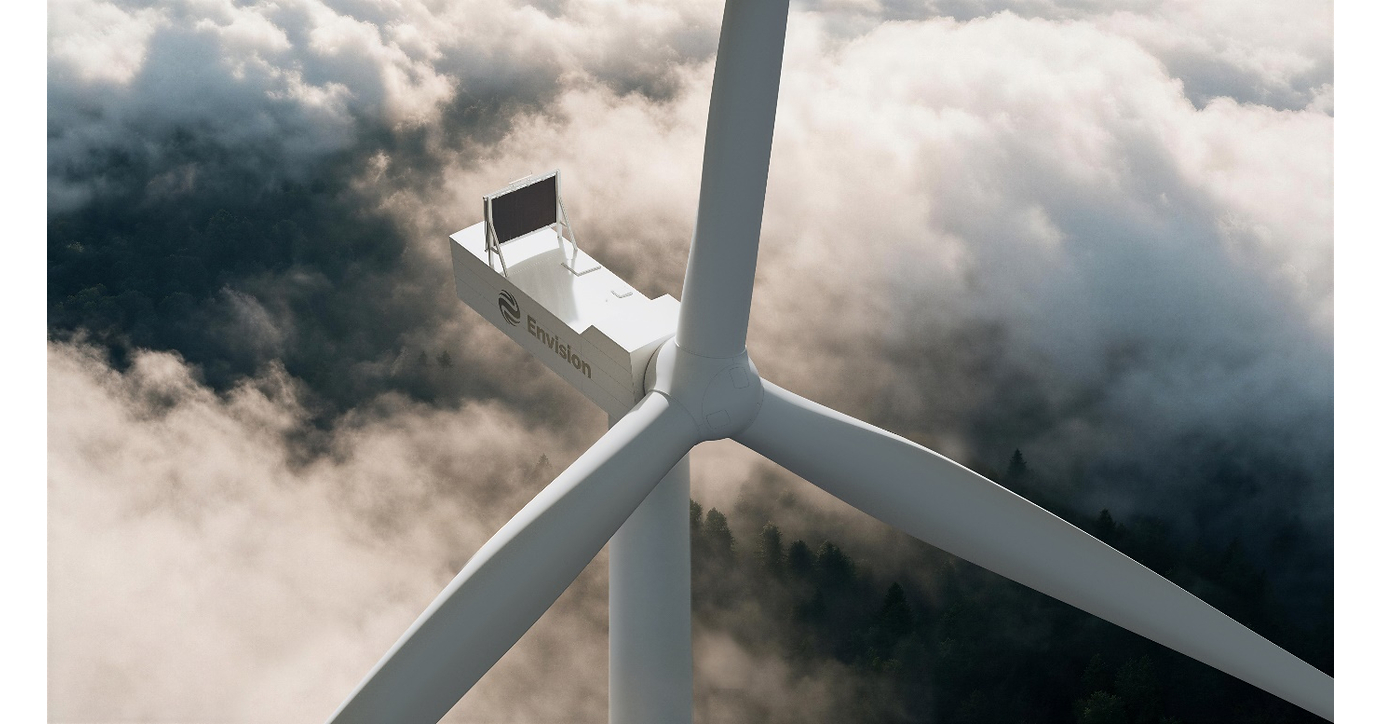
Envision Energy launched its onshore Model T EN175/8.0 wind turbine, an 8.0MW unit with a 175-meter rotor designed for medium-wind and challenging sites. The company says the turbine can increase energy yield by 2%-12% versus existing models, while AI-driven Galileo controls autonomously optimize operations using real-time weather and energy-system data. The turbine also incorporates grid-forming controls, 107 dB(A) acoustic performance, and optional cold-climate and anti-icing configurations, positioning it for broader renewable-power and grid-integration deployments.
Analysis
This is competitively relevant but not yet investable: Envision is private, and a launch claim without disclosed orders, certified power curve, warranty terms, or delivered cost per MW does not change public-company estimates. The meaningful pressure point is on European OEMs Vestas (VWS.CO) and Siemens Energy (ENR.DE): a credible Chinese 8MW onshore platform could force lower bid prices in medium-wind and price-sensitive export markets, where fixed-cost absorption makes even modest volume losses disproportionately dilutive to service and manufacturing margins.
Near term (days to 3 months), treat this as a procurement-data watch rather than a sector catalyst. Watch tender wins, export-credit financing, IEC/type certification, European local-content restrictions, and disclosed availability/warranty performance; these determine whether claimed energy-yield gains translate into bankable project IRRs. The second-order beneficiary is Mingyang Smart Energy (MYSEY), whose offshore-led internationalization has similar implications for Chinese OEM acceptance, while grid-forming inverter and storage suppliers could benefit if developers increasingly procure hybrid plant-control systems rather than standalone turbines.
Contrarian view: European wind OEM shares may be insulated because regulatory barriers, cybersecurity scrutiny, bankability requirements, and local-service networks matter more than nameplate economics in the EU and US. The greater risk is likely in emerging-market tenders, where Chinese financing plus vertically integrated supply can compress global turbine pricing before it materially displaces European installed bases. A failure to demonstrate low field-failure rates over 12-24 months would turn the larger rotor into a warranty-reserve and working-capital liability rather than a competitive advantage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No outright trade on the launch. Establish an alert for Envision export order announcements, third-party certification, and financing-backed wins; absent these, estimate impact is below the threshold for position initiation.
- Monitor VWS.CO and ENR.DE tender/order intake over the next 1-3 quarters for margin-sensitive emerging-market or non-core European projects. Consider a tactical short only if order backlog converts at lower pricing or management cuts turbine-margin guidance; cover on evidence of protected pricing or service-margin resilience.
- For renewable-equipment exposure, prefer VWS.CO over ENR.DE on a relative basis if Chinese competition accelerates: Vestas' service mix and lower power-grid-turnaround exposure provide cleaner downside protection. Falsifier: Vestas reports material pricing concessions or rising warranty provisions.
- Watch MYSEY as a high-beta read-through on Chinese OEM export acceptance, not a direct beneficiary recommendation. A sequence of third-party-financed non-China awards would validate international competitive pressure; policy restrictions or weak project execution would invalidate the thesis.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Houthi attack on Mecca, Medina would cross ‘red line’, Pakistan PM tells UN
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying