
BenQ Unveils New Visual Innovations for Work and Entertainment at IFA 2026
Source: PR Newswire
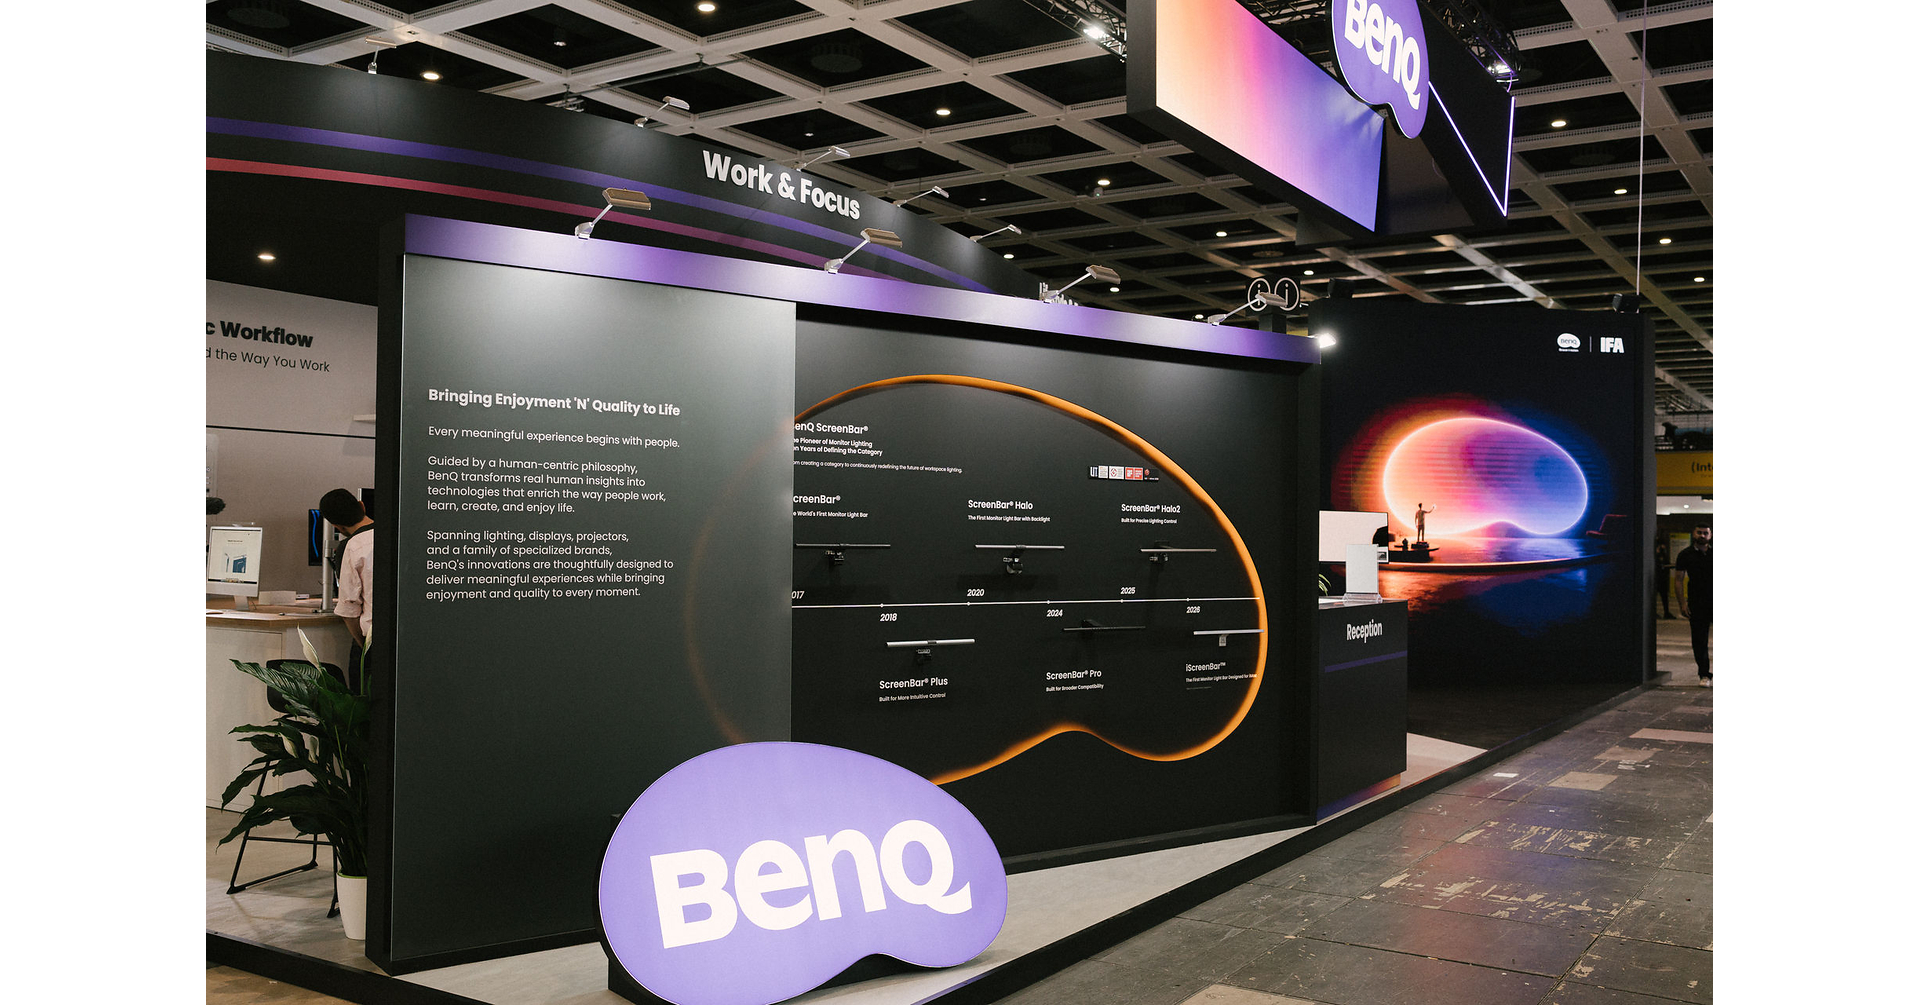
BenQ showcased new work and home-entertainment visual products at IFA 2026, including the ScreenBar Max and iScreenBar for iMac users, plus AI-enhanced projection models. The company also cited German monitor sales rising 6.7% in 2025 to nearly 3.4 million units, using that demand to support an expanded portfolio across monitors, lighting, projection, and ergonomic Apple-focused desktop accessories (INFTYLAB). Overall, the update is constructive on product momentum but provides no earnings, margin, or guidance figures.
Analysis
This is mostly a share-of-wallet story, not a demand shock. The market implication is that desktop tech is fragmenting into narrower use cases, which usually helps differentiated brands with ecosystem fit but hurts undifferentiated OEMs that rely on broad, spec-driven selling. For public comps, that is a mild negative for peripheral and monitor vendors with weak software or design moats, while the benefit to AAPL is mainly indirect via ecosystem stickiness rather than meaningful earnings lift.
Near term, I would not expect a large stock reaction unless channel checks confirm stronger attach rates or better pricing in Mac-related accessories. Over 1-3 months, the key catalyst is retailer data: if premium monitors and desktop accessories are growing through mix, that supports margin expansion; if growth is being bought with promotions, ASP compression will show up first in smaller hardware names. Over 6-18 months, the structural risk is that category growth persists but value migrates to brands that own the user workflow, not the hardware bill of materials.
The contrarian point is that the Apple angle may be overstated. A product designed for the Apple desktop ecosystem is often a distribution tactic, not evidence of a large new end market, and that matters because investors tend to extrapolate ecosystem narratives too far. The thesis is falsified if AAPL channel partners report rising accessory attach without a corresponding increase in promo intensity or if monitor pricing holds despite broader SKU proliferation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in AAPL; treat this as a monitor, not a catalyst. Reassess only if next 1-2 quarters of Mac-related channel data show higher accessory attach or improved PC ecosystem retention.
- If you want exposure, consider a small relative-value short in LOGI versus long AAPL for 1-3 months: the setup favors ecosystem strength at the platform level while accessories face brand-level pricing pressure. Risk/reward is modest, not high conviction.
- Set a watch item on DELL and HPQ into upcoming PC/monitor commentary: if premium monitor demand is rising without promo support, that is constructive for hardware mix; if not, it suggests margin pressure and no durable read-through.
- Avoid paying up for pure-play peripheral names on this news alone. Wait for evidence of sustained sell-through and inventory tightening; otherwise the more likely outcome is SKU proliferation with limited incremental profit pool.
More News
- Zoom and big financial firms add ‘Proof of Human’ badges from Sam Altman’s World to stop fraud and deep fakes
- TechCrunch Mobility: Rivian’s next act
- From the Royole FlexPai to the iPhone Duo: How the modern foldable phone has evolved
- Taiwan Semiconductor Just Proved Why It's a Top AI Investment
- What to Expect in Markets This Week: Meta, Tesla Report; Airlines, Streaming Giants' Results Due
- Breakfast News: The Sunday Edition