
Sistema de colaboración "Huawei + Partners", centrado en el cliente, para escalar la IA en la industria
Source: PR Newswire
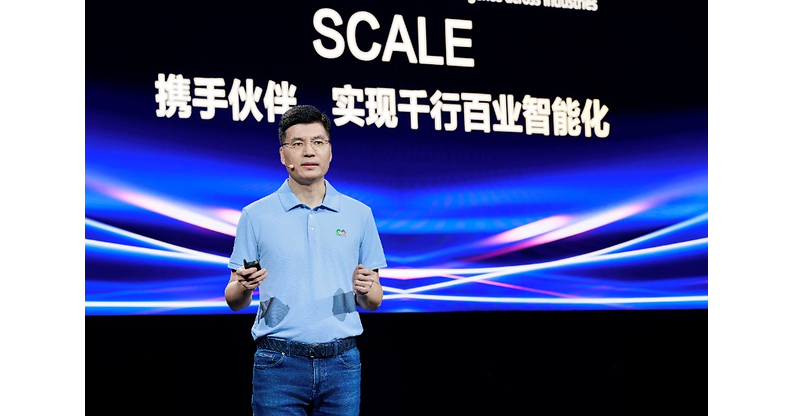
Huawei launched its SCALE partner-support system at HUAWEI CONNECT 2026 to help customers move from isolated AI pilots to large-scale industrial AI deployment. The company said partners have developed more than 100 scenario-based solutions across eight industries, supported by reference architectures for 48 high-value scenarios and over 130 global customer case studies. Huawei also reported training more than 50,000 AI professionals over the past three years, strengthening its partner ecosystem and local service-delivery capabilities.
Analysis
The investable implication is not an immediate earnings event but a potential acceleration of sovereign and enterprise AI-stack substitution in markets where Huawei has distribution leverage. If its partner enablement lowers deployment friction, the pressure falls most directly on Dell (DELL), HPE (HPE), Cisco (CSCO) and VMware-dependent private-cloud integrators in emerging markets, where service coverage and local implementation capacity often determine vendor selection more than benchmark chip performance. The second-order beneficiary is China’s domestic server, networking and storage supply chain, although listed-company revenue capture remains opaque and should not be assumed from a vendor press release.
For Nvidia (NVDA) and AMD (AMD), the relevant risk is geographic mix rather than aggregate AI demand: a more complete Huawei software, integration and support layer can make restricted or politically sensitive accounts less likely to wait for access to Western accelerators. That is a 6-18 month share-risk, not a near-term volume shock; NVDA’s constrained-China revenue base and continued global supply tightness limit immediate P&L damage. The more tangible near-term read-through is that AI infrastructure demand may increasingly shift from discrete GPU purchases toward integrated, service-heavy deployments, favoring vendors with enterprise channels over component suppliers if capital spending broadens.
Consensus is likely to overread this as evidence of a near-term Huawei AI revenue inflection. Partner certifications, reference architectures and marketing portals do not establish utilization, project conversion, or recurring software/service economics; many industrial AI pilots fail at data integration and workflow redesign. A credible bearish signal for Western enterprise infrastructure would require evidence over the next 1-3 quarters of tender losses, declining China/emerging-market backlog, or management commentary tying pricing pressure to Huawei—not partner-count metrics.
No directional trade is warranted solely on this announcement. Use it as a monitoring catalyst for competitive displacement: the thesis becomes actionable only if enterprise AI deal cycles show Huawei winning multi-site production deployments rather than proof-of-concept projects, particularly in telecom, utilities, manufacturing and public-sector accounts.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- Maintain no event-driven position from this release; set a 1-3 month diligence alert for DELL, HPE and CSCO earnings calls: downgrade the group only if management cites China or emerging-market order weakness, channel inventory pressure, or Huawei-related discounting.
- For a structural hedge to concentrated NVDA exposure, consider a small 6-12 month long HPE / short DELL pair only after confirmed enterprise AI backlog divergence. Thesis: HPE’s integrated compute and service model should be more resilient than DELL’s hardware-heavy channel exposure; exit if HPE AI systems order growth fails to exceed DELL’s by at least 10 percentage points.
- Avoid shorting NVDA on this development alone. Reassess only if China/ex-China restricted-market revenue weakens materially while Huawei shows independently verified production-scale deployments; the falsifier is sustained NVDA data-center growth and stable gross margin despite competitive headlines.
- Monitor China-listed AI infrastructure proxies and semiconductor ETFs for evidence of order conversion rather than promotional activity. A tradable long requires disclosed backlog, utilization, or operating-cash-flow improvement; absent those data, treat any sympathy rally as high-risk narrative beta.
More News
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year
- Factbox-Key issues for this week’s Trump-Xi summit in Washington
- Paramount agrees invest $1.5 billion in domestic movies and create a board for editorial independence at CNN, CBS as part of deal for Warner Bros.
- Here's who we know is going to the Trump-Xi dinner so far