
Shanghai Electric consigue su primer pedido internacional de turbinas de gas de gran potencia
Source: PR Newswire
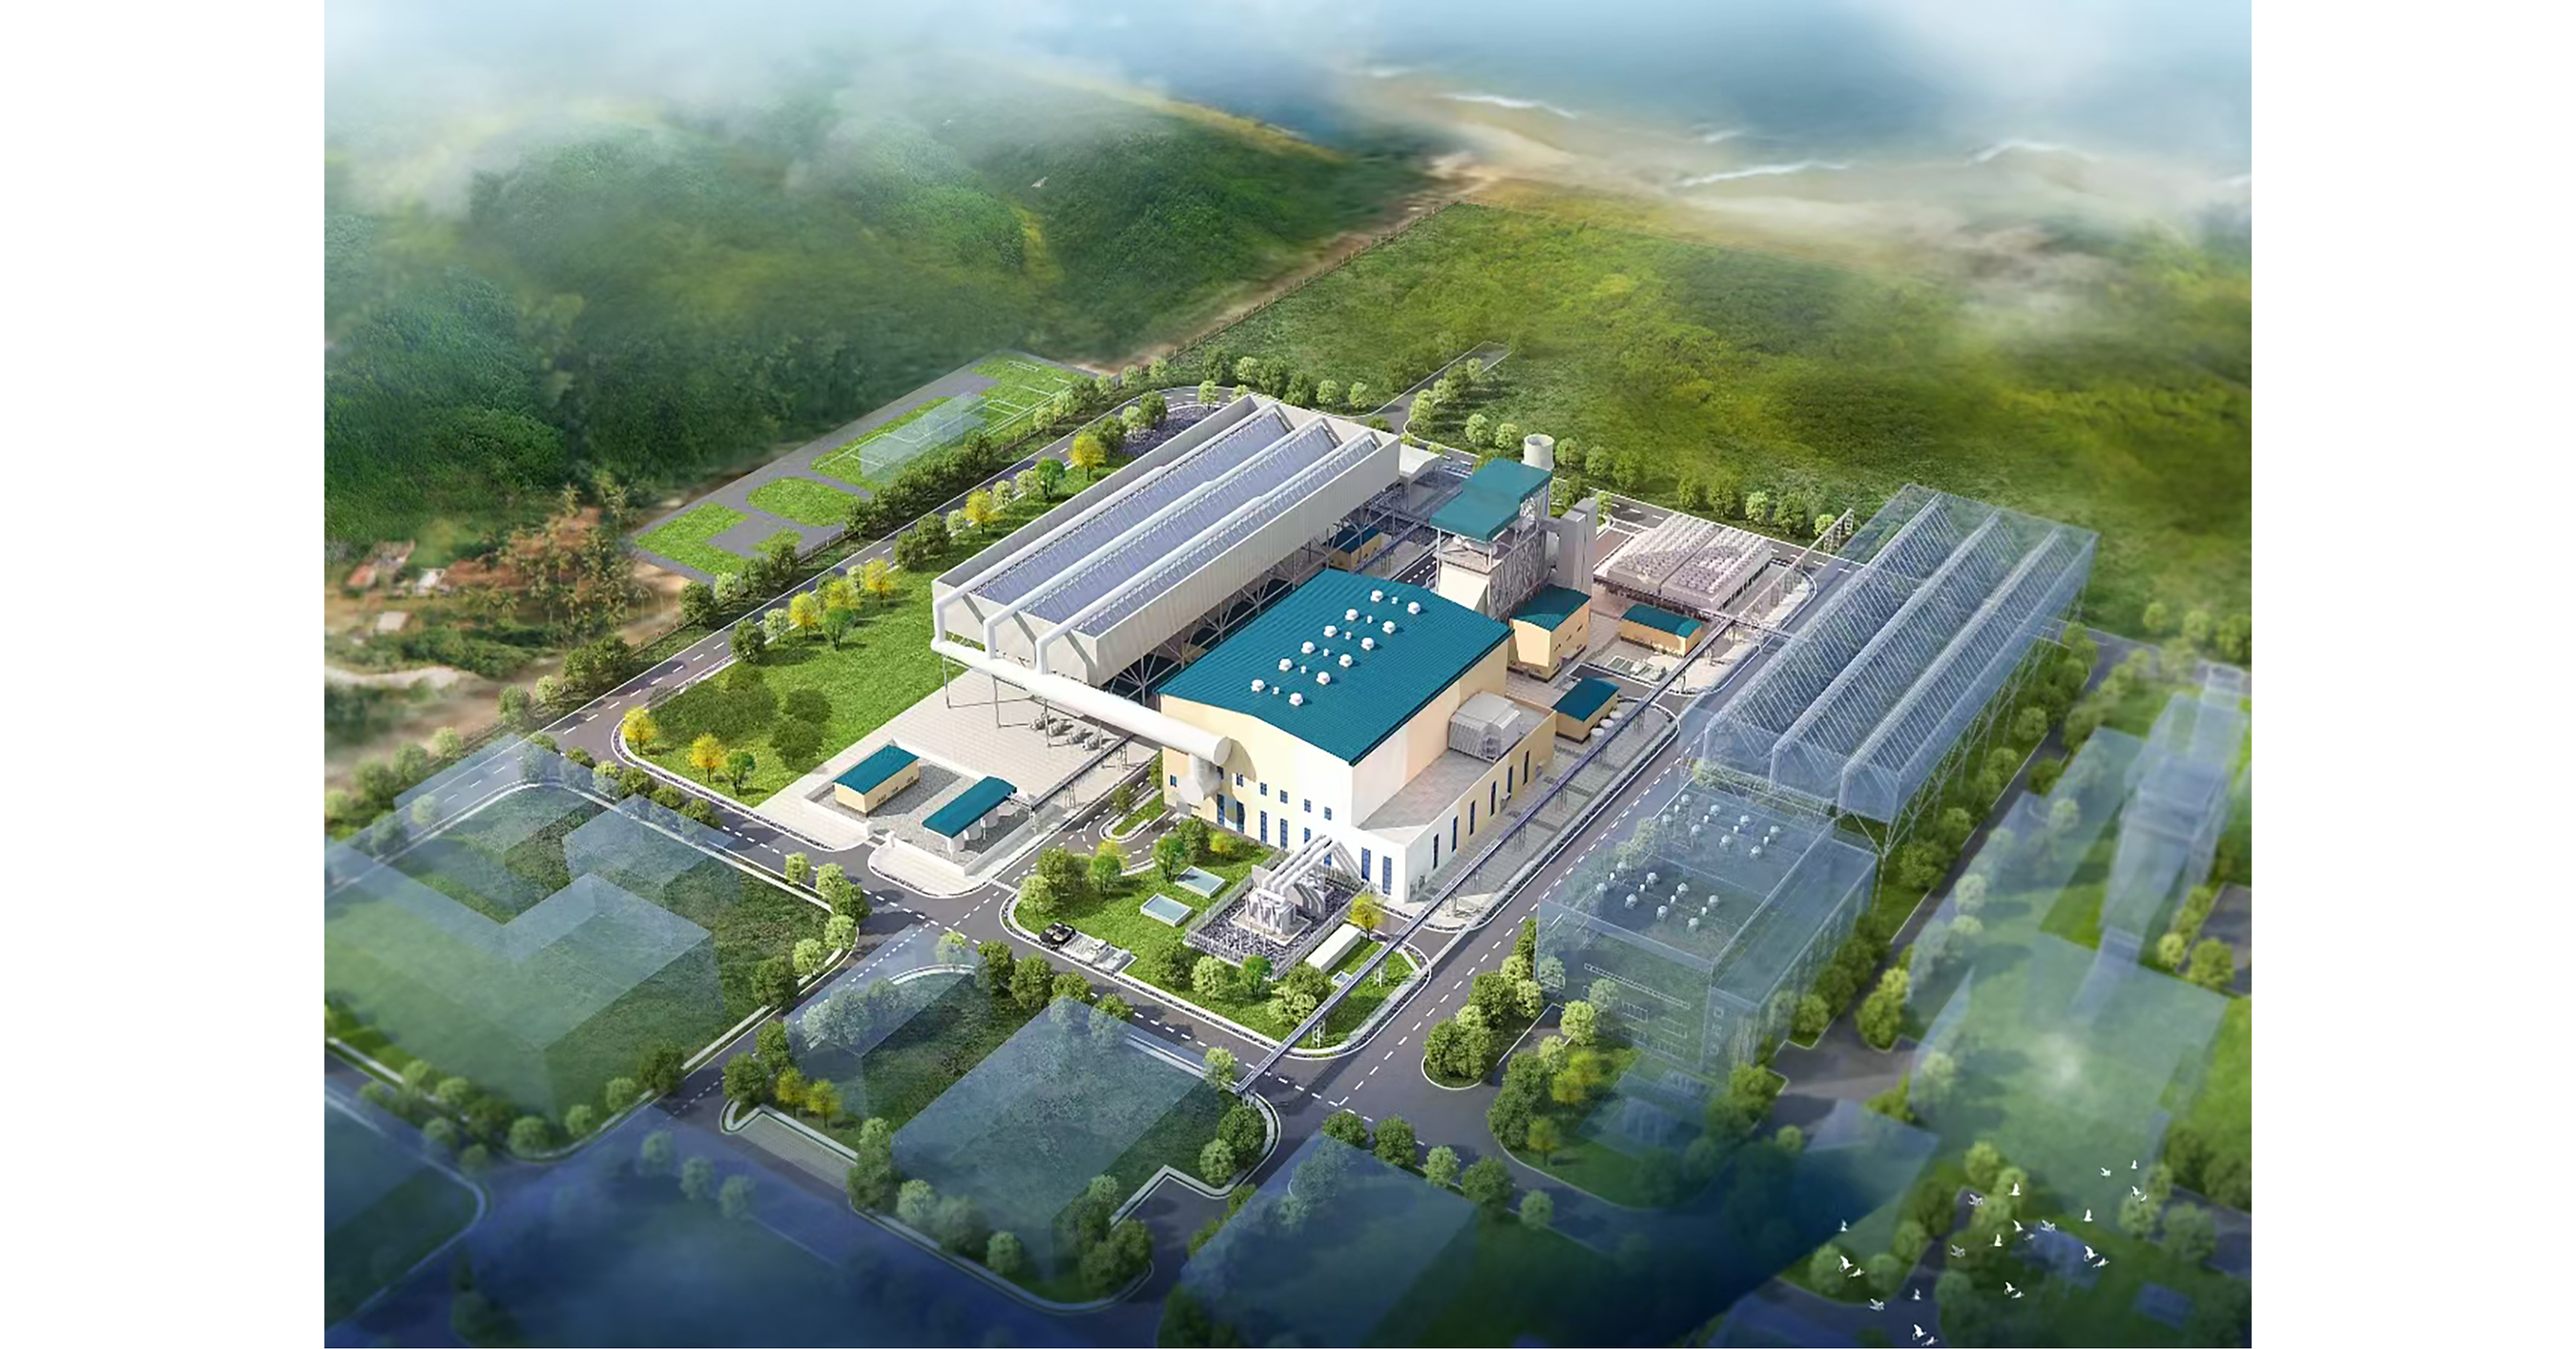
Shanghai Electric won its first international order for high-power gas turbines, securing the EPC contract for Unit 3 of the 500MW Sarawak Samalaju combined-cycle gas project in Malaysia. The agreement includes a 25-year long-term service contract covering all major equipment, which Shanghai Electric will manufacture internally and maintain exclusively. The win validates the company's 300MW-class turbine technology internationally and could support further orders, with developers in Indonesia, Thailand, the Philippines and Vietnam expressing interest; new turbine deliveries are available from 2028.
Analysis
The strategic value is less the initial EPC revenue than referenceability: a successful non-domestic baseload installation can lower buyer-perceived technology and service-risk across Southeast Asian tenders. Shanghai Electric's vertically integrated model should attach higher-margin aftermarket revenue over time, but it also concentrates warranty, performance-guarantee, and spare-parts liabilities on its own balance sheet. The order is therefore a potential multiple-expansion catalyst only after disclosure of contract value, advance-payment terms, project margin, and any parent/sovereign guarantees.
For GE Vernova (GEV), Siemens Energy (ENR) and Mitsubishi Heavy (7011), the immediate earnings impact is immaterial, but the competitive signal matters in a tight large-turbine supply market. A credible Chinese alternative could pressure bid pricing and long-term service attach rates in lower-cost ASEAN markets over the next 12-36 months, while potentially expanding the overall CCGT pipeline by making projects financeable at lower capex. The contrarian case is that export turbine economics remain unproven: first-of-kind international execution, gas availability, grid integration and sanctions/export-control exposure could turn a showcase project into a costly warranty event.
Near-term equity upside in Shanghai Electric is likely constrained by the absence of disclosed economics and a delivery cycle extending beyond the market's usual earnings horizon. The key 1-3 month catalyst is a formal contract filing with value, margin and financing detail; the 6-18 month catalyst is follow-on ASEAN awards or third-party performance validation. Thesis failure would be indicated by project delays, provisions for EPC guarantees, a weak operating-cash-flow conversion profile, or no incremental export orders despite the stated regional interest.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Key Decisions for Investors
- Place Shanghai Electric (2727 HK / 601727 CN) on an event-driven watchlist rather than initiate immediately; buy only following a filing that demonstrates contract economics and customer-payment protection. Target a 6-18 month position if at least one additional ASEAN award validates repeatability; exit on material project-delay disclosures or elevated warranty provisions.
- Maintain a modest long GEV versus short 2727 HK only if Shanghai Electric materially outperforms on the announcement without disclosed price or margin data. The pair expresses skepticism that one export reference closes the technology-service credibility gap; cover if Shanghai Electric discloses attractive LTSA economics or wins a second external order within six months.
- Monitor ASEAN CCGT tender activity and large-frame turbine lead times as a sector signal. Persistent capacity shortages favor GEV, ENR and 7011 pricing power despite a new entrant; evidence of Shanghai Electric winning multiple competitively bid projects would be an early warning to reduce exposure to those incumbents' ASEAN service-margin assumptions.
More News
- Baker Hughes sees no slowdown in energy projects despite higher rates as AI buildouts stoke LNG demand
- U.S. stock futures slide on calls to slow AI development, M.East escalation
- Oil prices rise after Saudi Arabia shut down critical pipeline that bypasses Strait of Hormuz
- Z.ai shares tumble over 10% after $5 billion fundraising, its second major raise in two months
- Why is Samsung Electronics stock sliding today?
- Big AI sets out its terms for regulatory capture and calls it ‘Pace the frontier’