
Mindray North America Celebrates Grand Opening of Expanded Mahwah Warehouse
Source: PR Newswire
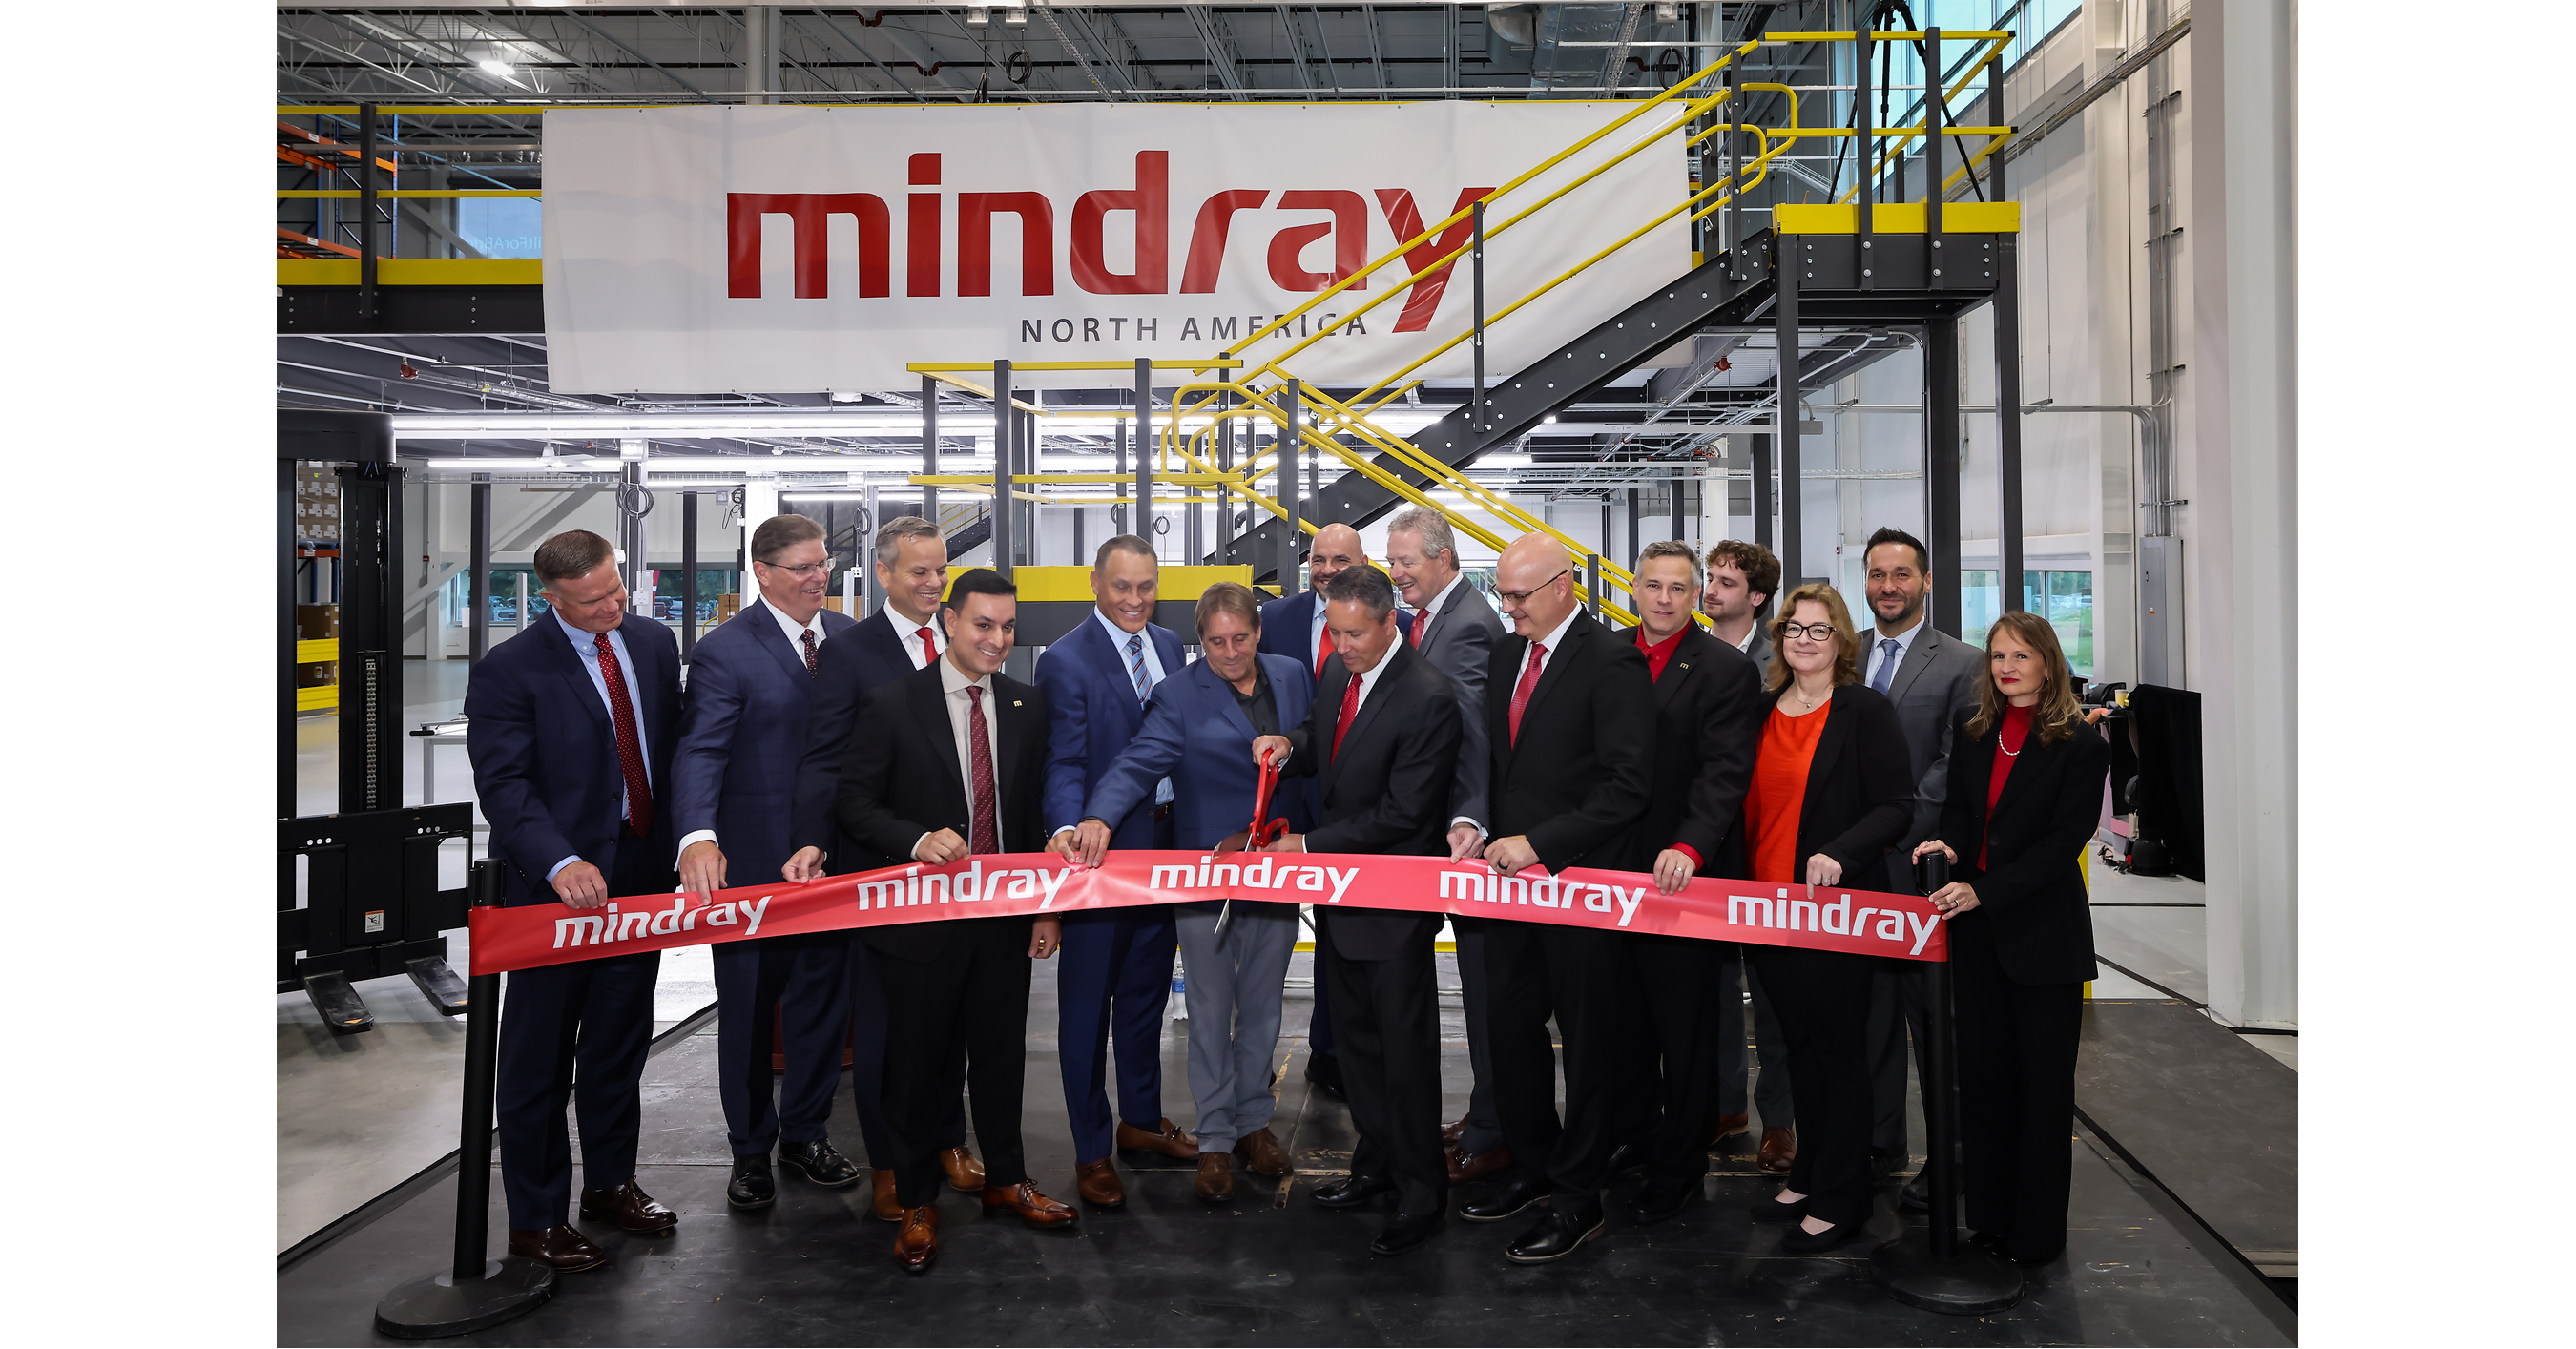
Mindray North America completed a multi-million dollar expansion, consolidating off-site operations into a single centralized facility to streamline logistics, improve order fulfillment, and shorten delivery times. The move supports capacity growth as Mindray expands into new product categories, including a new ventilator line with planned extensions over the next 18 months. Management also tied the consolidation to sustainability benefits by reducing trucking activity and lowering the customer shipment carbon footprint.
Analysis
This reads more like a supply-chain and execution upgrade than a demand inflection. In medtech, that distinction matters: better fill rates and shorter lead times can win share in critical care categories where hospitals punish stockouts and delayed replacements, but the near-term P&L lift is usually incremental rather than transformative. The biggest financial lever is likely modest freight/handling savings and improved working-capital turns, not a step-change in top-line growth.
The second-order opportunity is competitive: if service levels improve while the company rolls out ventilators and adjacent categories, it can pressure incumbents with less reliable fulfillment in tender-heavy accounts. That creates a path to incremental share from GEHC and PHG in ICU/respiratory equipment, especially where procurement teams value delivery certainty as much as product specs. But if this is mostly capex and facility rationalization, the market may be over-penalizing or over-rewarding the announcement before any revenue evidence appears.
The main risk is timing. Over the next 1-3 months, investors should focus on order conversion, backlog, and gross margin absorption; over 6-18 months, the real test is whether new categories generate recurring installed-base revenue rather than just more SKU complexity. A failure to show faster growth or lower logistics expense would turn this into a cost-center story, while any disruption at a centralized site would be a meaningful operational single-point-of-failure risk during product launches.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade in MEDD: the signal is positive but too small to justify a directional position before evidence of order/share gain shows up.
- Set a 1-2 quarter alert on MEDD for backlog, revenue growth, and distribution expense as a % of sales; if logistics costs fall 50-100 bps and growth re-accelerates, re-evaluate a long position.
- If the stock sells off on the capex headline, consider a relative-value entry: long MEDD / short GEHC or PHG, targeting modest 5-8% outperformance over 3-6 months if service levels translate into share gains.
- Watch for any supply disruption or launch delay at the centralized facility; a miss on delivery times or margin would falsify the bullish operational thesis quickly.
- Do not buy the ESG angle as a primary thesis; trucking reduction is a side benefit, not a valuation driver unless it materially changes margins or customer win rates.
More News
- Iran-backed Houthis strike Yemen’s Aden: What that means
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'