
Zoomlion Marks 34th Anniversary, Highlighting Milestones in Innovation and Global Growth
Source: PR Newswire
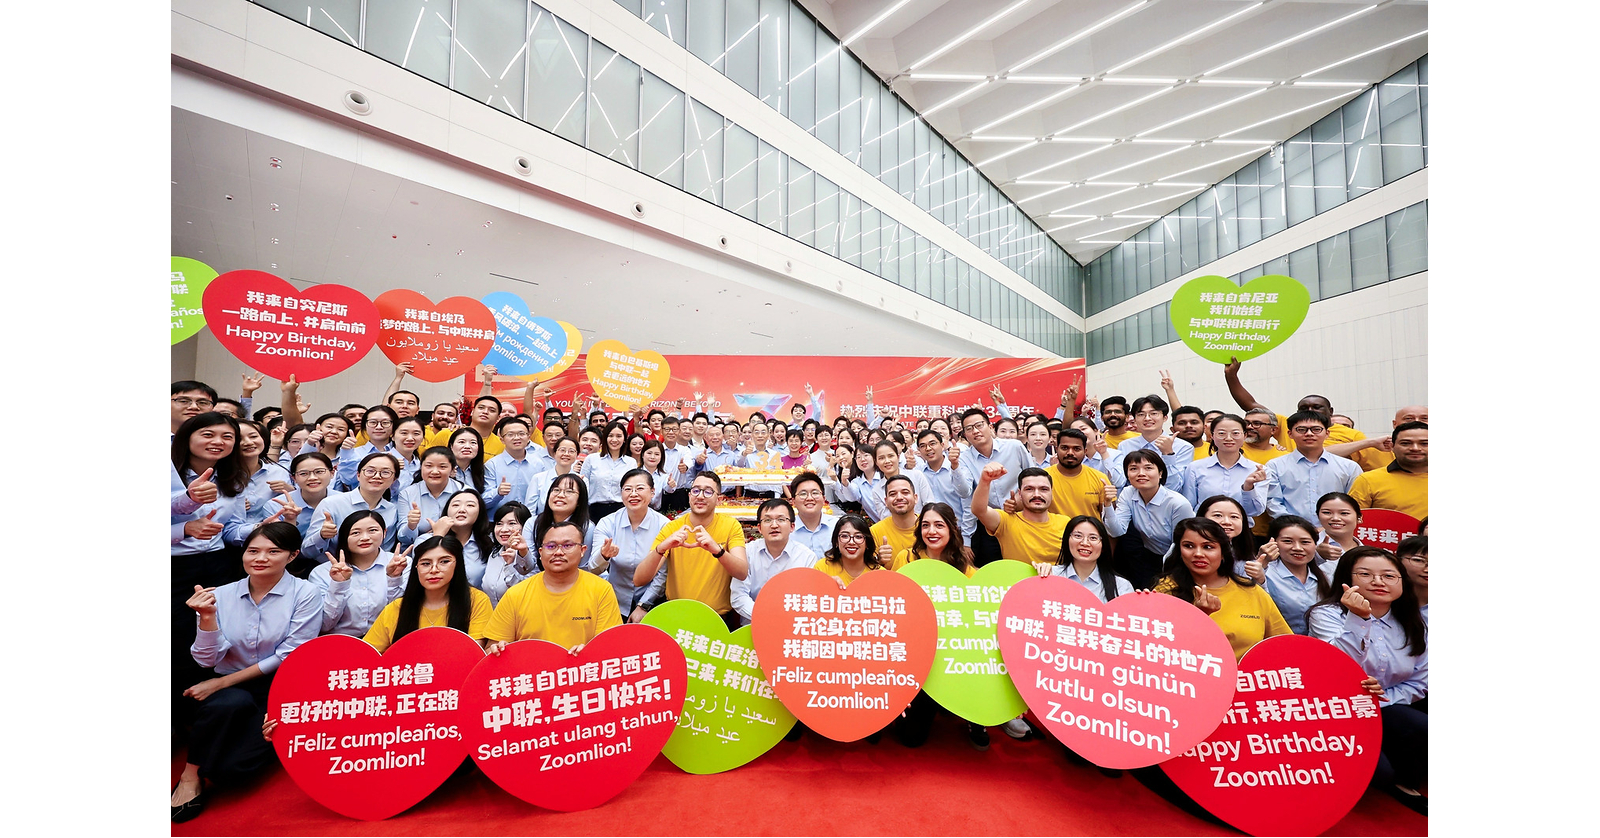
Zoomlion marked its 34th anniversary, highlighting its evolution into a global construction, mining and agricultural equipment supplier serving more than 170 countries and regions. International revenue now represents nearly 60% of total sales, supported by 11 overseas R&D and manufacturing bases. The company plans further investment in high-end equipment, AI, robotics, new-energy technologies and localized global operations as it enters its 35th year.
Analysis
This is not an investable catalyst by itself: anniversary communications provide no order intake, pricing, backlog, receivables, or capex disclosure. The relevant equity question is whether overseas expansion is becoming self-funding rather than consuming working capital through inventory, dealer financing, and localized service build-outs. For Zoomlion (1157 HK/000157 SZ), evidence of faster international revenue growth accompanied by falling receivables days would justify a multiple re-rating; growth without cash conversion would instead raise the risk that reported mix improvement masks balance-sheet strain.
The competitive implication is more meaningful for Chinese equipment exporters than for global incumbents. Zoomlion, SANY Heavy Industry (600031 CH), and XCMG Machinery (000425 CH) can use China-based component sourcing and local assembly to pressure mid-market crane, concrete, aerial-work-platform, and agricultural-equipment pricing in emerging markets. CAT and Komatsu (6301 JP) are less exposed in premium dealer-supported segments, but could face margin pressure in price-sensitive markets if Chinese competitors prove able to sustain parts availability and residual values over a full cycle.
Near term, the likely stock driver remains China infrastructure and property-linked equipment demand rather than corporate branding. Over 1-3 months, monitor monthly export data, dealer inventory, and receivables impairment; over 6-18 months, localization can be structurally positive only if overseas gross margin exceeds the added cost of service networks, compliance, and FX hedging. The AI/new-energy messaging should be treated as capex risk until management quantifies unit-cost savings, product premiums, or returns on invested capital.
Contrarian view: consensus may over-credit overseas mix as an automatic de-risking of China cyclicality. Emerging-market construction demand is often correlated with commodity prices, dollar liquidity, and Chinese project finance, creating a common downturn exposure rather than true geographic diversification. A meaningful deterioration in export orders, a rise in overdue dealer receivables, or renewed price competition led by SANY/XCMG would falsify a bullish internationalization thesis.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate directional trade on the release; maintain 1157 HK/000157 SZ as a watch item until the next results disclose overseas order growth, segment margin, inventory turns, and receivables aging.
- If results show overseas growth above domestic growth while operating cash flow and receivables days improve sequentially, initiate a 6-12 month long Zoomlion versus short XCMG (000425 CH). The thesis is superior international cash conversion; exit if receivables or inventory expand faster than revenue for two reporting periods.
- For a more liquid global expression, monitor a long CAT / short Chinese construction-equipment basket only if export pricing pressure becomes evident. CAT's dealer/service moat should outperform in a weak-demand environment; the trade is invalidated by sustained Chinese share gains in premium markets without CAT margin compression.
- Treat AI, robotics, and new-energy equipment claims as a diligence trigger rather than a valuation catalyst. Upgrade only after management provides product-level adoption, gross-margin, and incremental-capex data; absent that evidence, avoid paying a technology premium for 1157 HK.
More News
- UK Prime Minister Burnham says Iran 'played a part' in British air base incident
- South Korea’s exports hit record high on AI boom
- Asian stocks dip, bonds in focus after torrid September
- US judge approves settlement allowing Paramount to acquire Warner Bros
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)