
EPAM Reports Results for Third Quarter 2026
Source: PR Newswire
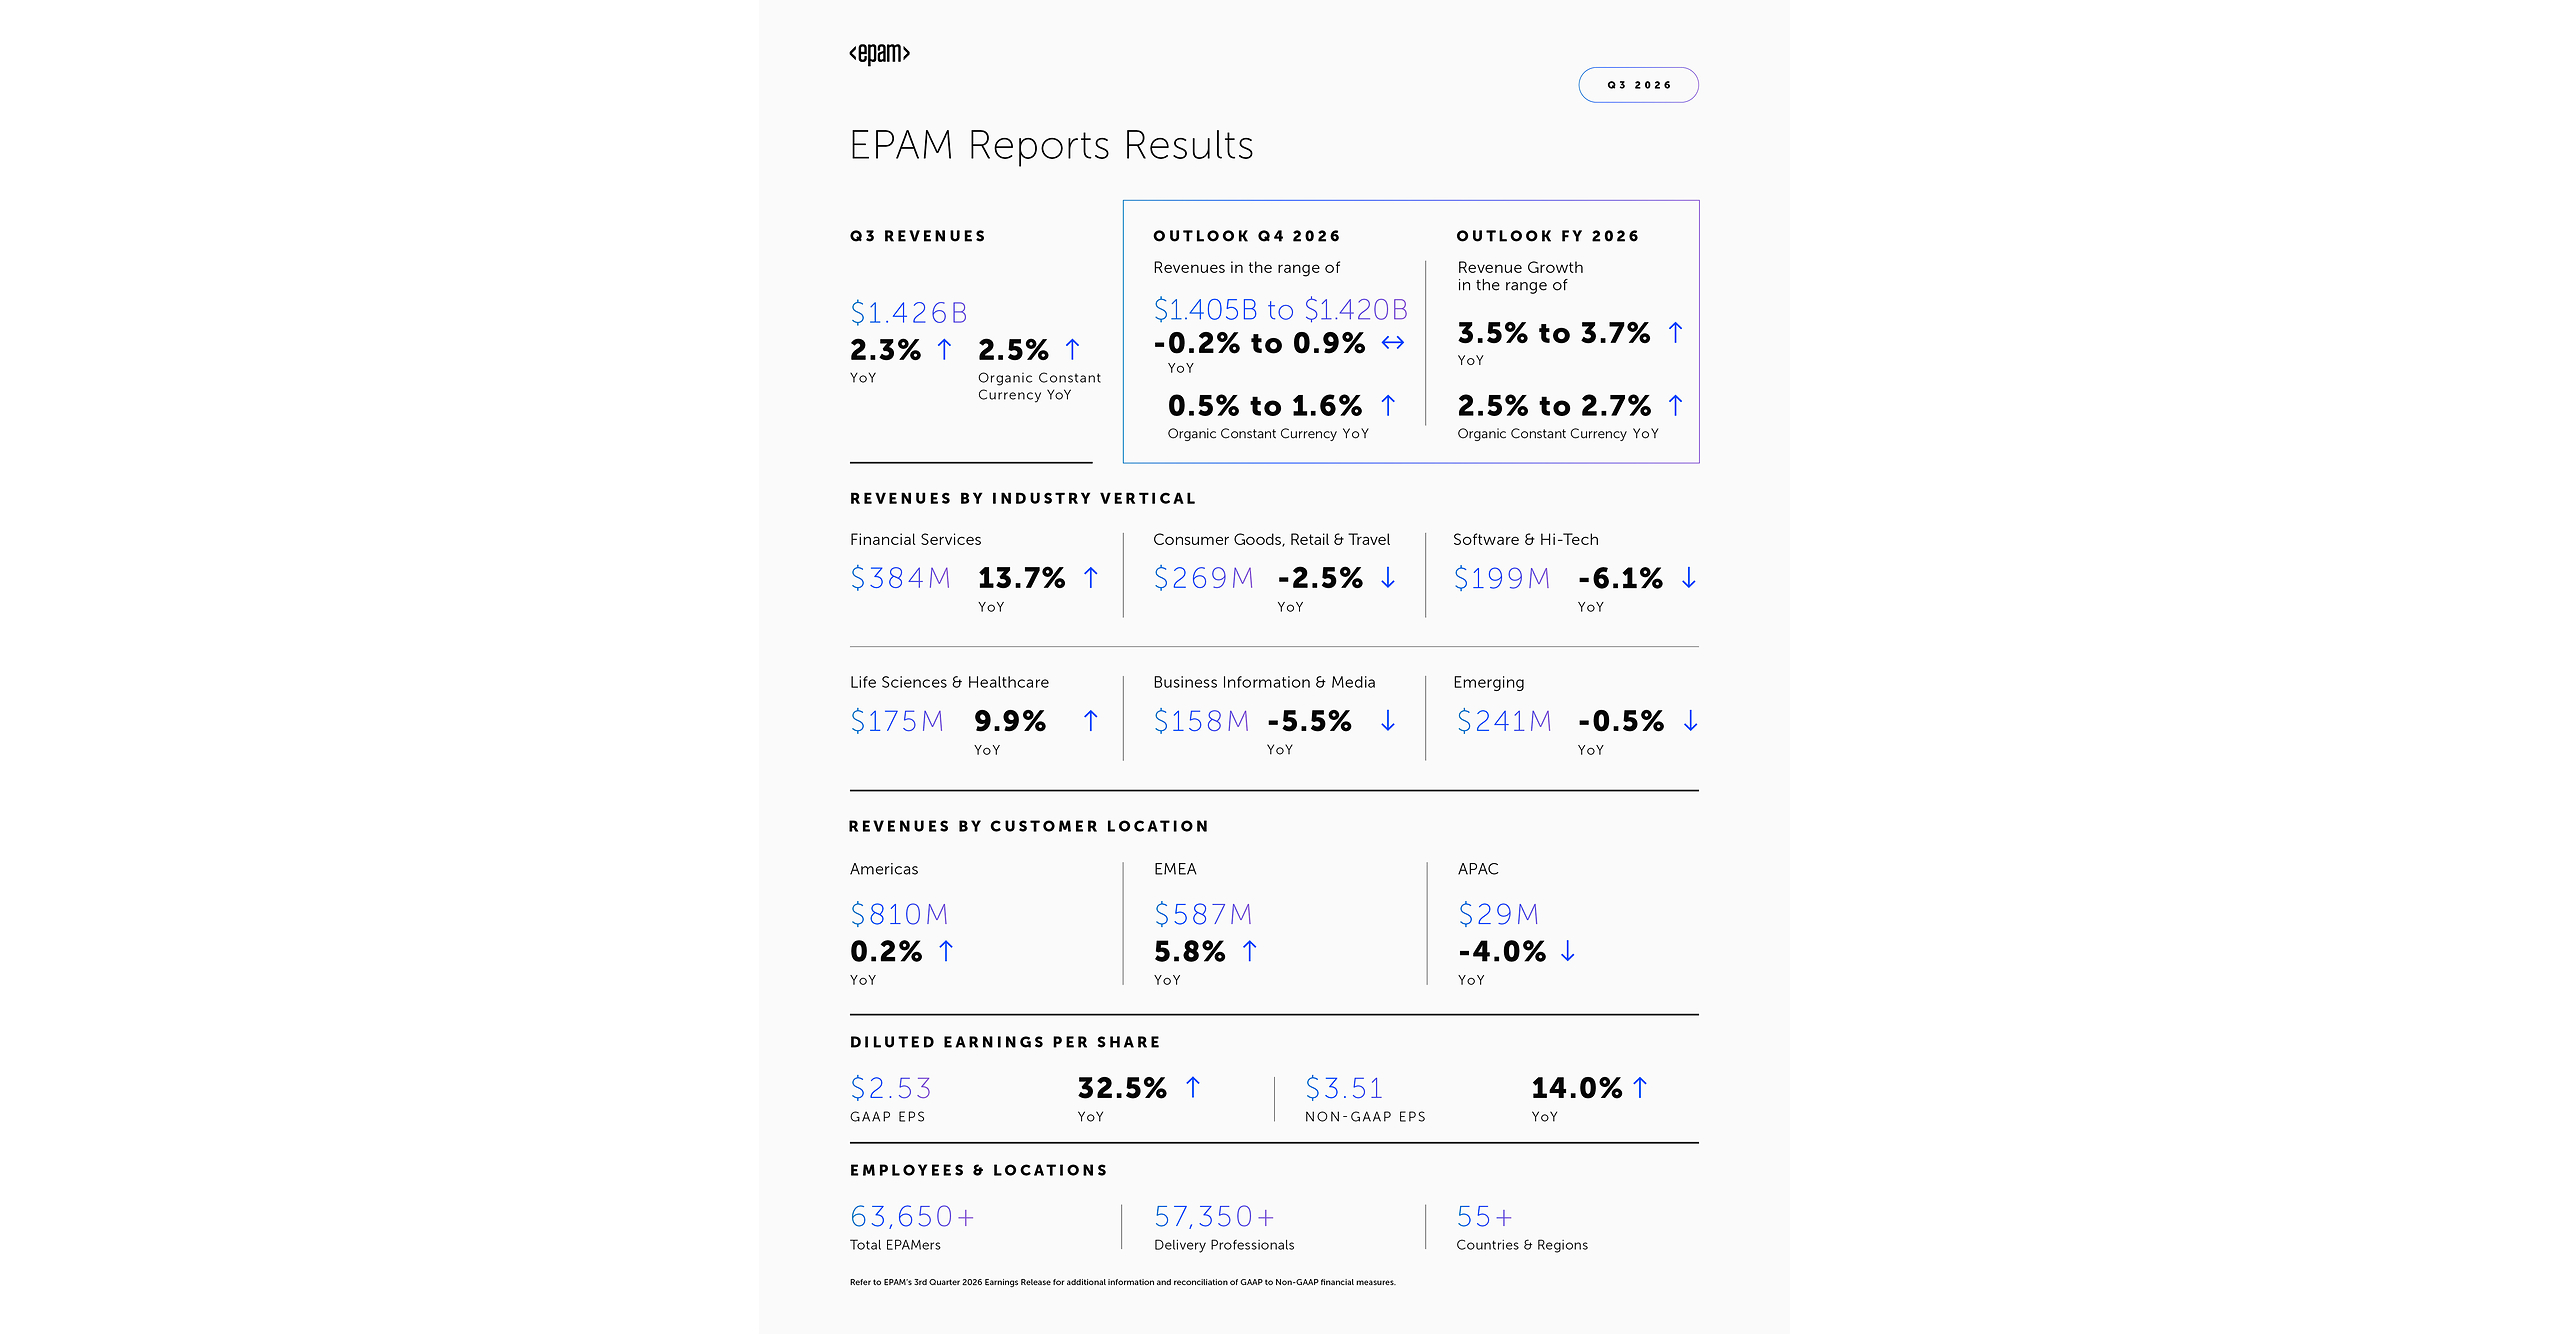
EPAM reported Q3 2026 revenue of $1.426 billion, up 2.3% year over year, while GAAP operating margin rose to 12.3% from 10.4% and GAAP diluted EPS increased 32.5% to $2.53. It raised its full-year 2026 revenue-growth outlook to 3.5%–3.7% and EPS outlook to $8.41–$8.49 GAAP and $13.23–$13.31 non-GAAP; Q4 revenue guidance implies a year-over-year change of (0.2)% to 0.9%. EPAM also approved $1.5 billion in incremental repurchase authorization, plans a $500 million accelerated repurchase, and committed to return at least 50% of free cash flow annually from 2027 through 2029; operating cash flow was lower year over year for the first nine months.
Analysis
The setup is mixed, not a clean growth inflection: margin gains and lower share count support EPS, while the Q4 revenue range points to near-flat year-over-year growth. The immediate reaction may favor the margin/EPS beat and announced ASR; over the next 1–3 months, the test is whether client demand stabilizes rather than whether buybacks continue. The ASR can support per-share results, but it is not evidence of improving demand: the company plans to use cash and its credit facility, while nine-month operating cash flow was lower year over year and cash balances declined. Verify working-capital drivers and free-cash-flow conversion before underwriting the 2027–29 capital-return commitment.
A further quality-of-growth check: delivery headcount increased while revenue growth remained low. That may reflect investment for anticipated projects, or underutilization if demand does not recover; utilization and bookings/backlog are needed to distinguish the two. Also, the non-GAAP adjustments remain sizable, including stock compensation and amortization, so headline non-GAAP margin should not be treated as fully equivalent to cash earnings. AI services are a potential structural differentiator, but the release provides no quantified AI revenue or conversion evidence. The contrarian risk is over-crediting the AI narrative and buyback for a growth recovery that guidance does not yet show.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase EPAM solely on the EPS beat or ASR announcement. Treat the near-term signal as mildly positive but growth-constrained; reassess after Q4 results and the next guidance update.
- Watch Q4 revenue against the $1.405–$1.420 billion range, organic constant-currency growth, and delivery utilization. A miss or further weakening in bookings would falsify the margin-led stabilization thesis and favor reducing exposure.
- Monitor operating cash flow, receivables/contract assets, cash, and any credit-facility borrowing around the $500 million ASR. Weak cash conversion alongside continued repurchases would raise the risk that capital returns are outrunning internally generated cash.
- For a conditional long, require evidence that revenue demand is bottoming while non-GAAP operating margin holds near the guided range; absent that confirmation, prefer a watch position over a directional trade. No valuation or price data are supplied to define an entry level or risk/reward.
More News
- Stocks making the biggest moves midday: Micron, Tesla, Tripadvisor, AppLovin, Nvidia & more
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms
- Qualcomm slides 9% after earnings, leading post-election chip stock sell-off
- Costco is taking aim at its May record high — how it got here and where's it going
- Neocloud IREN says $4 billion in annualized revenue being delayed due to customer request