
Israel’s Supreme Court Overturns Election Ban on Arab Parties
Source: Bloomberg
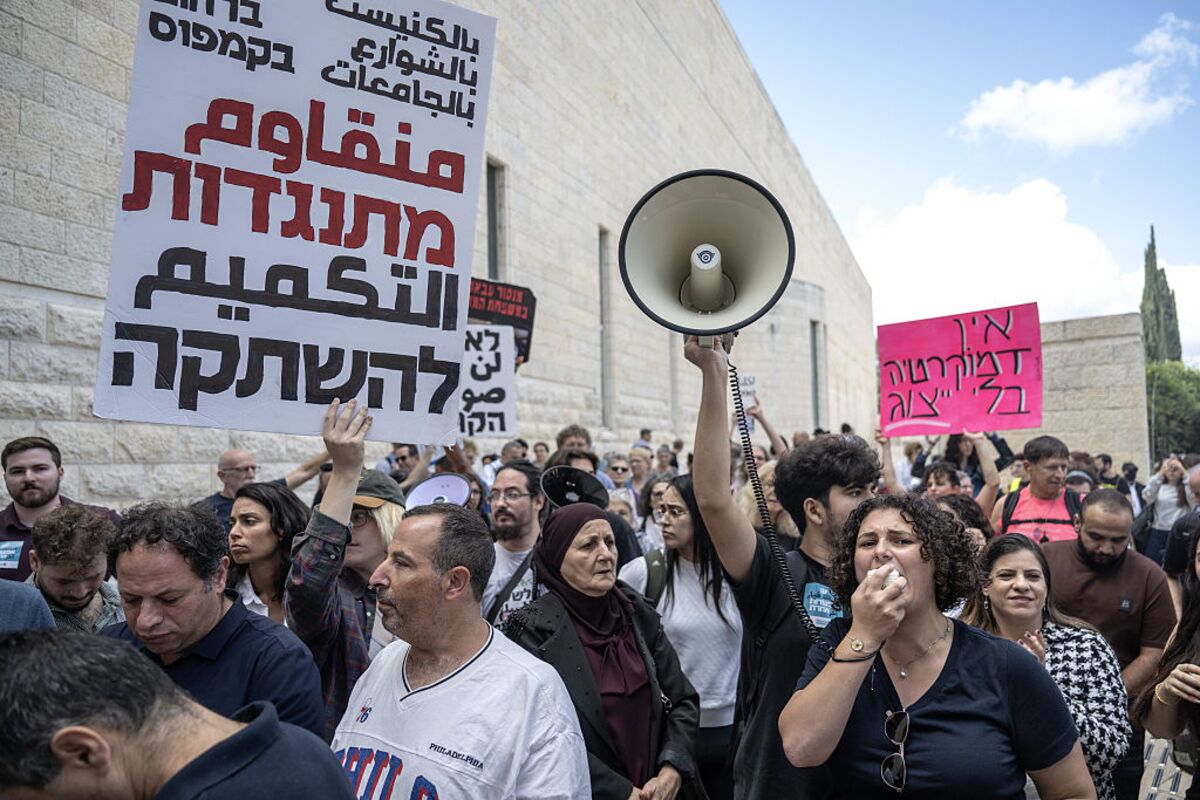
Israel’s Supreme Court unanimously overturned the central elections committee’s ban on all four Arab-majority parties contesting the Oct. 27 election. The reversal constrains a committee controlled by Prime Minister Benjamin Netanyahu and his right-wing bloc, preserving Arab-party participation and adding political uncertainty ahead of the vote.
Analysis
This is primarily a reduction in domestic political-tail-risk rather than a direct earnings catalyst. By preserving parliamentary representation for Arab voters, the ruling marginally lowers the probability of an election outcome that produces an uncompromising right-wing governing coalition; that matters most through the risk premium embedded in Israeli equities, the shekel, and sovereign credit spreads rather than through near-term fundamentals.
The more relevant market mechanism is coalition arithmetic. If participation and representation are meaningful, the probability of policy outcomes that intensify regional-security, settlement, or institutional-conflict risk declines at the margin; Israeli banks and domestically oriented real estate are the most sensitive listed exposures because they reprice quickly to sovereign-risk and funding-cost moves. Conversely, a contentious campaign, weak turnout, or post-election deadlock could still widen Israel CDS and pressure ILS, offsetting any immediate relief.
Consensus should avoid treating the judicial ruling as a durable institutional-stability signal. The decision removes one electoral exclusion risk, but it may also sharpen political polarization and increase the odds that the election becomes a referendum on judicial constraints. Over the next 1-3 months, polling, Arab turnout indicators, and coalition negotiations will matter more than the ruling itself; the 6-18 month implication depends on whether the resulting government moderates or escalates institutional confrontation.
There is no high-conviction standalone trade from this event absent observable movement in Israeli assets. A sustained ILS appreciation and tighter five-year Israel CDS following credible turnout/polling data would validate a tactical risk-on expression; renewed coalition instability, a material deterioration in security conditions, or a 25-50bp widening in sovereign spreads would falsify it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No immediate directional position: treat this as a monitoring event, not an investable earnings catalyst, given low stated impact and no asset-specific transmission yet.
- Set alerts on USD/ILS and five-year Israel CDS through the election: consider a tactical long ILS versus USD only if USD/ILS breaks lower alongside a sustained 15-20bp CDS tightening; target a 2-3% currency move over 1-3 months, with a stop if CDS reverses wider by 25bp.
- Use EIS as the liquid equity proxy only after polling confirms a less confrontational coalition path: a 3-5% pullback with stable CDS offers better entry than chasing a headline response; exit if security escalation or coalition deadlock drives a renewed sovereign-risk repricing.
- For existing exposure to Israeli banks or property-linked names, hedge event risk into election and coalition-negotiation dates rather than reduce on this ruling alone; their downside is more sensitive to funding-cost and risk-premium widening than to the court decision's direct effect.
More News
- Iran’s currency is getting obliterated as the regime is about to run out of oil to sell and can’t even get its money from customers
- Trump taps Director of National Intelligence Jay Clayton as AI czar: WSJ reports
- Brazil’s Lula and Bolsonaro close campaigns ahead of critical election
- U.S. debt is increasingly at the mercy of the market as interest costs surge while elections add more risk to the debt ceiling, ratings agency warns
- After threatening to ban U.S. exports of diesel fuel, Trump admits ‘we were never going to do it’
- G7 Fuel Release Offers Short Term Price Relief
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Automating Financial Model Updates: A Source-Controlled Workflow
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts