
Paul Mueller Company: Even With A Decline In Backlog, It's Too Attractive To Ignore
Source: seekingalpha.com
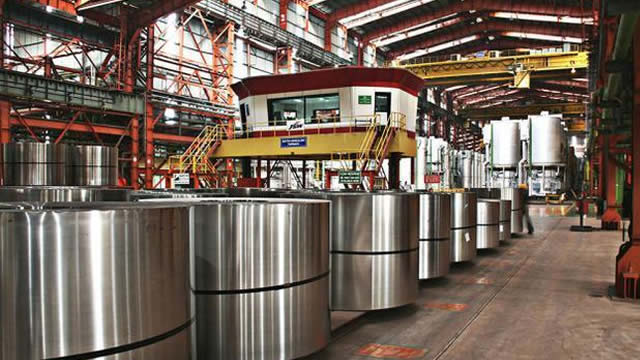
Paul Mueller Company’s H1 2026 revenue rose 21.8% to $160.2M, supporting a continued “strong buy” view on compelling value and a pristine balance sheet. However, net income and cash flows fell due to higher costs and one-off events. The nearly fully utilized new module fabrication building should raise workloads and reduce reliance on expensive contractors, providing an offset to near-term cost pressure.
Analysis
The setup is less about headline growth and more about operating leverage timing. A company with little balance-sheet stress can absorb temporary margin noise, but the market usually waits for proof that incremental revenue is converting into cash rather than just backlog and working capital. The near-full internal fabrication build-out matters because it should reduce dependency on outsourced contractors, which is usually a hidden margin leak; if utilization stays high, the next step change is likely in gross margin, not revenue.
Second-order winners are customers who value lead-time certainty and quality consistency, because internal capacity tends to improve schedule control and shorten project slippage. The losers are third-party fabricators and job shops that had been filling capacity gaps; if MUEL is insourcing more of the work, that can compress pricing in the local outsourced module market. The key risk is that higher activity also raises inventory and receivables before cash conversion catches up, so the pristine balance sheet could still see working-capital drag for 1-2 quarters even if the business is healthy.
The market may be underestimating how cyclical the rerating will be: small industrials rarely re-rate on revenue growth alone, but they can re-rate quickly once contractor spend falls and margin inflects. The contrarian view is that the recent cash-flow softness is not a red flag if it is just the cost of filling a new asset; if that is true, the stock could be cheaper on normalized earnings than on current reported numbers. Falsifier: if the next two quarters show no gross-margin recovery or if the new facility remains only partially utilized, the self-help thesis is overstated.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Initiate a small starter long MUEL on weakness, with a 1-3 month horizon; thesis is that margin normalization should lag revenue by one quarter or two as contractor spend rolls off. Risk/reward is attractive only if you can tolerate near-term cash-flow noise.
- Add on the next earnings print only if gross margin and operating margin improve sequentially; if they do not, treat the move as a trap and avoid averaging down. Falsifier: no margin expansion despite higher utilization.
- Use a tight alert on working-capital metrics and contractor expense in the next filing; if receivables/inventory rise faster than sales, reduce or exit. This is the main balance-sheet risk over the next 1-2 quarters.
- If liquidity permits, consider a relative-value long MUEL / short small-cap industrial basket (IWM) for a quality-balance-sheet self-help tilt. The trade works best if industrial multiples compress while MUEL proves internal-capacity leverage.
- Avoid long-dated calls until management confirms the new fabrication building is translating into higher operating leverage; options are likely to be expensive relative to the limited near-term catalyst path.
More News
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Wall Street's fear gauge is ripping. Traders see it going even higher
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Index and ETF Holdings Data for AI Research
- Capital Intensity as Gravity: The AI Trade Enters Its Industrial Era (Looking at Q3 2025 Earnings in Tech)