
Union Pacific Rides on Operating Discipline Amid Freight Woes
Source: zacks.com
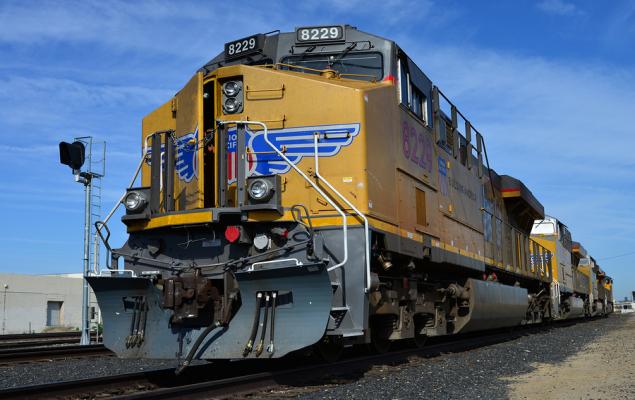
Union Pacific’s Q2 2026 revenue rose 12% year over year to $6.9B and adjusted EPS increased 13%; management raised its 2026 reported EPS growth outlook to the high single digits. Operating improvements included 5% higher freight car velocity, terminal dwell down 7% to a record-tied 19.7 hours, and workforce productivity up 5%. A prolonged freight downturn and challenging second-half coal demand remain headwinds, while pricing above inflation and shareholder returns support the outlook.
Analysis
The setup favors rail operators that can protect yield and lower unit costs while freight demand is soft, but the durability of UNP’s earnings growth matters more than the headline beat. The gap between revenue growth and modest carload growth makes mix, pricing, fuel surcharges, and other revenue components important to verify: if pricing is doing most of the work, the near-term margin cushion is real, but volume leverage remains unproven. UNP’s service improvements could also win intermodal freight from trucking, a potential pressure point for J.B. Hunt, though the article provides no lane-level share data to establish that shift.
Over the next 1–3 months, the key catalysts are carload trends, operating-ratio progress, and evidence that pricing remains above inflation as fuel surcharges and mix fluctuate. Coal weakness is a specific downside, while lower natural-gas prices can prolong the substitution risk. Over 6–18 months, continued productivity gains may support margins, but repeated records raise the bar for further efficiency improvements. The contrarian risk is that investors extrapolate cost discipline into durable EPS growth despite weak freight demand; guidance is not proof of a volume recovery. Dividend and repurchase headlines for CSX and JB Hunt are not, by themselves, evidence of relative undervaluation or stronger operating momentum.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Favor UNP tactically over freight-volume-sensitive exposure, but avoid chasing the positive guidance reaction; consider adding on weakness only if carloads stabilize and operating-ratio improvement continues.
- Treat CSX as a peer benchmark, not an automatic short: compare organic volume, pricing, and operating-ratio trends before initiating a UNP-versus-CSX pair.
- Monitor UNP’s next quarterly disclosures for carloads, coal volumes, pricing versus inflation, and operating-ratio progress. Reassess the thesis if productivity gains fail to translate into margin improvement or guidance is reduced.
- Do not buy JB Hunt solely on its buyback and dividend actions. Watch intermodal volumes and share trends for evidence that rail service gains are taking freight from truck, rather than assuming substitution from UNP’s service metrics.
More News
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Alibaba Backs Chinese Robovan Maker in $400 Million Fundraising
- Walmart’s Flipkart is quietly building a food delivery challenger in India
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More