
HiRO and Differentia Biotech Forge Strategic Alliance to Redefine Clinical Trial Design Through AI-Powered Simulation
Source: PR Newswire
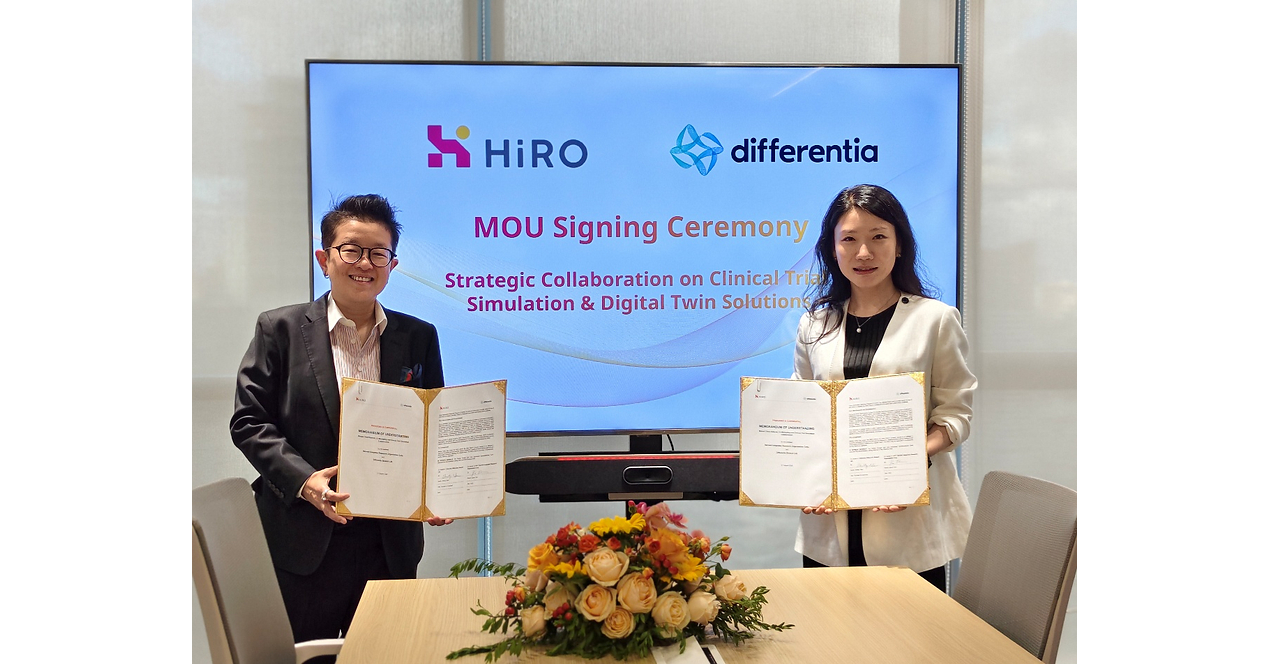
HiRO and Differentia Biotech announced an MOU to develop AI-powered clinical trial simulation/digital twin capabilities, aiming to support “simulate first” drug development as trial costs exceed $2.6B per drug and timelines compress. The partnership targets smarter trial design, improved patient selection, and potentially smaller subject counts through simulation-informed decisions. While it does not announce financial figures, the collaboration aligns with regulators’ model-informed drug development direction and could modestly improve perceived efficiency/value for biotech sponsors.
Analysis
This reads more like a capability roadmap than a monetized event. The immediate market impact is likely negligible because an MOU does not yet create backlog, recurring software revenue, or measurable margin leverage; the only thing tradable near-term is narrative optionality. The real economic value, if it exists, is in lowering sponsor development spend and shrinking cycle times, which shifts bargaining power toward CROs that can bundle analytics with execution rather than pure labor-arbitrage shops.
Second-order winners are likely model-informed development vendors and data-rich CROs that can prove protocol optimization: Certara (CERT) is the cleanest public proxy, while large CROs such as IQVIA (IQV) are more mixed because shorter, smaller trials can pressure top-line per study even if they improve win rates and utilization. The losers are point-solution vendors tied to patient recruitment, site activation, central labs, and imaging if sponsors truly reduce sample sizes; those businesses are more exposed than headline CROs. In biopharma, the benefit accrues first to cash-constrained small/mid-cap biotech via runway extension, which can delay dilutive financings over a 6-18 month horizon.
The key risk is regulatory and execution credibility: model-informed development only becomes durable if it repeatedly changes protocol design in real programs, not just in marketing decks. Near-term catalysts are sponsor signings, case studies, or FDA-facing validation over the next 1-3 months; the thesis is falsified if no commercial conversion appears by the next two earnings cycles or if a marquee simulated protocol underperforms in clinic. Consensus is probably overestimating the speed of adoption and underestimating how much CRO incumbents can absorb these tools through partnerships or acquisitions, limiting long-run disruption.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in IREHF on the MOU alone; treat as a watch item and require a disclosed sponsor contract or case study before underwriting value creation.
- Long CERT / short IQV as a 3-6 month relative-value expression if model-informed development adoption accelerates; CERT has cleaner upside to simulation monetization, while IQV is less likely to show material earnings lift from this theme.
- If looking for a lower-risk way to play the theme, buy a small basket of biotech capital-efficiency beneficiaries (small/mid-cap sponsors with 12-18 month cash burn risk) on pullbacks; the payoff is delayed financing relief, not immediate revenue growth.
- Set an alert for FDA/regulatory validation or a named commercial win from HiRO/Differentia; absent that, the probability-weighted value of the partnership remains too low for a directional position.
- Short the most exposed trial-enablement subcontractors only if follow-through data shows sample-size reduction or enrollment-cycle compression; until then, the disruption thesis is too early for an outright short.
More News
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
- TikTok CEO sees major scientific breakthroughs from AI within three years
- IIF CEO on Rising Global Debt