
Performance Brokerage Services Advises on the Sale of White Horse RV Center in Williamstown and Galloway, New Jersey from Ed Hutchinson, Jr. to Meyer's RV Superstores
Source: PR Newswire
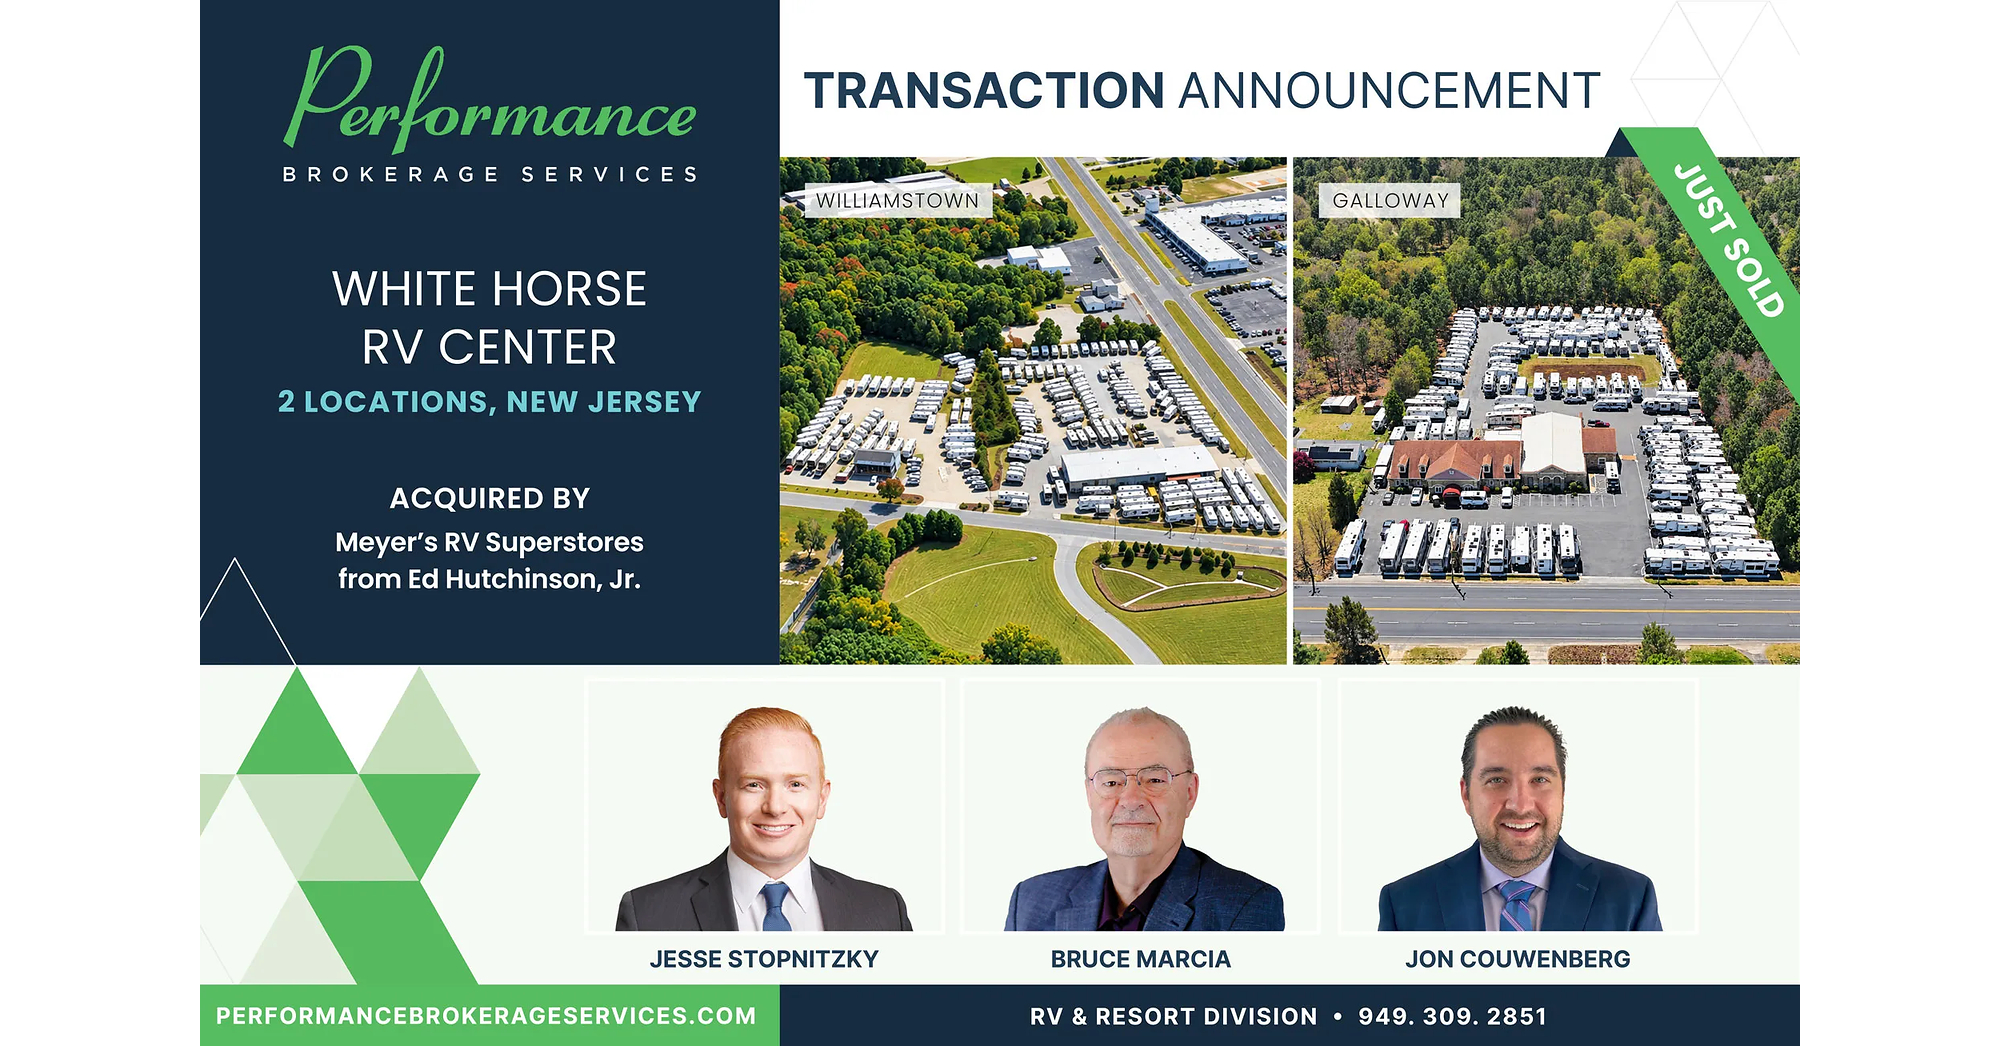
Meyer's RV Superstores acquired White Horse RV Center's two New Jersey dealerships in Williamstown and Galloway; the purchase price was not disclosed. The locations will be renamed Meyer's RV and remain in place, bringing Meyer's New Jersey dealership count to three and its overall network to 19 RV and marine dealerships across six states.
Analysis
This is evidence of continued buyer appetite for established regional dealership assets, not evidence of an RV-demand inflection: a family succession sale can occur even in a flat market. The more relevant second-order effect is local scale. Adding two established sites may improve Meyer's purchasing leverage, marketing reach, and service coverage, while raising the bar for independent dealers competing for inventory, technicians, and customer acquisition. Any advantage remains conditional on the undisclosed purchase price, operating performance, and integration costs; the release supplies none of these.
For RV manufacturers such as Jayco and Grand Design, a larger dealer group can offer broader distribution but also concentrate channel power and potentially strengthen demands for allocation, incentives, or support. That trade-off matters more if consolidation spreads beyond this isolated transaction. It is not possible to infer manufacturer revenue or margins from this deal.
Near term, the transaction has negligible standalone read-through for public equities. Over 1–3 months, watch for additional regional acquisitions and dealer commentary on inventory turns, promotions, and floorplan costs. Over 6–18 months, sustained consolidation could pressure small dealers and shift channel economics, but this release alone does not establish that trend. The contrarian point: the optimistic framing may invite an overread as a demand signal; seller succession is a plausible alternative explanation. Thesis weakens if Meyer does not integrate the sites or if subsequent disclosures show persistent inventory build, discounting, or weaker RV retail demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade on this transaction alone: purchase price, target earnings, and financing terms are undisclosed, and no public-company exposure is identified in the supplied data.
- Treat as a low-priority consolidation watch item; monitor Meyer's further acquisitions and independent-dealer exits before positioning around a structural scale advantage.
- For RV-sector exposure, wait for corroboration from dealer inventory turns, discounting, and consumer financing conditions; worsening inventory or promotions would falsify a bullish channel-consolidation read-through.
More News
- GIC Private Ltd, Medline 10% owner, sells over $721m in shares
- A 32% beat, a +6% jump: the IT solutions name our models picked in July
- Paramount's hard-fought takeover of Warner Bros. Discovery closes Tuesday. Here's how we got here
- CNN, CBS News now under one roof as Paramount-Warner Bros merger closes
- Nvidia Is on the Verge of a $6 Trillion Market Value
- Paramount Closes Warner Merger in Historic Hollywood Deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Selecting an AI Research Platform for Institutional Investors
- Weekly Update: New Reporting Features and More Sources for Document Search