
Greggs to Close Four Plants as Baker Warns of Inflation Pressure
Source: Bloomberg
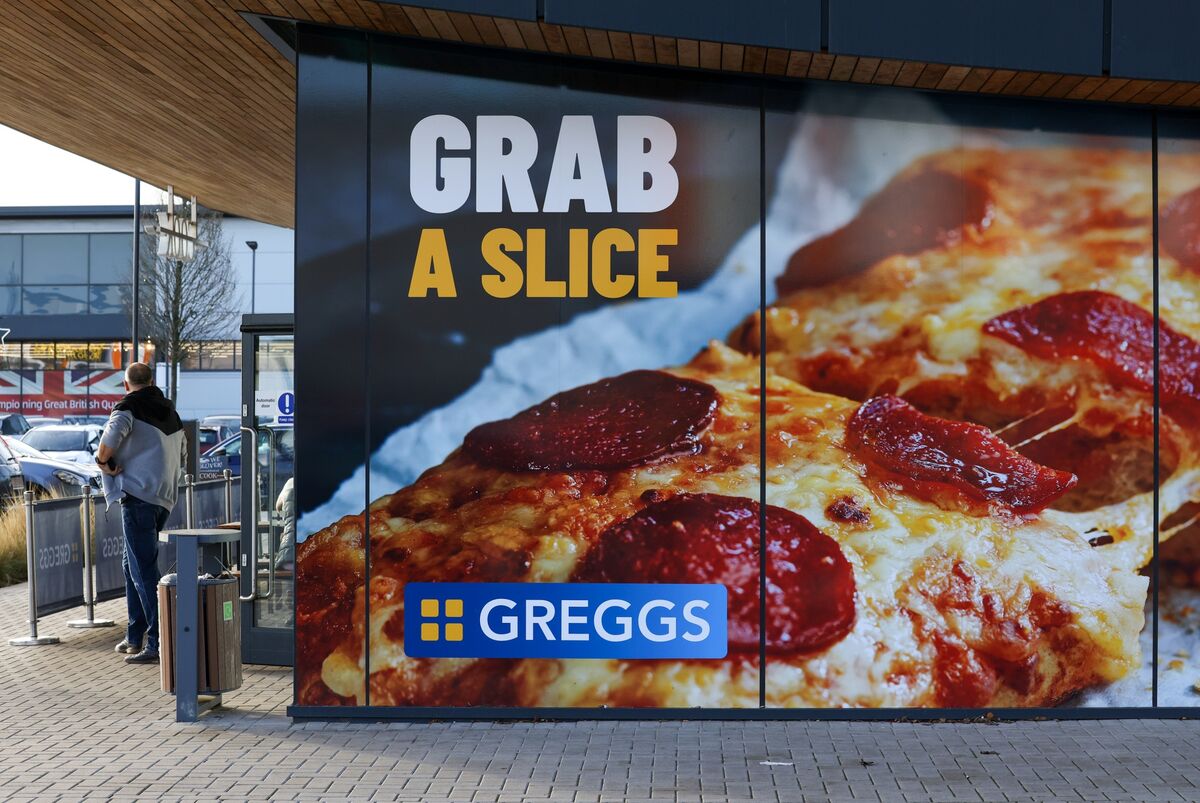
Greggs plans to close four manufacturing sites, a restructuring that could eliminate 740 jobs, as the UK bakery chain faces rising inflation pressure. The company said the closures would improve cost efficiency and shift production to better support its expanding store network, creating near-term workforce and execution risks despite expected operational savings.
Analysis
The key equity question is whether the network consolidation is capacity rationalization ahead of weaker volumes or a genuine fixed-cost reset that protects unit economics during store expansion. For GRG, the near-term P&L is likely burdened by consultation, redundancy, asset-impairment and production-transfer costs before savings are visible; the market will discount the action if management cannot quantify annualized savings, payback period and disruption risk. A manufacturing transition also raises the probability of temporary availability gaps or waste inflation, which would be especially damaging if value-conscious consumers trade down within food-to-go rather than simply absorb price increases.
Inflation exposure is asymmetric across UK quick-service retail. Larger scaled operators such as JET, MCD and (privately held) Pret have more purchasing leverage and can spread distribution costs over broader networks, while smaller bakery/café chains and independent high-street operators face greater labor, rent and ingredient-cost pressure. GRG can ultimately emerge with a stronger regional production footprint, but only if the consolidation releases enough capacity to support incremental shops without incremental central overhead; that is a 6-18 month thesis, not a next-quarter earnings benefit.
Consensus may treat cost cutting as automatically margin-accretive. The contrarian risk is that closures reveal that prior investment assumptions no longer match local demand or that inflation is forcing a more persistent value-for-money tradeoff, limiting pricing power. The decisive 1-3 month catalysts are quantified restructuring charges, like-for-like sales cadence, gross-margin commentary and confirmation that store-opening targets are unchanged; deterioration in any two would shift the read-through from efficiency to demand defense.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly negative
Sentiment Score
-0.55
Ticker Sentiment
Key Decisions for Investors
- Remain tactically underweight GRG through the next results/update unless management discloses a credible annualized savings figure and a sub-24-month cash payback. The immediate downside setup is guidance de-risking from one-off costs plus operational disruption; reassess after evidence that availability and like-for-like sales remain intact.
- Use GRG as a relative short versus MCD or JET over the next 1-3 months if UK food, labor and distribution inflation continues to rise. The pair expresses weaker operating leverage and execution risk at GRG while reducing broad consumer-discretionary beta; stop out if GRG reaffirms margin guidance and provides savings sufficient to offset restructuring within two years.
- Set an earnings alert on GRG for three falsifiers: unchanged store rollout, stable/improving like-for-like sales, and gross-margin resilience despite transition costs. If all are confirmed, cover any tactical short because the market could re-rate the program as a structural margin and capacity upgrade over 6-18 months.
- Avoid extrapolating the announcement into a broad UK consumer short absent corroborating traffic data. The more investable second-order signal is pressure on subscale food-to-go operators, but no liquid, clean listed UK pure-play comparator is identified from the available data.
More News
- Greggs shares jump 9% as Panmure Liberum highlights stronger quarterly trading
- Greggs lifts 2026 outlook as it plans four factory closures and 740 job cuts
- UK Reports Stronger Than Expected Economic Growth In Break For Burnham
- ‘Groundhog Day’: Iran is unlikely to let the war end until after the midterms—and may even escalate soon
- Drastic budget cutbacks essential to fund Europe's defense, Germany and allies warn
- Pressure on U.S. Treasurys eases after 30-year yield hits highest level since 2002
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Private Equity Due Diligence: A Buyer Workflow
- Weekly Update: In-App Tutorials, Futures Data, and Watchlist Enhancements