
XPENG Launches Its Next-Gen AI Flagship SUV G9L in China, with Global Launch Set for Oct 12 at the Paris Motor Show
Source: PR Newswire
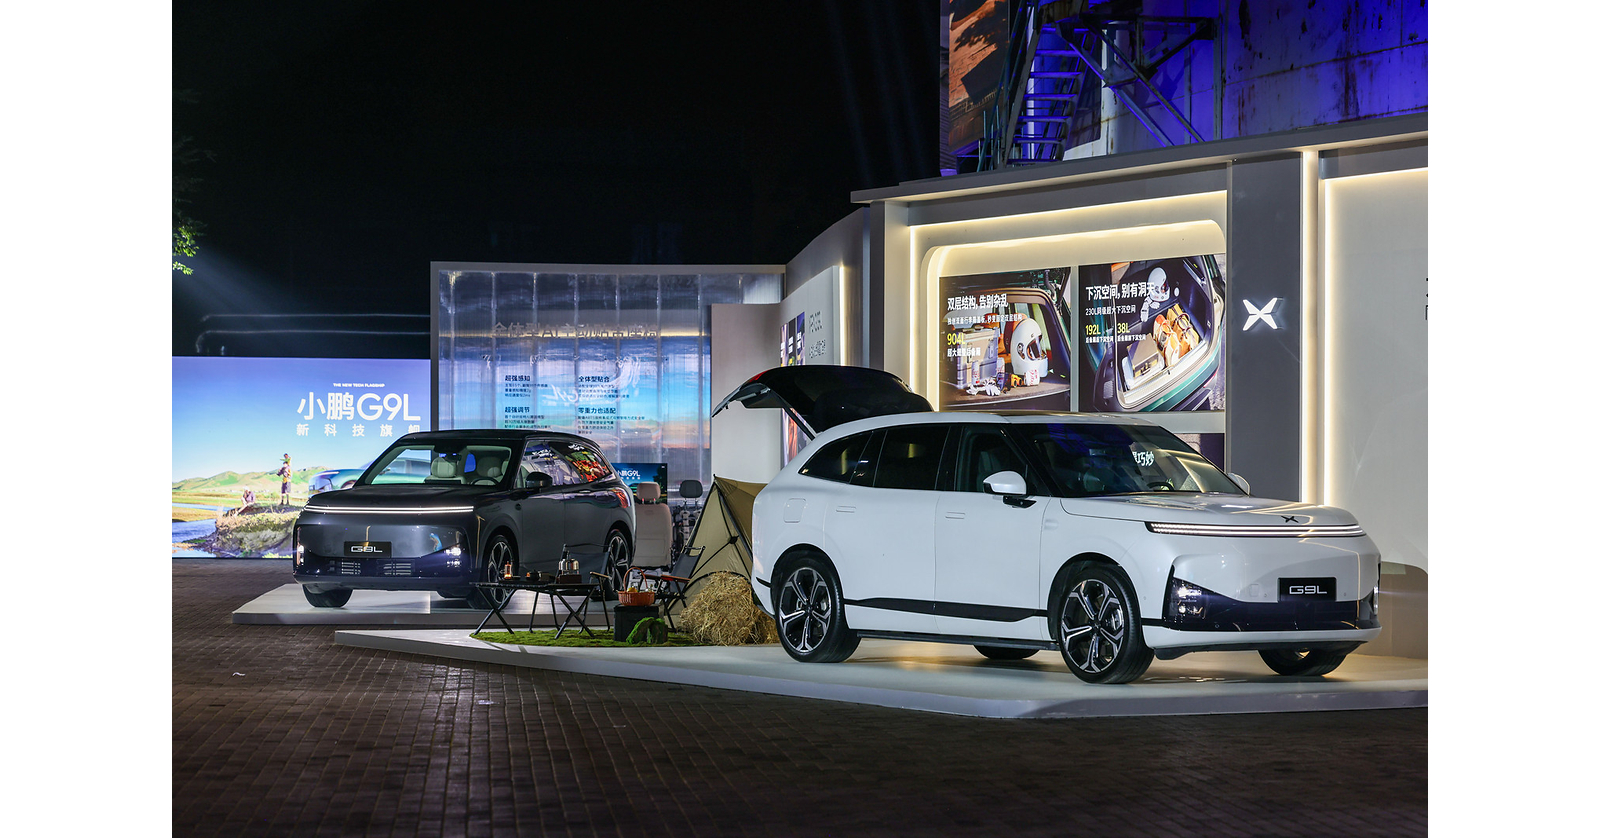
XPENG launched its G9L AI flagship SUV in China and plans to introduce the BEV and REEV model across 64 global markets, beginning with an October 12 global debut at the Paris Motor Show. The 5,120 mm SUV uses XPENG's VLA 2.0 AI model and Turing AI chip, while production will take place in Guangzhou and at Magna's Graz, Austria facility. G9L becomes XPENG's fourth locally assembled European model within one year, underscoring its accelerating international manufacturing and product-expansion strategy.
Analysis
XPEV's valuation upside depends less on launch-day demand and more on whether the model lifts overseas mix without recreating the margin dilution historically associated with dealer incentives, homologation expense, and fragmented service networks. A locally assembled premium SUV can improve delivery lead times and reduce tariff exposure, but only if European content rules qualify it for favorable treatment; assembly alone does not eliminate trade-policy risk. The critical 1-3 month read-through is order conversion and achievable transaction price versus the G9/P7+ portfolio, not reservations or management's addressable-market framing.
MG gains a modest, lower-risk revenue opportunity through contract-manufacturing utilization and engineering services, but economics are likely immaterial versus its broader customer base unless XPEV commits meaningful annual volumes. Magna's more important benefit is strategic: it reinforces its position as a neutral European manufacturing bridge for Chinese OEMs facing tariff and capacity barriers, potentially attracting peers such as Zeekr, Leapmotor, and BYD. The second-order negative is for European premium OEMs—BMW, Mercedes-Benz and Volvo—if XPEV demonstrates that premium software features can be localized while retaining Chinese cost advantages; however, established brands retain financing, residual-value and service-network advantages that remain decisive in this segment.
Consensus may overvalue the AI branding before there is evidence of regulated, monetizable driver-assistance functionality outside China. European safety approvals, data localization, liability standards and country-by-country feature restrictions can turn a software differentiation story into a feature-parity vehicle at launch. Over 6-18 months, the thesis is bullish only if overseas gross margin expands despite localized production and the REEV variant broadens demand without triggering brand or emissions-compliance friction in key European markets.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Maintain XPEV as a watch-to-buy into the October 12 event rather than chase the press-release move; initiate only if disclosed European pricing supports a premium to China-equivalent pricing and management reaffirms consolidated vehicle gross-margin expansion. A 10-15% upside is plausible on credible order/pricing evidence, while downside is comparable if guidance implies launch incentives or higher overseas operating expense.
- Use a 3-6 month pair trade only after first European delivery data: long XPEV / short LCID for a premium-EV technology and scale comparison, with a hard stop if XPEV's overseas ASP falls below its existing European portfolio or LCID secures a material funding/production catalyst.
- Accumulate MG on weakness for a 6-18 month option on Chinese-OEM localization demand, but size modestly: require confirmation of incremental contracted volumes or capacity-utilization commentary before underwriting a material earnings impact. The thesis is falsified if European trade rules restrict the economic benefit of Austrian assembly or if XPEV volume remains below scalable production thresholds.
- Set alerts for EU tariff/rules-of-origin decisions and XPEV's first post-launch gross-margin commentary; either evidence of non-qualifying local content, elevated warranty provisions, or increased sales incentives would invalidate the near-term XPEV margin-expansion narrative.
More News
- Xpeng stock rises on plans to license tech to foreign automakers
- Italy to deploy warships to protect shipping through Bab al-Mandeb
- Oil prices fall for 3rd day as supply concerns ease, diplomacy in focus
- Australia’s central bank chief warns inflation risks materialising
- Saudi Pivots Oil Routes After Pipeline Attack
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework