
CARNIVAL TROPICALE 号开放预订 | CARNIVAL TROPICALE 号正式开放预订,2028 年将从加尔维斯顿启航
Source: PR Newswire
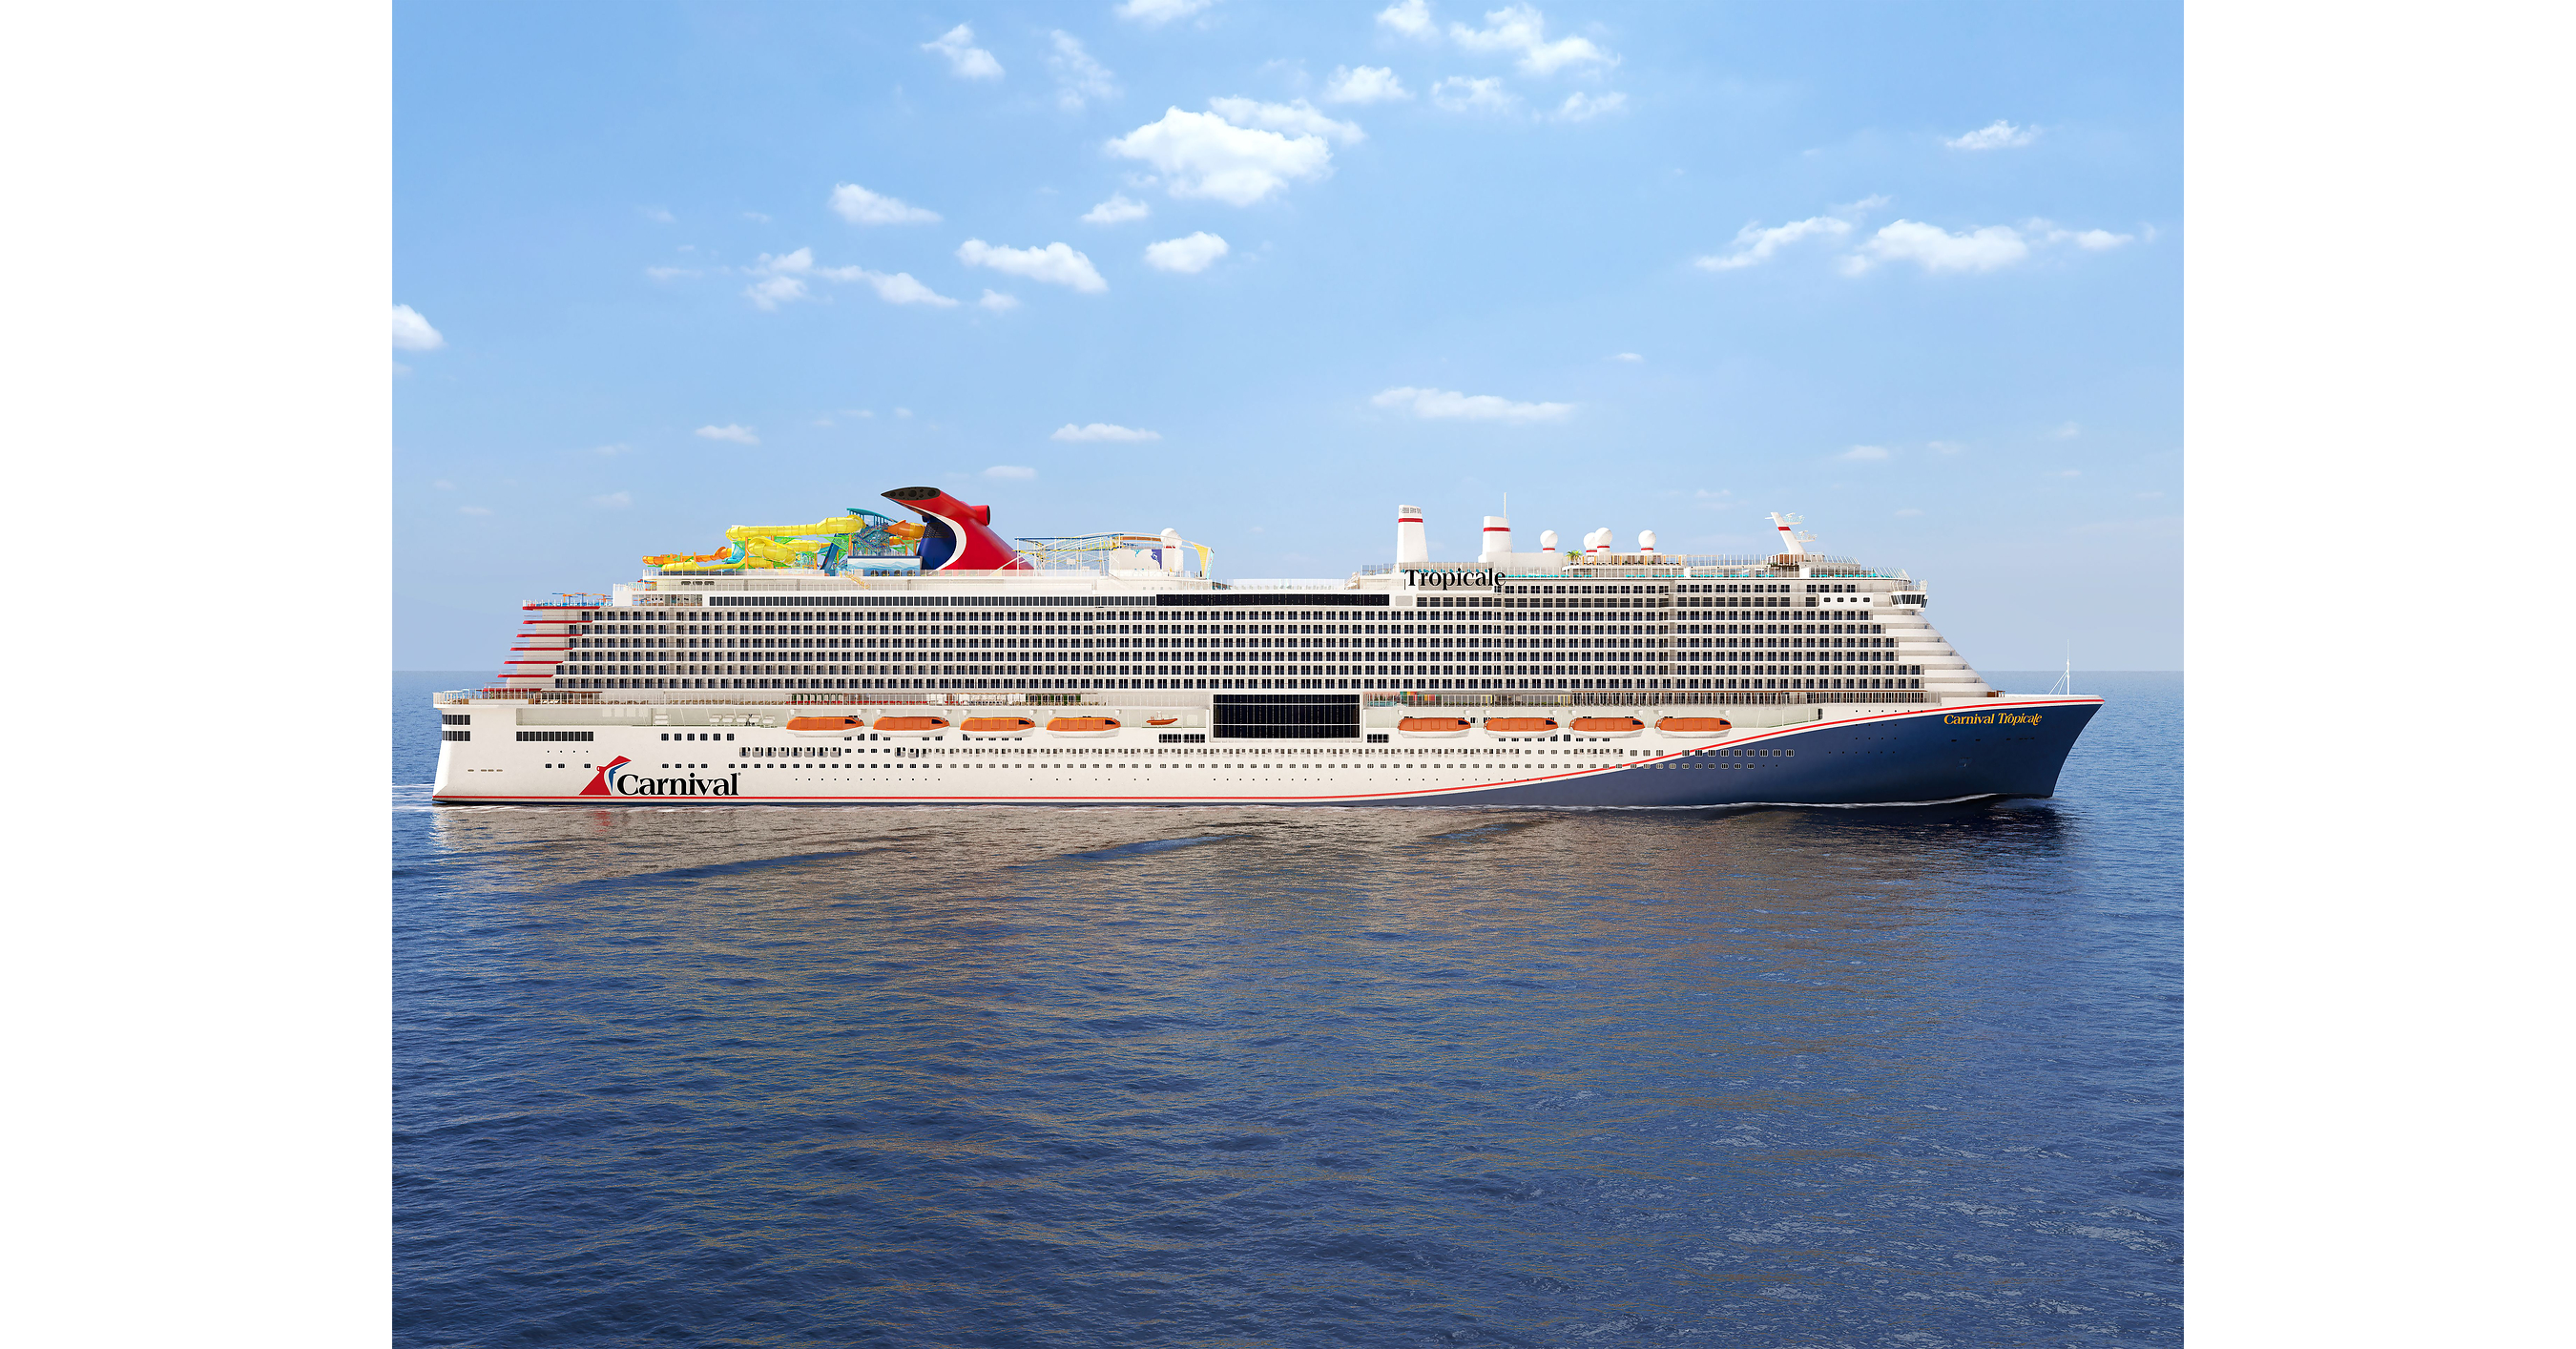
Carnival Cruise Line opened bookings for Carnival Tropicale, its fifth and final Excel-class ship, scheduled to begin sailing from Galveston on April 15, 2028. The vessel will operate 4-, 5-, 6- and 8-day Caribbean itineraries and add new family entertainment, waterpark and dining concepts. The launch supports Carnival's fleet-expansion plan, which calls for five additional ships by 2033, including Excel-class deliveries in 2027 and 2028.
Analysis
The booking opening is not a near-term earnings catalyst; it is a 2028 capacity commitment whose value depends on whether Carnival can preserve pricing while absorbing another high-fixed-cost vessel. The more investable read is demand visibility: early bookings can improve the long-dated revenue curve and support yield assumptions, but deposits are cancellable and do not establish realized net yield. Investors should look for management disclosure on booked position, pricing versus prior Excel-class launches, and the incremental capex/financing profile rather than extrapolate from a marketing announcement.
Galveston concentration creates a potentially attractive regional fly-to-drive advantage versus Florida-heavy itineraries, particularly if domestic leisure demand softens and consumers trade down from international vacations. It also raises exposure to Gulf disruption, Texas labor and port constraints, and Caribbean destination capacity; a hurricane-driven itinerary disruption would hit both onboard spend and customer satisfaction at the same time. The proprietary-destination strategy can lift onboard and shore-excursion capture over 6-18 months, but only if the new destinations avoid cannibalizing occupancy and pricing on existing Caribbean sailings.
Competitive impact is modest near term. RCL and NCLH face a renewed family-product and Texas-market competitive challenge, but their valuation implications hinge on whether CCL uses the vessel to take share at comparable yields rather than filling berths through discounting. Consensus may over-credit the headline capacity growth: one additional ship is earnings-accretive only after accounting for depreciation, interest expense, pre-opening costs, and the yield needed to offset incremental berth supply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade solely on this release; treat it as a booking-data watch item ahead of CCL quarterly results. Upgrade only if management shows 2028 booked pricing ahead of comparable launch curves without raising promotional intensity.
- Maintain a 6-12 month long CCL / short NCLH pair only on confirmation that CCL's Caribbean yields and onboard revenue outperform while net leverage continues declining; CCL has the stronger proprietary-destination monetization path, while NCLH is more vulnerable to industry discounting. Exit if CCL net yields decelerate for two consecutive reporting periods or leverage reduction stalls.
- For existing CCL longs, use any pre-earnings strength to reduce exposure if valuation rerates without an upward revision to 2027-28 capacity, net-yield, or free-cash-flow guidance. The primary falsifier is evidence that incremental Galveston capacity is being filled at lower ticket yields rather than producing mix-driven margin expansion.
- Monitor hurricane-season disruption, Galveston port operations, and Caribbean destination capacity over the next 1-3 months; these are nearer-term risks to CCL booking momentum than a ship scheduled for delivery in 2028.
More News
- Royal Caribbean Stock Jumps After Better-Than-Expected Earnings, Raised Outlook
- OneSpaWorld earnings up next as cruise demand hits records
- SK Hynix third-quarter profit sharply beats estimates on AI memory boost
- SK Hynix Posts Record Profit Amid AI Rush
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Anthropic Gives Traders a Pure-Play Bet on Frontier AI