
Ukrainian Parliament Awards U.S. Bipartisan Delegation in Kyiv as Russian Attacks Intensify Against Civilian Infrastructure and the U.S. House Weighs the Lindsey O. Graham Sanctioning Russia and Iran Act
Source: PR Newswire
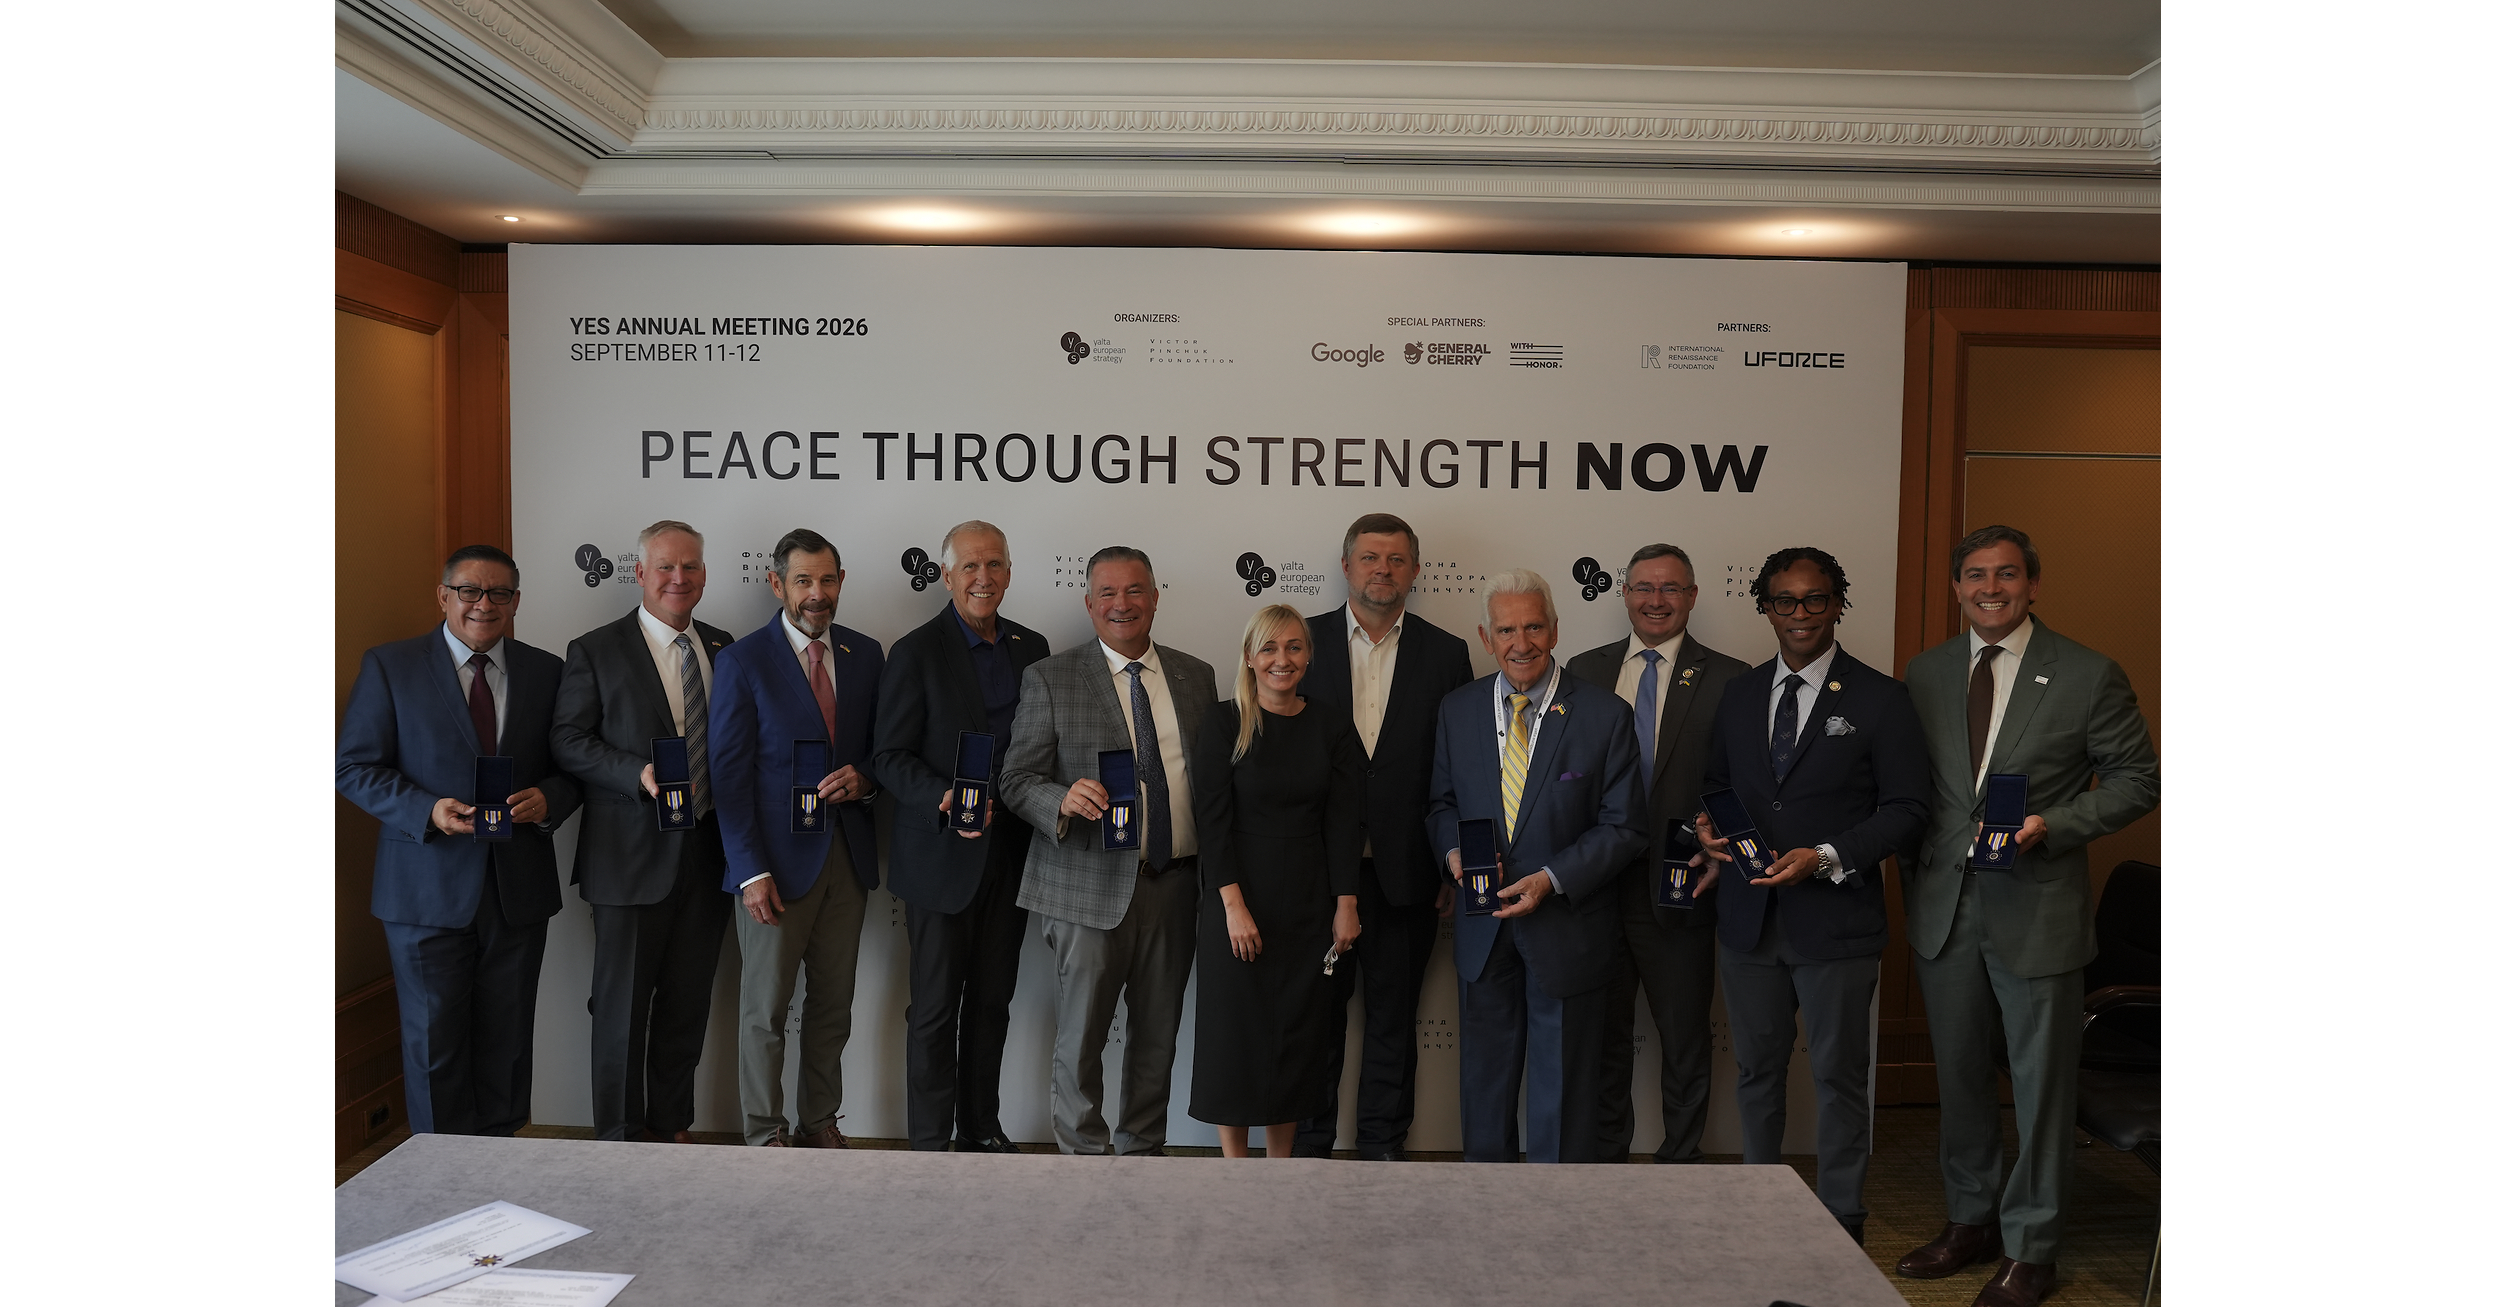
The Senate passed the Lindsey O. Graham Sanctioning Russia and Iran Act by an 86-11 bipartisan vote on Aug. 7, with the House urged to take up the measure as Russian attacks on Ukrainian civilian infrastructure intensify. Congress also appropriated $400 million in FY2026 for Ukraine-related European capacity building, but the Pentagon has not yet contracted the funds for U.S.-manufactured weapons, equipment and services. Passage and implementation could increase pressure on Russian oil revenue and support U.S. defense suppliers, though the article underscores elevated escalation risks ahead of Ukraine's winter.
Analysis
The investable signal is not the congressional delegation; it is whether appropriated Ukraine procurement converts into signed contracts before winter. Even full obligation would be immaterial to LMT, RTX, NOC and GD at the consolidated level, but could marginally improve visibility for air-defense, counter-UAS, munitions and tactical-communications program lines where production slots—not demand—remain the binding constraint. The more meaningful second-order beneficiary is the U.S. defense supply chain’s utilization rate: incremental foreign-funded replenishment supports multiyear capacity investment and pricing discipline, particularly for solid rocket motors and missile components.
A House vote is a near-term headline catalyst, but the market should separate authorization from enforcement. Any Russia/Iran sanctions package has commodity relevance only if it includes credible secondary-sanctions mechanisms, defined penalties, and visible Treasury implementation; absent those details, crude and LNG markets are likely to treat passage as symbolic. A tighter enforcement regime would raise the embedded disruption premium in seaborne crude, benefiting XLE and LNG exporters such as Cheniere (LNG), while increasing European gas-price convexity into winter.
Consensus may overestimate the direct EPS impact on defense primes and underestimate execution risk. Pentagon contracting lead times, export approvals, production bottlenecks, and the administration’s willingness to enforce sanctions matter more than bipartisan rhetoric; a delay in obligation beyond the next 30-60 days would push deliveries into a less strategically relevant window and remove the near-term order catalyst. The thesis is falsified if contract awards fail to appear in DoD announcements by year-end, or if legislation materially weakens secondary-enforcement provisions during House consideration.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.32
Key Decisions for Investors
- No outright defense-prime trade on this release alone. Create a 30-day contract-award watchlist for RTX, LMT, NOC and GD; buy the contractor actually named in any air-defense, interceptors, counter-UAS or munitions award rather than pre-positioning across the group.
- If the House passes a final bill with enforceable secondary sanctions and Treasury issues implementing guidance within 2-4 weeks, initiate a tactical long XLE versus short XLI for a 1-3 month energy-input spread trade. Exit if Brent fails to hold above its pre-legislation level after implementation or if carve-outs materially preserve Russian export flows.
- Maintain LNG as the preferred structural energy-security expression over broad oil beta on a 6-18 month horizon; add only if European gas spreads widen materially or contracted U.S. export volumes accelerate. Key downside risk is a negotiated ceasefire or a warm European winter compressing LNG optionality.
- For defense exposure, favor a relative-value basket long RTX/NOC versus short ITA only after identifiable missile-defense or munitions awards, targeting a 3-6 month catalyst window. The $400 million pool alone is too small to justify a sector-wide multiple rerating; limit risk if order announcements do not exceed currently implied backlog expectations.
More News
- Saudi coalition says Houthi drone destroyed near Mecca
- BOJ expected to hike rates by 25 basis points to fresh three-decade high: CNBC survey
- Iran war increasing inflation, straining US munitions: congressional report
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- US Senate crypto bill collapses in blow to industry