
Worthington Steel: Kloeckner Turns Processing Density Into An Earnings Engine
Source: seekingalpha.com
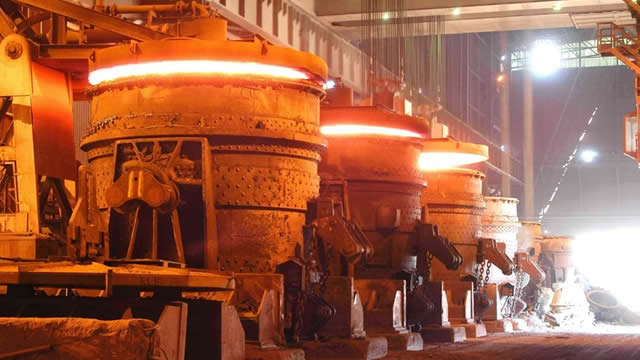
Worthington Steel is repositioning as a value-added metals processor, using the Kloeckner acquisition to increase processing density and procurement efficiencies even with lower total tonnage. Management highlights ~$150M of synergy potential by FY2028, implying improved value capture and higher-quality earnings, though investors will watch integration risk, potential leverage impacts, and electrical steel demand headwinds.
Analysis
This is more a business-model re-rate than a simple steel call. If processing density rises and procurement gets centralized, WS can improve EBITDA per unit of throughput even with flatter tonnage, which is exactly the kind of mix shift that can justify a higher multiple in a cyclical name. The competitive spillover is toward smaller service centers with weaker buying power; the right comps are now scaled distributors like RS and RYI, not commodity mills.
Near term, the market will care less about announced synergies and more about whether working capital, integration costs, and leverage stay controlled over the next 2-3 quarters. Metals roll-ups often look great on paper but take several reporting periods before purchasing savings and network rationalization appear in gross margin, so any slip will be punished if industrial demand softens or electrical steel remains a drag. If net leverage does not trend down as free cash flow converts, the equity will trade like a leveraged cyclical, not a quality compounder.
The contrarian point is that lower tonnage is not automatically negative if the mix shifts toward higher value-added processing and more durable earnings. The market may be underestimating the potential for multiple expansion over 6-18 months if management proves the platform can deliver consistent margin per ton rather than just acquisition-adjusted revenue growth. Falsifier: two consecutive quarters without clear spread/margin improvement or any sign the integration is consuming cash instead of creating it.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Initiate a half-size long WS position on weakness, targeting a 3-6 month horizon; add only if the next earnings print shows gross margin per ton inflection and lower working-capital drag.
- Pair trade: long WS / short XME for 3-6 months to isolate the mix-and-synergy story from broad steel-beta volatility; thesis fails if WS underperforms XME after the first post-close integration update.
- Do not buy the multiple up front on synergy headlines alone; require evidence of realized cost savings and declining net leverage before sizing beyond a starter position.
- If WS net leverage stays elevated or electrical steel weakness deepens into the next two quarters, exit the long and treat the deal as value-destructive rather than accretive.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- Wall Street Anxiety Spreads as AI Rout Meets $110 Oil Shock
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Tesla is taking $250,000 deposits for a Roadster with SpaceX thrusters. The FAA says it isn’t an aircraft
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Independent Research Firms: A Publishing System
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More