
Opus Expands Capital Capabilities with Hiring of Mark Kunkel as Senior Vice President of Capital Formation and Investment Strategy
Source: PR Newswire
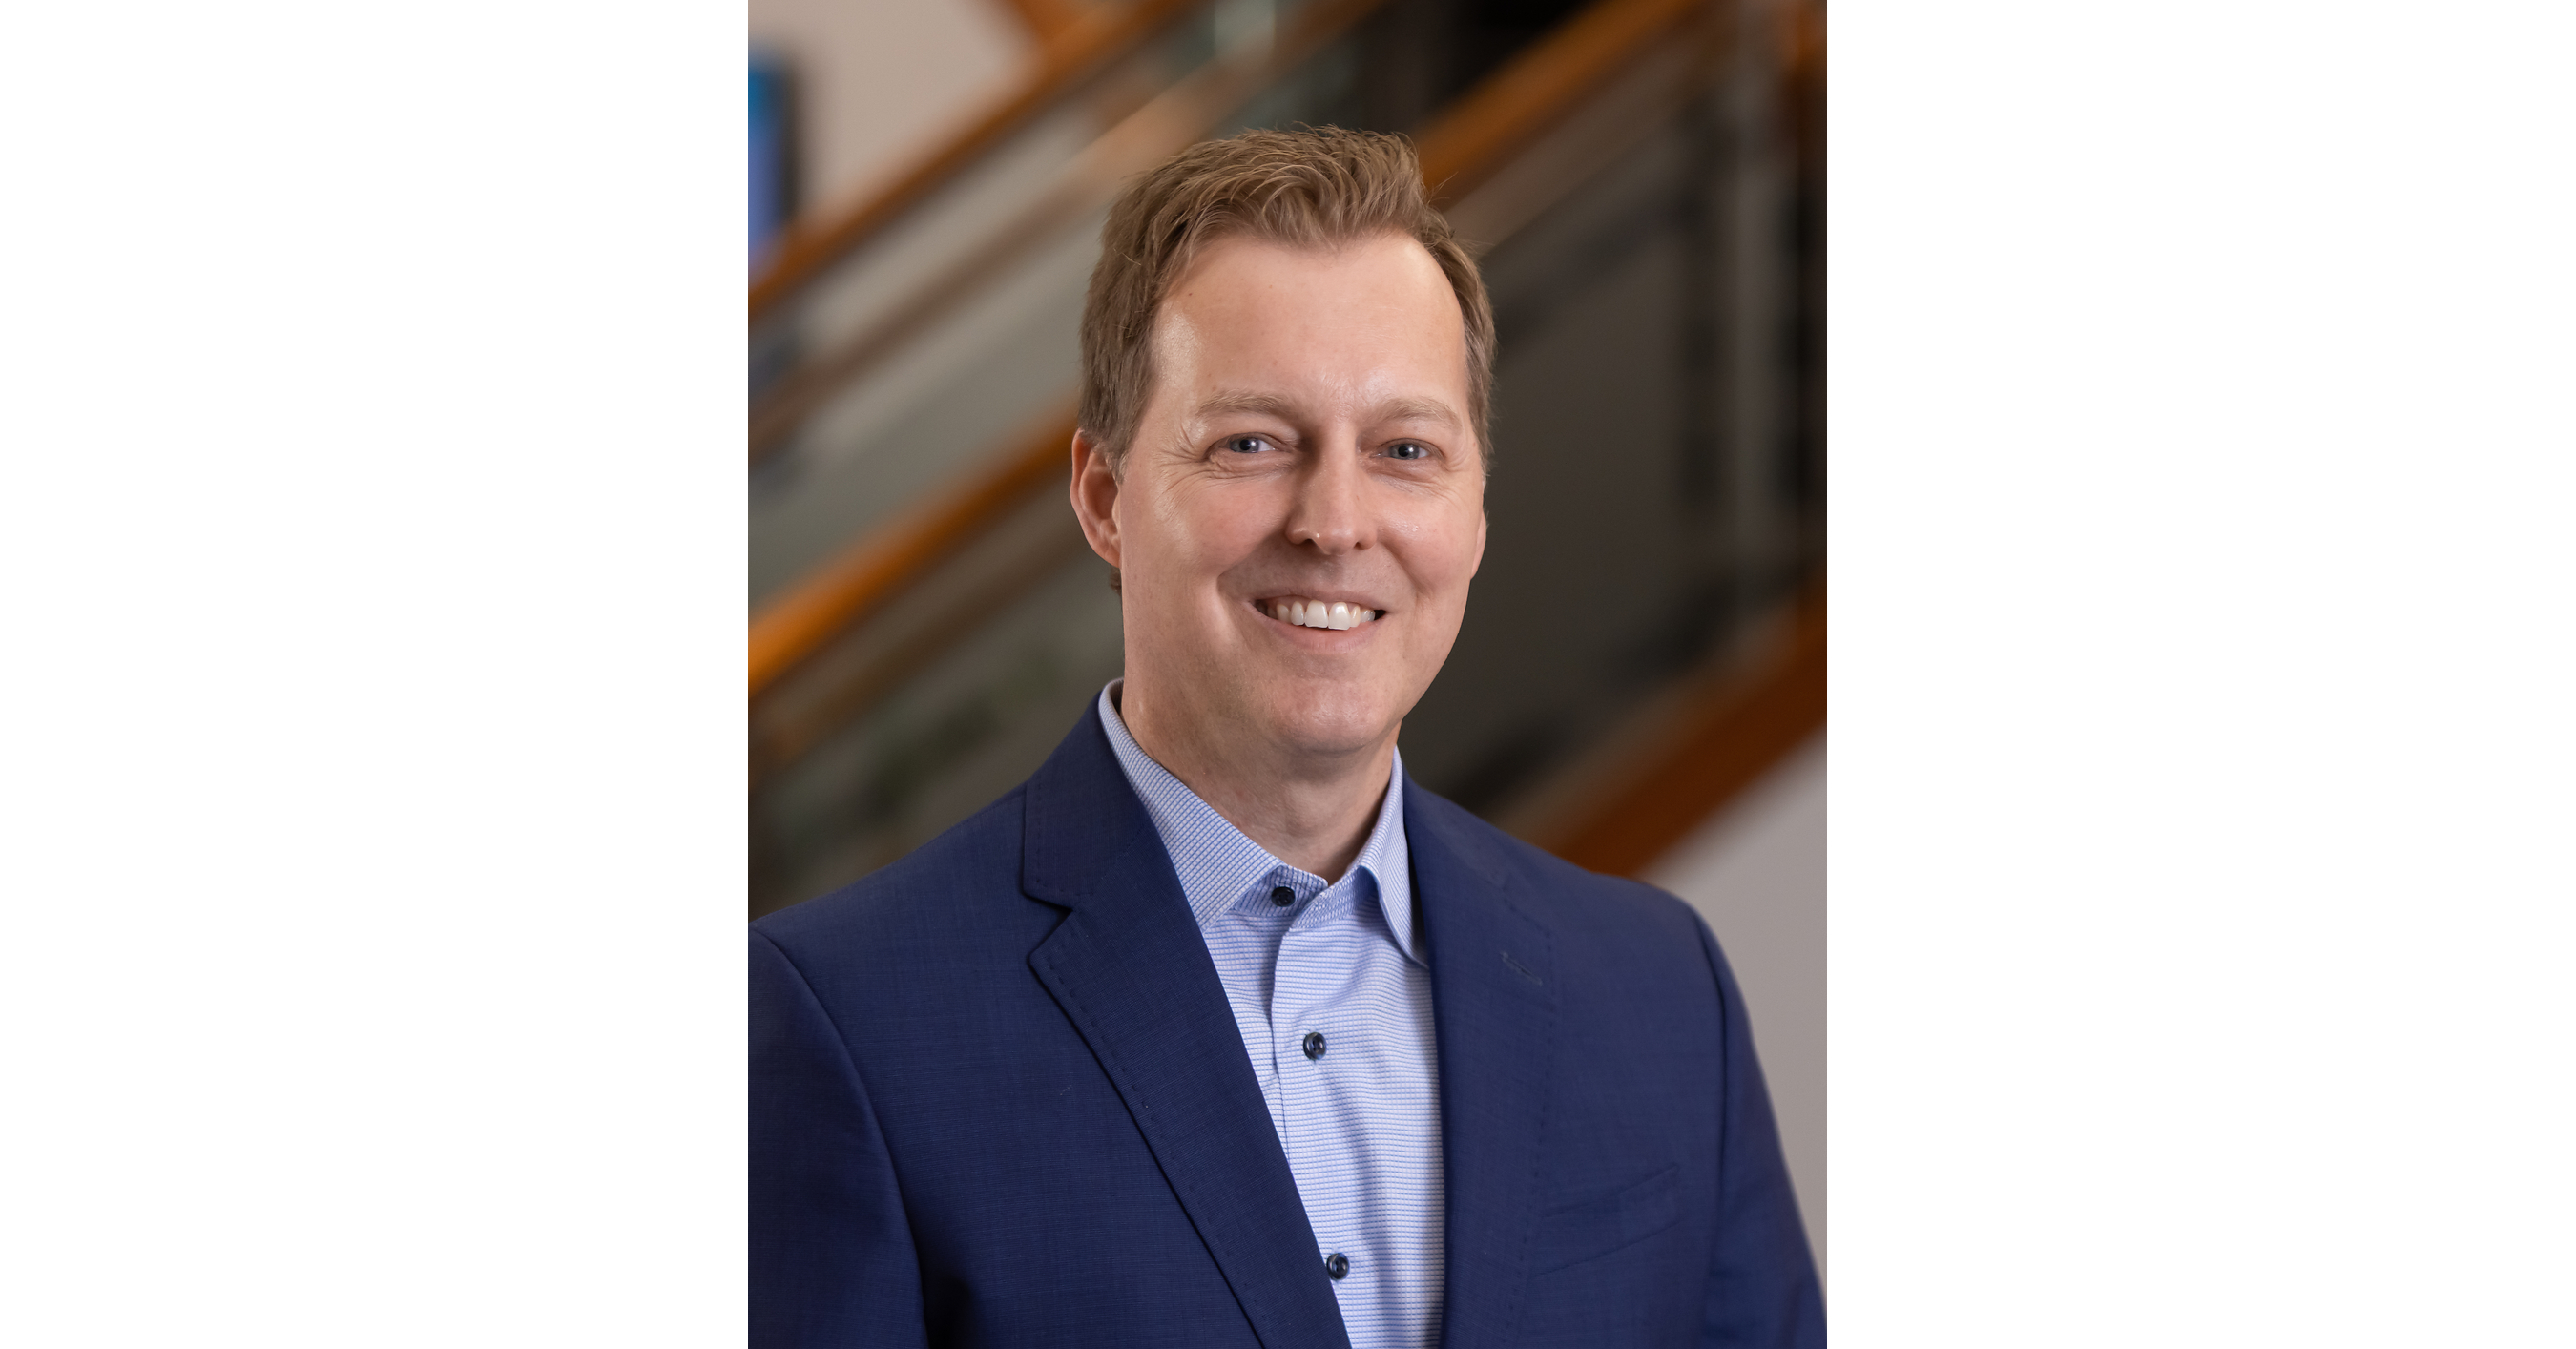
Opus appointed Mark Kunkel as senior vice president of capital formation and investment strategy to expand and diversify its commercial-real-estate funding base beyond joint-venture equity. Kunkel brings 25 years of investment-management experience, including more than $3.0B of acquisitions, financings and dispositions and portfolio oversight of over 12 million square feet. The hire supports Opus' planned development of institutional-grade investment vehicles and fund strategies, though the announcement disclosed no transaction size, fundraising target or financial impact.
Analysis
This is not a public-markets catalyst: Opus is private and the announcement provides no committed capital, target fund size, asset mix, fee economics, or deployment timetable. The relevant signal is that a developer is shifting from episodic JV funding toward discretionary capital, which can improve pipeline certainty and fee-like income but also introduces fund-raising, deployment, and valuation risk during a still-selective institutional CRE allocation environment.
Second-order implications favor scaled, balance-sheet-light CRE capital managers over merchant developers if institutional allocators resume commitments. BX, KKR, APO and ARES have established fundraising distribution and can absorb demand for real-estate credit or opportunistic equity more readily; listed developers and construction firms do not gain directly unless new vehicles translate into incremental starts. For construction-sensitive names, the useful read-through is demand for industrial and multifamily development financing, not a leadership hire itself.
Over the next 1-3 months, watch for evidence of an actual first close, anchor LP, or announced strategy; absent those, this is organizational positioning rather than investable demand. Over 6-18 months, the key differentiator will be whether capital is directed to development equity, where lease-up and exit-cap-rate risk remain material, or real-estate debt, where current yields provide more downside protection. A sharp widening in CRE credit spreads, further office-value declines, or a sustained rise in long-term rates would impair fund formation and make the expansion thesis moot.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No direct trade in response to this release; Opus is private and the financial terms needed to assess incremental capital formation are absent.
- Maintain a watchlist on BX, KKR, APO and ARES for broader evidence of institutional CRE fundraising recovery; favor ARES/BX if commitments skew toward private credit and industrial-residential financing rather than ground-up development.
- Use a first-close announcement, disclosed AUM target, anchor-investor commitment, and stated property-type allocation as required confirmation before treating Opus activity as a demand signal for listed construction or development exposures.
- For CRE exposure over the next 6-12 months, prefer debt-oriented platforms and avoid extrapolating this into a broad office-development recovery; thesis is falsified if 10-year Treasury yields rise materially or CRE loan-spread stress reaccelerates.
More News
- History shows financial calamities occur when rates rise rapidly like this: 'Something always breaks'
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- 30-year fixed mortgage rate jumps sharply Thursday to 7.45%
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- Here’s the Tesla Semi… again