
THE 50 BEST BARS ANNOUNCES THE EXTENDED 51-100 LIST FOR 2026
Source: PR Newswire
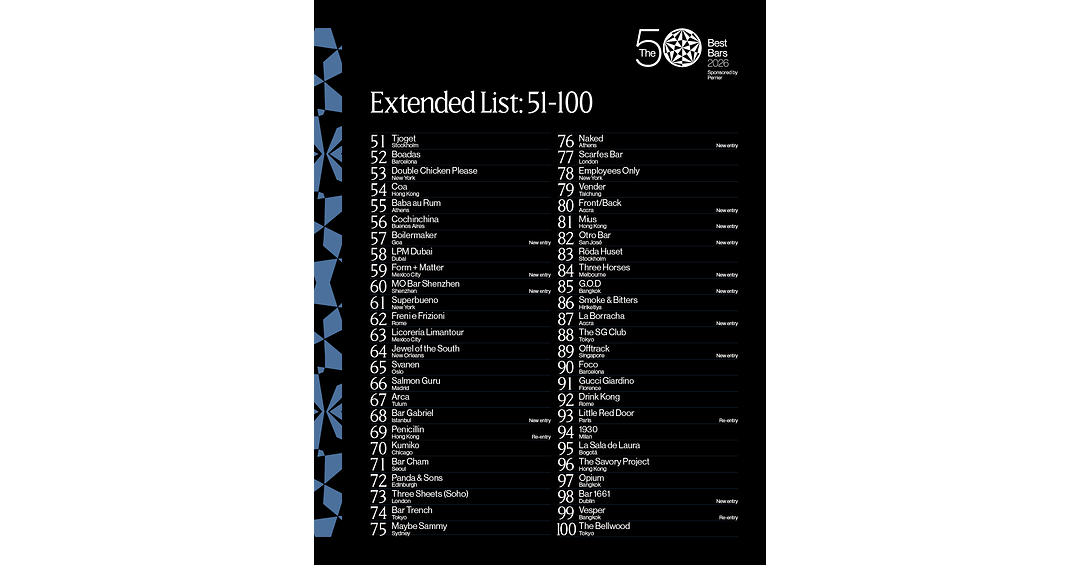
The 50 Best Bars released its 2026 extended 51-100 ranking, covering venues in 34 cities and adding 13 new entries, ahead of the main awards ceremony in Milan on 7 October. Europe leads with 18 ranked bars, Asia has 16, and the U.S. remains the most represented country for a fourth consecutive year with five venues. The announcement highlights global hospitality and cocktail-sector visibility but is unlikely to have material public-market implications.
Analysis
This is not a standalone public-equity catalyst: the ranking is promotional, has no disclosed booking, spend, or supplier-volume data, and is unlikely to alter near-term estimates for listed travel, beverage, or hospitality companies. The most investable read-through is a modest demand signal for premium experiential consumption in destination cities, but its economic impact is dispersed across independent venues rather than concentrated in listed operators.
Over the next 1-3 months, the October awards event could marginally support earned-media traffic and premium on-premise trial for global spirits brands, particularly Diageo (DEO), Pernod Ricard (RI.PA), Rémy Cointreau (RCO.PA), and Brown-Forman (BF.B). However, awards-driven visibility tends to favor high-end, cocktail-relevant SKUs with limited aggregate volume; it does not offset the more important variables for these equities: US depletion trends, China travel retail, FX, and promotional intensity. Treat any share-price reaction as noise unless subsequent distributor data show premium-spirit velocity acceleration.
The second-order beneficiary is luxury hotel F&B and urban travel ecosystems rather than bar operators themselves. Marriott (MAR), Hilton (HLT), Accor (AC.PA), and booking platforms could capture incremental high-spend traveler activity only if rankings translate into measurable city-level room-night and restaurant-reservation demand. That linkage is too weak for a position today; a broader premium-experience recovery would be better validated through RevPAR guidance and card-spend data over the next two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No directional trade on the ranking itself; classify as low-signal marketing/newsflow rather than an earnings catalyst.
- Maintain a watchlist on DEO, RI.PA, RCO.PA, and BF.B into the October ceremony; upgrade the premium on-premise thesis only if management or channel checks indicate improved cocktail-channel depletions, with the next earnings cycle as the confirmation window.
- For a broader experiential-travel view, monitor MAR, HLT, and AC.PA for upward RevPAR or international leisure guidance revisions over 1-2 quarters; absent that evidence, do not extrapolate localized venue publicity into hotel demand.
- Falsification trigger for any premium-spirits read-through: renewed US on-premise traffic weakness, increased discounting, or further China travel-retail guidance cuts would dominate any favorable awards-related brand exposure.
More News
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Here's what happens to the economy when Treasury yields soar like they are now
- Oil industry warns a diesel export ban will raise fuel prices as Trump weighs restrictions
- Mark Zuckerberg debuts $1,299 Meta VR Glasses and Muse Charm pendant amid AI agent push
- Meta's standoff with Amazon over Muse could be a sign of things to come
- How a Diesel Export Ban Could Impact US Fuel Prices
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- AI Software for Buy-Side Teams: Build the Research Stack