
Done Switzerland Expands Operations to Türkiye
Source: globenewswire.com
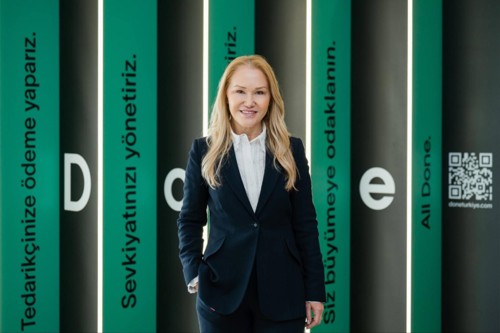
Done has begun operations in Türkiye, marking the Swiss-headquartered group's entry into its fourth market. The logistics, supply chain management and financing group appointed Filiz Ünal as CEO of Done Türkiye; no financial terms or market reaction were reported.
Analysis
The announcement is an option on future regional growth, not evidence yet of material earnings contribution. In Turkish logistics, customer density, reliable cross-border execution, and control of receivables matter more than market entry; Done’s financing offering could differentiate it if it wins repeat customers, but it also adds credit and liquidity risk. Local operators and established networks such as DHL Group, DSV, and Kuehne+Nagel could face incremental competition only if Done demonstrates service quality and scale; there is no basis to infer meaningful share loss today.
Near term, the signal is too small and unquantified for a sector trade. Over 1–3 months, verify customer wins, shipment volumes, asset intensity, and whether financing is funded on Done’s balance sheet or through partners. Over 6–18 months, the key question is whether Turkish operations become a repeatable platform or remain a costly standalone launch. Lira volatility, local rates, collections, and regulatory or customs friction could turn growth into working-capital drag. The contrarian point: market entry and a senior appointment can attract attention while obscuring the harder test—profitable density. No listed security is identified in the supplied mapping, so direct equity exposure is unclear.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No trade on the announcement alone; avoid treating geographic expansion as a near-term earnings catalyst without disclosed operating scale.
- Set a 1–3 month diligence alert for customer references, volume growth, service coverage, and financing structure; distinguish partner-funded receivables from balance-sheet credit exposure.
- Monitor Turkish lira and local funding conditions alongside evidence of collections and working-capital needs; worsening FX or funding pressure would weaken the expansion thesis even if volumes rise.
- Revisit only if Done reports repeatable customer traction and economics. Falsifiers include stalled volume/customer additions, rising receivables or credit losses, or evidence that expansion requires materially greater fixed-asset commitments than expected.
More News
- SK Hynix Posts Record Profit Amid AI Rush
- SK Hynix third-quarter profit sharply beats estimates on AI memory boost
- Anthropic's IPO could be 'speculative fiction' or a 'generational moment' — investors are split
- Iran’s calculations as US escalation looms: Trust, midterms, Hormuz
- Tech's relief rally extends as attention turns to tough decisions for the Fed
- Anthropic Gives Traders a Pure-Play Bet on Frontier AI