
NISHANE OPENS ITS FIRST NEW YORK BOUTIQUE IN THE HEART OF NOLITA
Source: PR Newswire
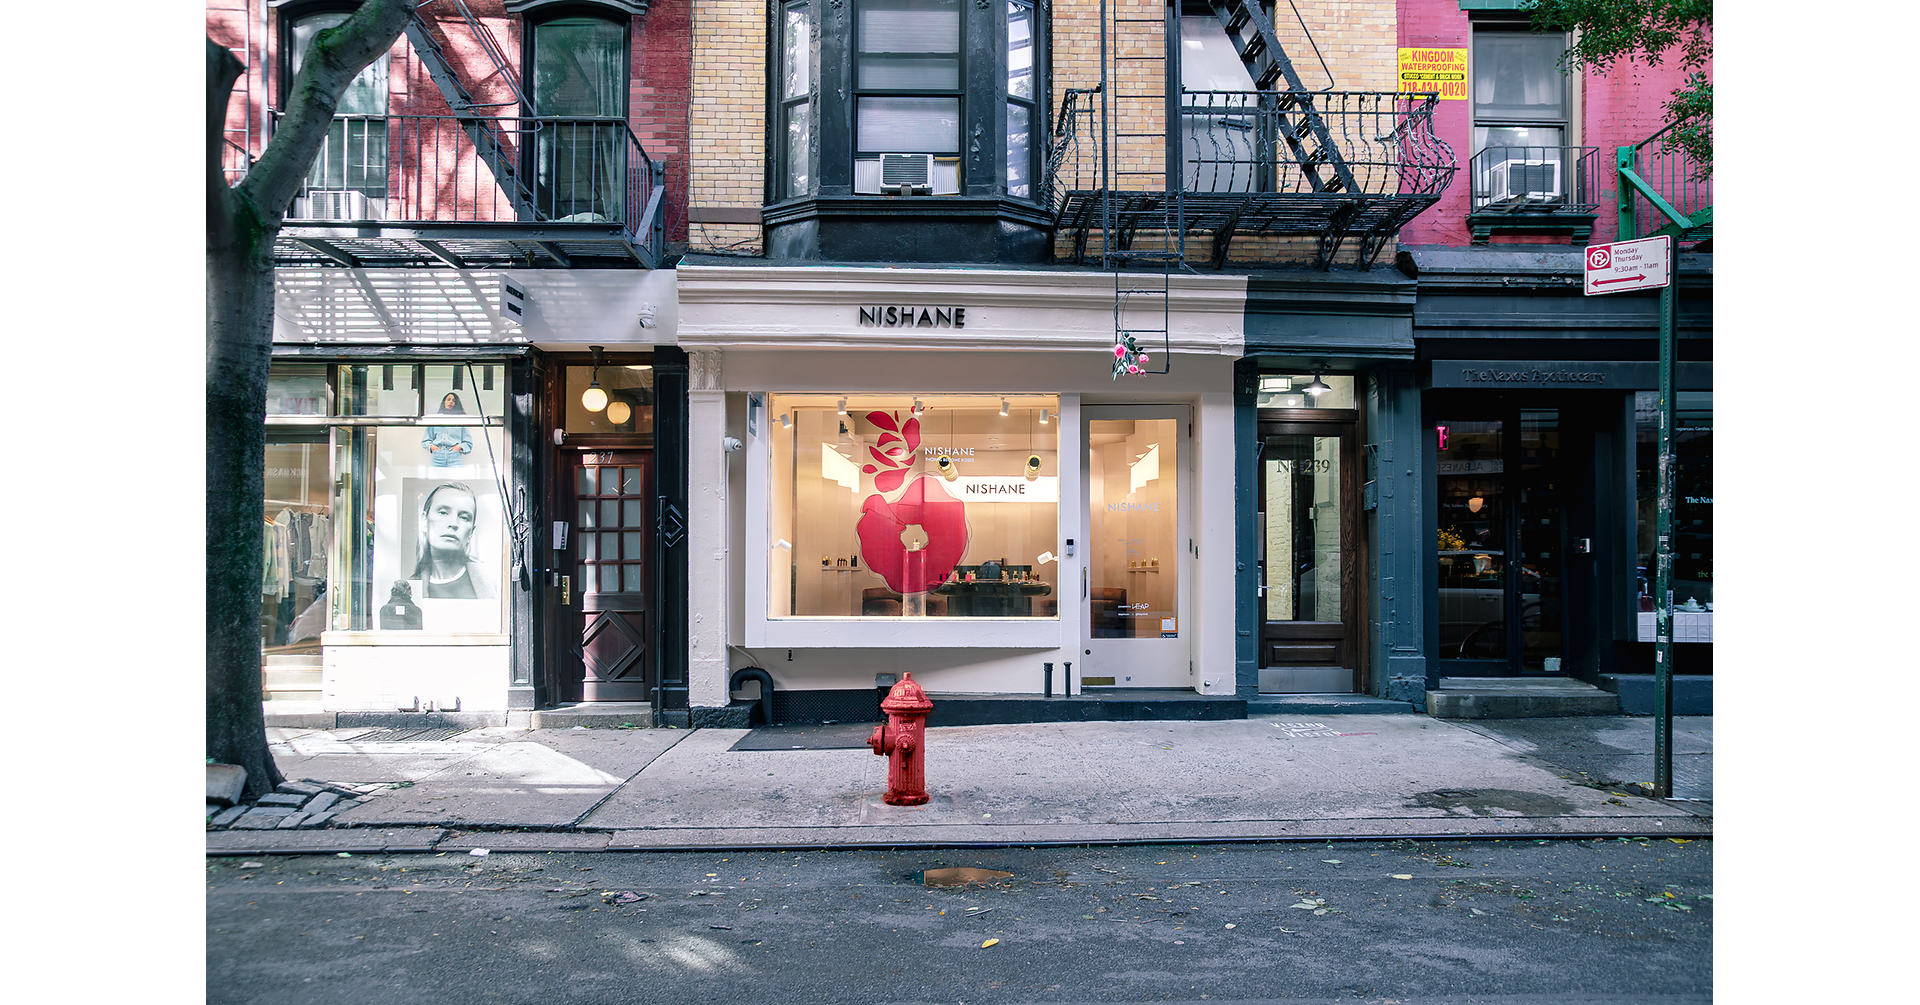
NISHANE opened its first New York boutique at 239 Elizabeth Street in Nolita on October 1, 2026, establishing a permanent U.S. location following its London boutique opening earlier this year. The store will carry the full fragrance portfolio, including Prestige Extraits with concentrations up to 40%, and support launches, private consultations and community events. The expansion reflects growing U.S. distribution through independent perfumeries, Neiman Marcus, Bloomingdale's and Nordstrom online, but is unlikely to have broad public-market implications.
Analysis
This is not a public-markets catalyst: NISHANE is private and a single flagship adds no measurable near-term earnings signal for listed U.S. department stores. The more relevant read-through is that premium niche fragrance brands continue to view U.S. direct-to-consumer retail as worth funding despite high Manhattan occupancy costs, implying confidence in full-price conversion and customer-acquisition economics at the luxury end.
For Nordstrom (JWN) and Macy's/Bloomdale's parent Macy's (M), the second-order effect is modestly negative at the margin: a proprietary boutique can shift high-intent collectors away from wholesale doors and reduces the brand's dependence on department-store promotional calendars. Conversely, Neiman Marcus is private, while Coty (COTY), Interparfums (IPAR), Estée Lauder (EL), and LVMH-linked Sephora exposure are not direct substitutes; the signal is more supportive of prestige fragrance category resilience than of any individual listed issuer.
Over 6-18 months, independent brands expanding owned retail could pressure wholesale gross margins and shelf productivity, particularly for department stores whose beauty traffic is increasingly concentrated in fragrance. The contrarian point is that a boutique network can also enlarge category awareness and create halo demand at wholesale partners; without evidence of retail-door rationalization, sell-through gains, or changed wholesale terms, this remains anecdotal rather than an investable deterioration signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Key Decisions for Investors
- No standalone trade: treat this as a qualitative datapoint, not an earnings catalyst, given the private issuer and immaterial single-store footprint.
- Maintain a 1-3 month watch on JWN and M fragrance/beauty commentary: investigate if prestige fragrance sales outperform broader beauty while vendor exclusivity and markdown support deteriorate; only then consider a relative short M versus long XLY.
- For prestige-beauty exposure, wait for EL, COTY, and IPAR quarterly disclosures on fragrance organic growth and gross margin before positioning. A broad category acceleration with stable promotional intensity would favor IPAR over EL, given IPAR's more fragrance-concentrated earnings mix.
- Falsification of the wholesale-disintermediation concern: continued department-store fragrance comp growth, stable beauty gross margins, and no increase in brand-owned retail exclusives over the next two reporting cycles.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today