
Ideal Option Releases 2025 Patient Outcomes Annual Report, Highlighting Life-Saving Treatment Amid Montana's Shifting Fentanyl Crisis
Source: PRWeb
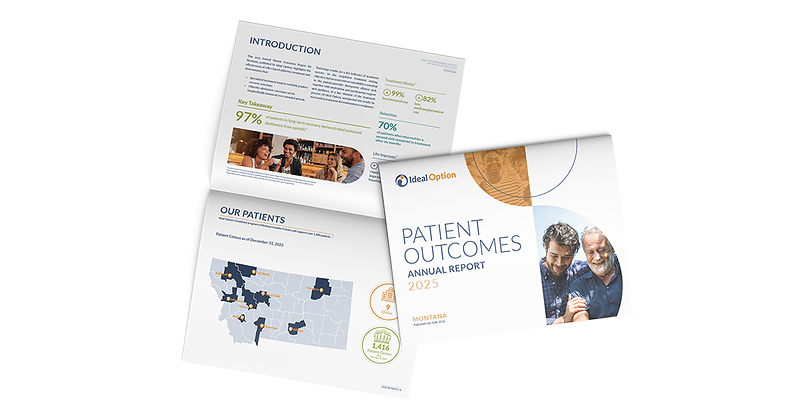
Ideal Option reported that 97% of Montana long-term medication-assisted-treatment patients sustained abstinence from opioids and stimulants in 2025, while patients reaching maintenance reduced fentanyl use by 99% and methamphetamine use by 82%. The positive treatment outcomes contrast with a worsening overdose environment: fentanyl-linked deaths rose 34% to 74 in 2025 despite a reported 70% decline in fentanyl seizures. The release is primarily an operational outcomes update for a private addiction-treatment provider and is unlikely to have broad market impact.
Analysis
This is not a public-equity catalyst: Ideal Option is private, its outcome claims are self-reported, and the Montana sample is too small to infer a revenue inflection for listed managed-care or pharma names. The investable read is instead a modest confirmation that medication-assisted treatment utilization can remain resilient even where illicit-drug conditions worsen, supporting Medicaid-funded behavioral-health demand rather than discretionary healthcare spending.
Near term (days to 3 months), no standalone trade is warranted. Watch Medicaid redetermination, state behavioral-health appropriations, and correctional re-entry contracts: reimbursement continuity is the binding constraint for outpatient MAT providers, and pressure on state budgets could outweigh rising clinical need. Public managed-care exposure is indirect through Centene (CNC), Molina Healthcare (MOH), and Elevance Health (ELV); higher treatment engagement may raise medical costs initially but can reduce expensive emergency, inpatient, and incarceration-related utilization over 12-24 months.
The non-obvious risk is that increasingly adulterated drug supply raises acuity and treatment complexity, potentially shifting care from low-cost office-based models toward emergency and inpatient settings. That would be unfavorable for state Medicaid margins and safety-net hospital economics, while potentially benefiting providers with integrated behavioral-health, pharmacy, and care-coordination capabilities. A broader policy catalyst would be federal or state reimbursement expansion for telehealth, contingency management, and post-release care; without it, clinic expansion claims should not be extrapolated into earnings expectations.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.12
Key Decisions for Investors
- No immediate position: classify as a policy/reimbursement watch item rather than a tradable company-specific event; reassess after 2027 state Medicaid budget proposals and behavioral-health rate updates.
- Monitor CNC and MOH quarterly for behavioral-health medical-cost trend, Medicaid membership retention, and management commentary on substance-use treatment utilization; a sustained adverse medical-cost revision would falsify any defensive managed-care interpretation.
- For a 6-18 month thematic basket, prefer scaled exposure to ELV over pure Medicaid names if reimbursement support broadens: its diversified commercial and services mix better absorbs a rise in behavioral-health utilization. Avoid initiating solely on this report.
- Set an alert for federal action expanding MAT/telehealth reimbursement or meaningful correctional re-entry funding. Such policy would be a more credible catalyst for behavioral-health services and pharmacy utilization than provider-reported abstinence data.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns
- Microsoft's Big Bets on AI Start to Pay Off
From AllMind Research
- AllMind Platform Feature Updates - Fall 2026
- AI Credit Covenant Monitoring: From Clause to Review
- AI-Led Expert Interviews vs. Transcript Libraries
- Automating Financial Model Updates: A Source-Controlled Workflow
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements