
GAC exportierte von Januar bis September 197.000 Fahrzeuge - der neunte Monat in Folge mit einer Verdoppelung gegenüber dem Vorjahr.
Source: PR Newswire
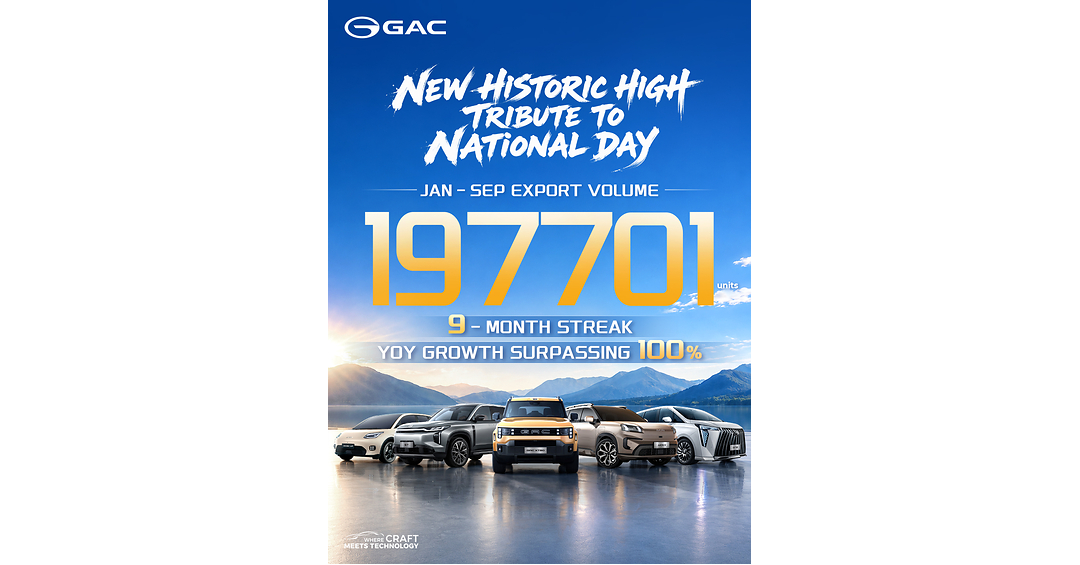
GAC exported 197,701 own-brand vehicles from January through September 2026, up 138.9% year over year and equal to 156.7% of its full-year 2025 volume; September exports rose 160.9% to 25,693 units, marking the ninth consecutive month of more than 100% growth. The company said this puts its 300,000-unit annual export target within reach. GAC also reported growth across multiple regions and highlighted overseas launches, a Cambodia factory opening, and a five-star 2026 Euro NCAP rating for the AION UT.
Analysis
The key test is whether export growth converts into durable, profitable retail demand—not whether GAC can report high year-over-year rates from expanding or initially small markets. On the stated figures, reaching 300,000 exports requires about 102,000 in Q4, or roughly 34,000 monthly: around one-third above September. That makes the target a meaningful execution hurdle, not yet evidence of a sustained run rate.
The potential upside is operating leverage from using local assembly to serve markets where importing finished vehicles is costly or exposed to tariffs. But the Cambodia plant is only an early proof point; localization may add fixed costs, supplier qualification demands, and working-capital needs before it improves economics. European AION growth is also exposed to intense price competition and the cost of building dealer, service, and parts coverage. Five-star safety certification helps market access, but does not establish attractive unit economics.
The press release gives no export revenue, model mix, pricing, inventory, or regional profitability. Regional growth rates—especially month-on-month figures—may reflect small bases, launches, or channel stocking. Near term, the headline may support sentiment; over 1–3 months, monthly export volumes and sell-through are the useful tests. Over 6–18 months, localized production and repeat purchases matter more than launch counts. A reversal would be Q4 exports materially short of the required pace, evidence of rising dealer inventory, or discounting that undermines margins. With no ticker mapping or financial detail supplied, this is not a sufficiently grounded standalone equity signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- Do not chase the release as an earnings catalyst. Treat the 300,000 export target as unverified until monthly shipment data shows a sustained pace near 34,000 in Q4.
- Set an alert for monthly export volume, retail sell-through versus wholesale shipments, and dealer inventory by region; deteriorating sell-through alongside rising exports would suggest channel loading rather than end-demand strength.
- Monitor whether Cambodia assembly progresses beyond commissioning into meaningful localized output, and whether GAC discloses localization costs, utilization, or regional profitability. Until then, treat tariff and margin benefits as conditional.
- Reassess the thesis if Q4 shipments miss the implied run rate or if evidence of discounting, inventory accumulation, or weaker export guidance emerges; stronger sell-through and disclosed profitable localization would improve the case.
More News
- CH Robinson to Buy RXO for $5.8B in Bet on AI Model
- OKX debuts a platform that turns 50 currencies into digital dollars, betting emerging market investors want stablecoins
- Nike’s China troubles: What are the implications for other sportswear brands?
- SpaceX stock climbs to highest since June, returning Musk to trillionaire status
- Schneider Electric drops $22.6B on PTC as datacenter boom rains money on infra companies
- Wells Fargo gets a bold upgrade ahead of earnings. Why the stock can play catch-up