
DAR GLOBAL DELIVERS 66% REVENUE GROWTH IN HY 2026 AS PORTFOLIO GDV REACHES US$23BN
Source: PR Newswire
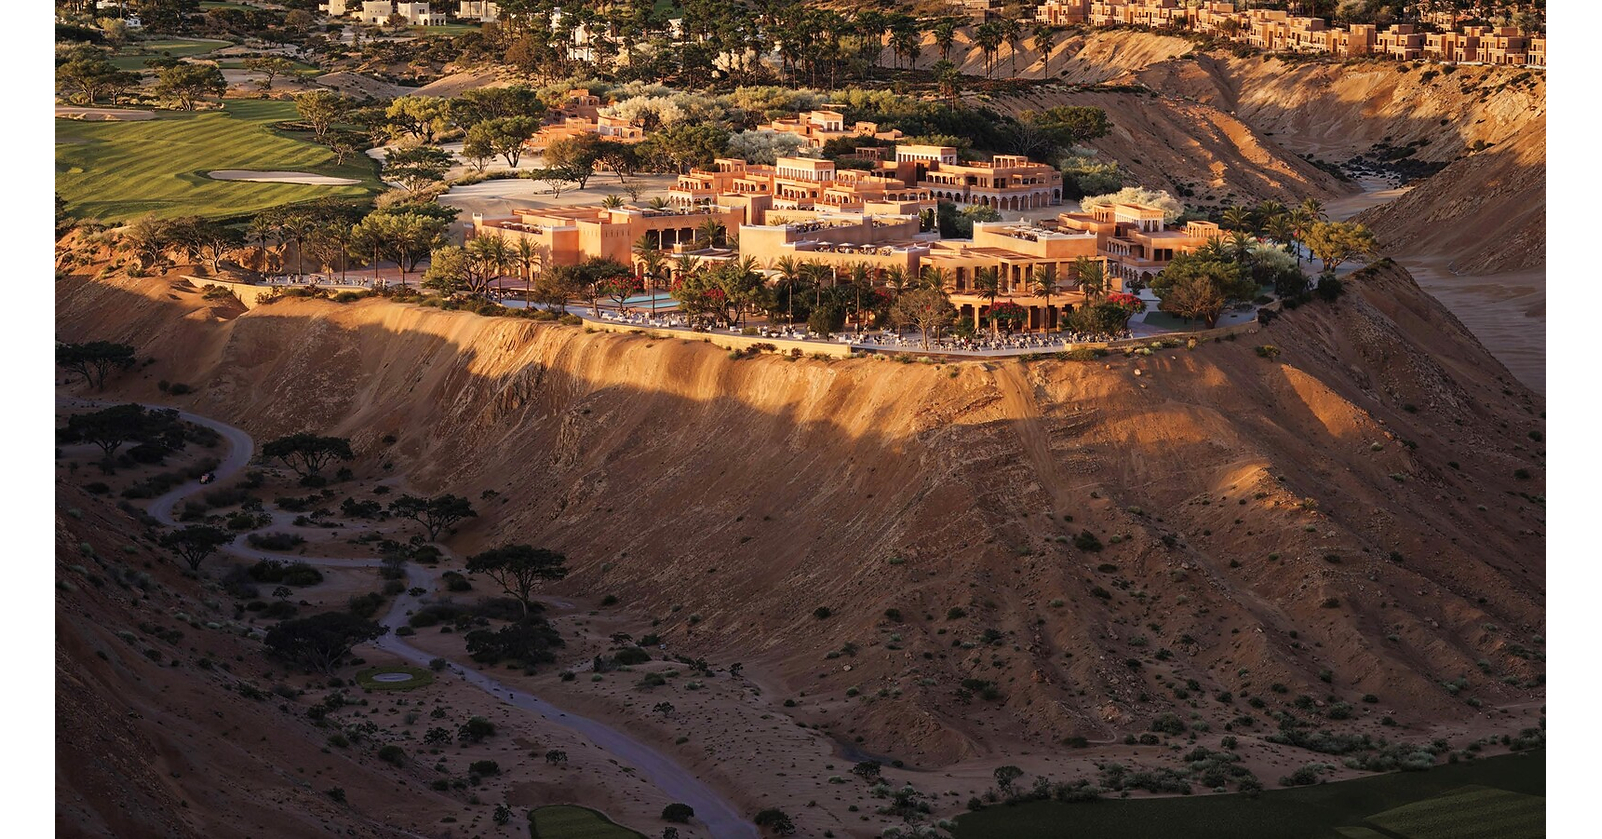
Dar Global reported HY 2026 revenue growth of 66% to $258.0 million, while gross profit rose 85% to $87.7 million and net profit surged 149% to $30.4 million. Gross development value nearly doubled year-on-year to $23.0 billion, with cumulative contracted sales reaching $3.9 billion across 4,380 units. The developer ended the period with $579.3 million of available liquidity and strengthened funding through a $250 million syndicated term loan, supporting continued expansion in Saudi Arabia, Dubai and other international luxury-property markets.
Analysis
DAR’s earnings quality should be assessed through contracted-sales conversion rather than the reported revenue growth rate: luxury development accounting can create material period-to-period volatility as projects cross completion milestones. The margin expansion is encouraging, but the key underwriting question is whether the contracted-sales base converts into cash collections without incremental discounting or construction-cost leakage; the gap between headline cash, free cash and available liquidity suggests investors should focus on restricted customer deposits, debt covenants and project-level funding in the full interim filing.
The enlarged development pipeline creates a positive operating-leverage setup over 12-36 months, but also raises execution and capital-intensity risk materially before revenue recognition catches up. Saudi and Dubai exposure concentrates the upside in high-net-worth foreign-buyer demand, where branded residences can sustain pricing premiums, but these buyers are more sensitive to geopolitical headlines, UK/EU tax changes, and regional asset-price liquidity than domestic housing metrics imply. Construction awards are not proof of sell-through; rising contractor costs, delayed permits, or slower off-plan collections would pressure both gross margin and net working capital.
There is limited direct read-through to AML despite the branding association. Any royalty, design-fee, or brand-visibility benefit is likely immaterial to AML’s automotive earnings unless management discloses contract economics; treating this as an AML demand signal would be a category error. Consensus may also underappreciate the reputational optionality and political sensitivity embedded in the Trump-branded projects: brand-led demand can accelerate reservations in select buyer cohorts, but it increases event risk around regulatory approvals, financing counterparties and buyer composition.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Maintain or initiate a modest long DAR only after confirming H1 cash-flow conversion, net debt and restricted-cash definitions in the interim report; target a 6-12 month rerating if contracted-sales conversion and gross margin remain intact. Size conservatively given likely London-market liquidity and development-accounting volatility.
- Use the next 1-3 months to monitor reservation velocity, cancellation rates, collection milestones and presales on Saudi projects. Reduce exposure if management reports slower collections, materially higher build-cost assumptions, or draws incremental debt before project cash receipts; these would falsify the self-funded-growth thesis.
- Do not add AML on this release. Revisit only if AML quantifies recurring licensing/royalty income or identifies branded-residence economics as material; absent disclosure, the risk/reward remains driven by automotive volumes, pricing and leverage rather than DAR’s project pipeline.
- For investors seeking a relative-value expression, prefer long DAR versus a broad UK residential-development proxy rather than a directional housing trade over 6-18 months: DAR’s luxury international buyer base and branded-product mix should be less tied to UK mortgage rates, while the trade fails if GCC luxury demand weakens or UK developers receive a sharper rate-cut-driven valuation rerating.
More News
- Ten Reasons Investors Are Driving Government Bond Yields Higher
- Asian stocks dip, bonds in focus after torrid September
- September Ends on a Grim Market Note: Evening Briefing Americas
- China’s Property Crisis: From Evergrande Collapse to Beijing’s Latest Measures
- Paramount Skydance prices $42 billion debt for Warner Bros deal
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?