
The Parisian Macao Celebrates 10th Anniversary
Source: PR Newswire
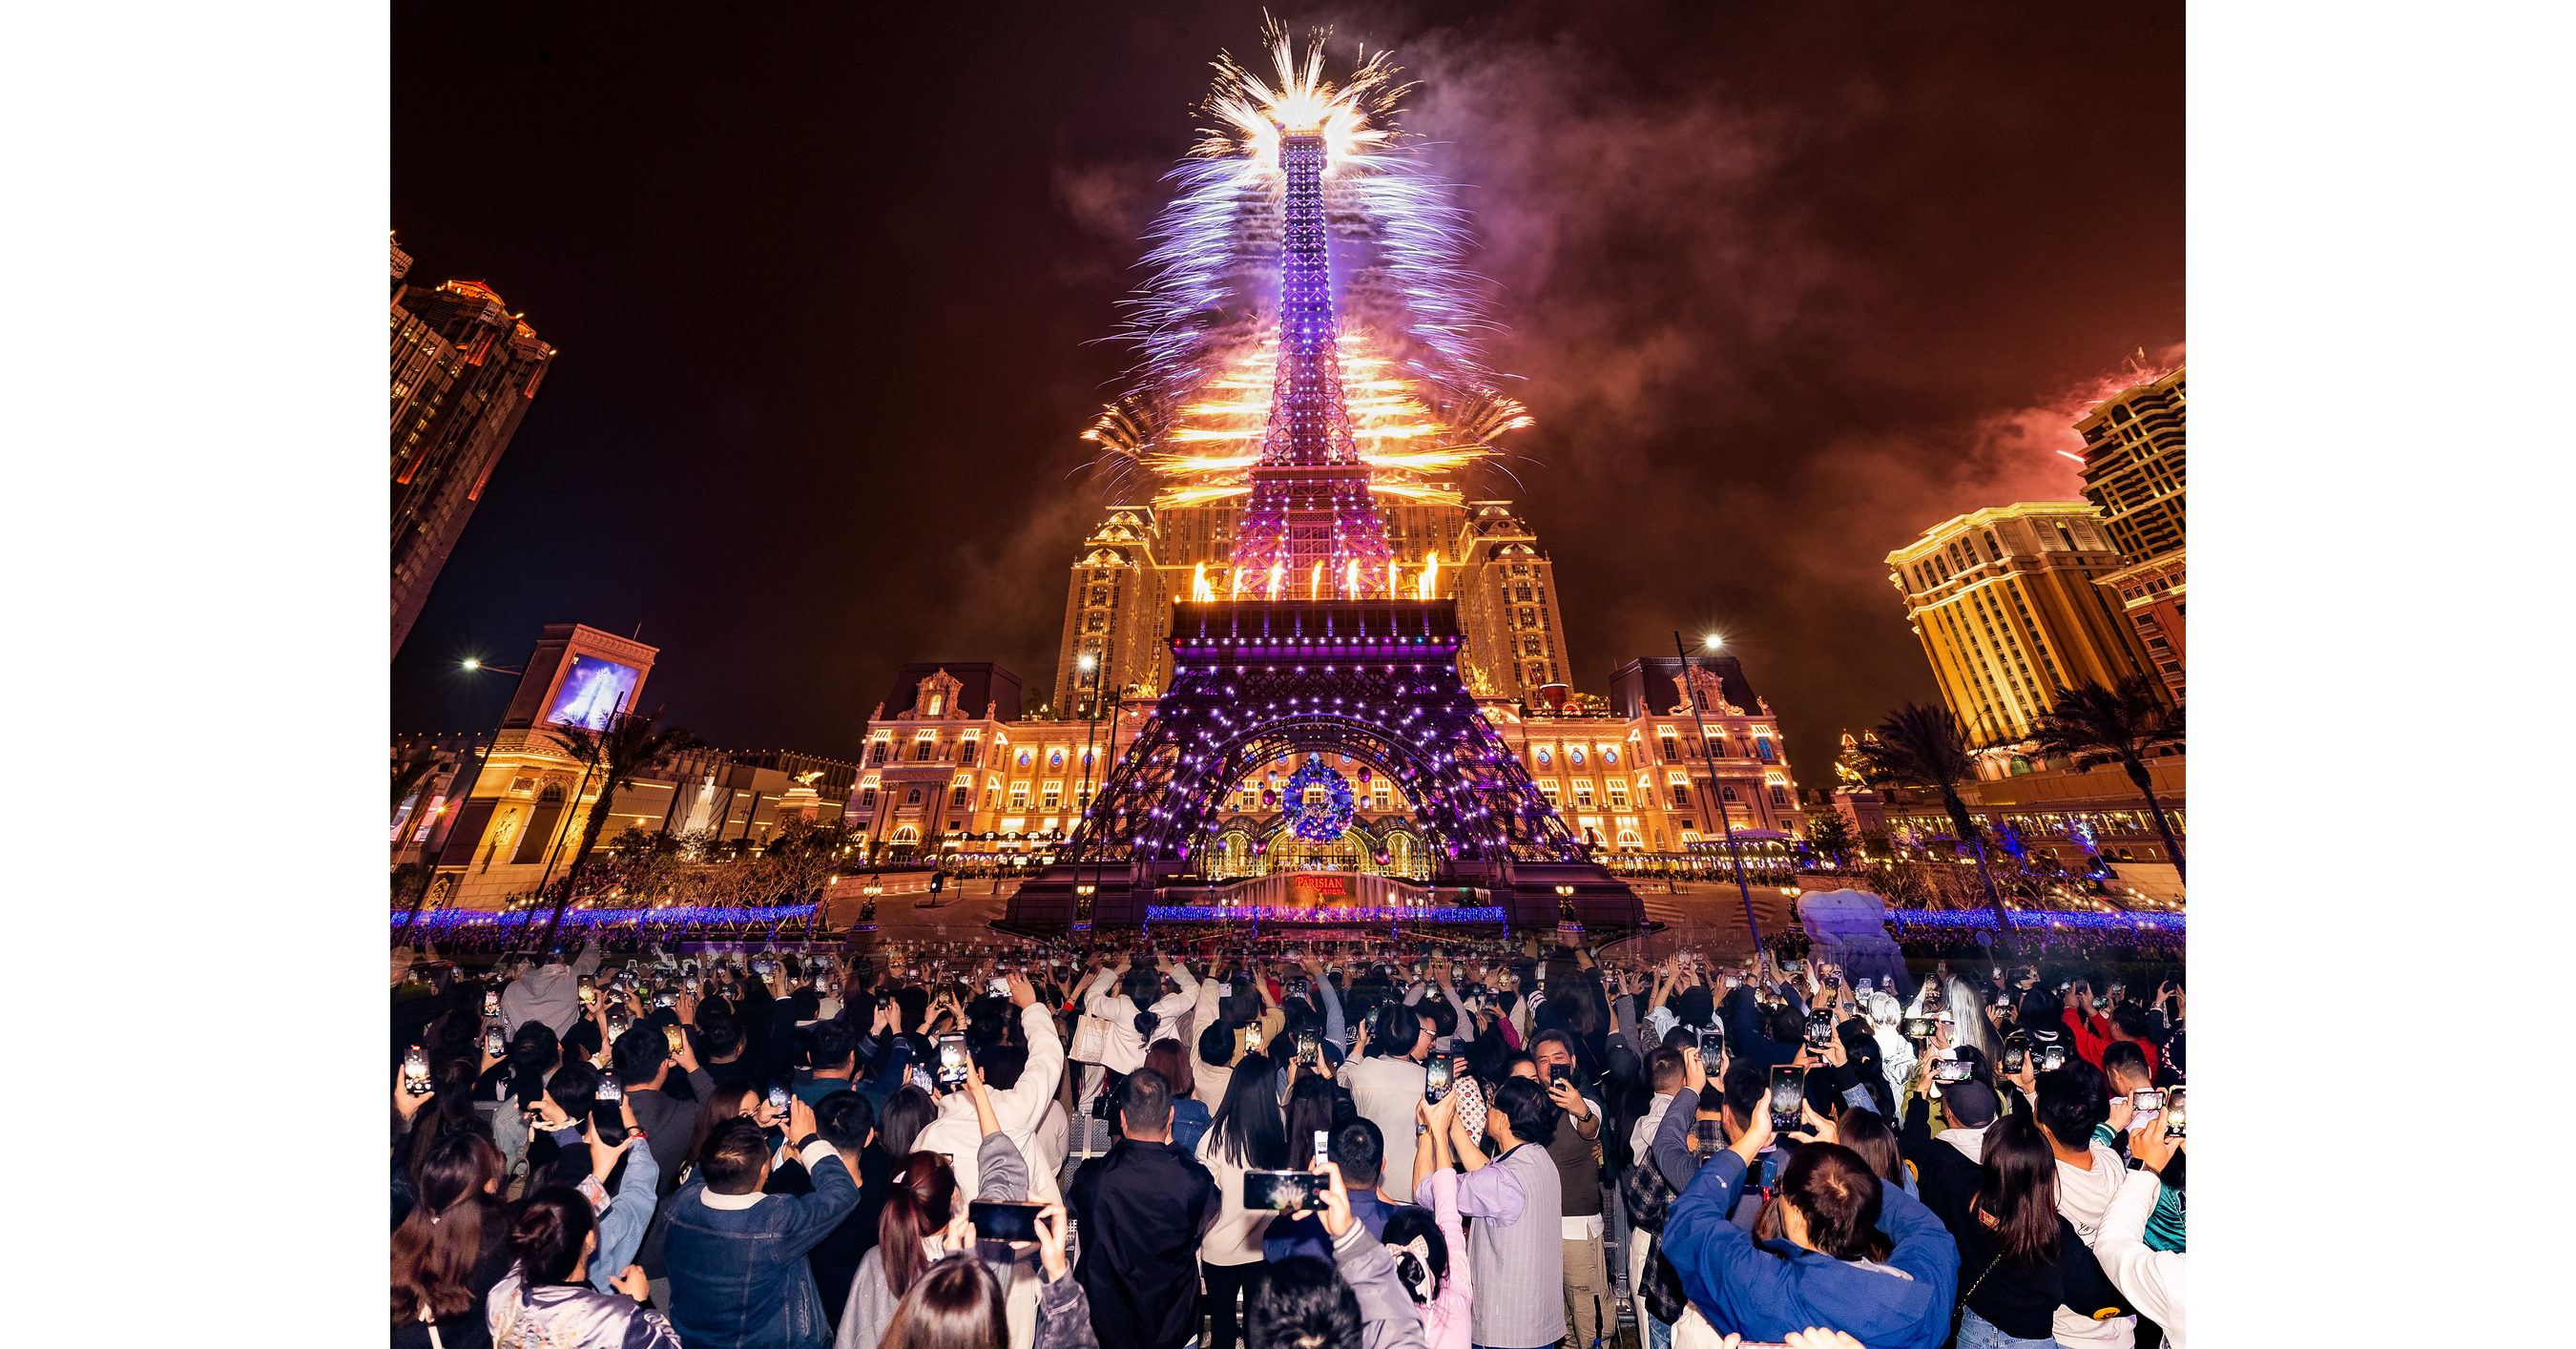
Sands China said The Parisian Macao has surpassed 100 million visitor visits since opening in 2016, marking its 10th anniversary with new dining, entertainment and promotional events. The property offers more than 2,540 hotel rooms, 62,000 square feet of MICE space, a 1,200-seat theater and 297,000 square feet of retail space. The company reaffirmed its intention to continue investing in non-gaming tourism, entertainment, retail and convention offerings to support Macao's economic diversification, but disclosed no new financial targets or material capital commitments.
Analysis
This is promotional rather than earnings-relevant disclosure, but it reinforces LVS's strategic fit with Macau's policy priorities—a critical consideration ahead of future concession reviews and for approvals tied to incremental non-gaming investment. The economic value is not the anniversary programming itself; it is the potential to sustain premium-mass visitation, hotel occupancy and retail tenant productivity while limiting reliance on volatile VIP gaming revenue. Any improvement in retail/MICE mix is likely to be lower-margin than gaming in isolation, but can raise property-level ROIC through better utilization of an already-built Cotai asset base.
The key competitive implication is relative: LVS has the greatest Macau room, retail and convention footprint, making it disproportionately exposed if the market shifts toward overnight family, events and higher-spend leisure travelers rather than same-day gaming visitors. That favors LVS versus MGM China (2282 HK) and Galaxy Entertainment (27 HK) on non-gaming capacity, though Galaxy's newer Cotai assets remain a meaningful premium-mass competitor. Near term, the company-funded events are too small and too short-lived to alter consensus EBITDA; investors should not extrapolate promotional visitor counts into incremental gaming or retail revenue without evidence in monthly GGR, hotel ADR and mall-sales data.
Over the next 1-3 months, LVS can outperform on evidence that Golden Week and convention calendars lift overnight stays and premium-mass spend without a corresponding increase in promotional expense. Over 6-18 months, the upside case rests on Macau's tourism diversification increasing weekday utilization and smoothing seasonality, which would support EBITDA multiple expansion and reduce perceived China-policy risk. The thesis fails if mainland consumer weakness constrains overnight discretionary spend, Macau gaming-revenue growth decelerates materially, or non-gaming capex and marketing rise faster than incremental property EBITDA.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release; treat it as a monitoring item rather than a catalyst. Reassess LVS after the next monthly Macau GGR print and quarterly results, with particular focus on premium-mass revenue, hotel ADR/occupancy, retail rental performance and property EBITDA margin.
- Maintain a 3-6 month relative long LVS / short MGM China (2282 HK) only if LVS continues to show superior overnight-visitor and non-gaming monetization metrics. The pair limits broad Macau-demand beta; exit if MGM China closes the property-EBITDA growth gap for two consecutive reporting periods.
- For long-only exposure, add LVS only on a post-data pullback rather than ahead of promotional events. A constructive trigger would be resilient Macau GGR combined with management confirmation that non-gaming initiatives are funded within existing capex and do not dilute EBITDA margins; invalidation is a downward revision to Macau margin or capex guidance.
- Watch Galaxy Entertainment (27 HK) as the principal relative-risk hedge: evidence of stronger premium-mass growth at Galaxy's Cotai properties would challenge the assumption that LVS's scale converts into superior share gains. If Galaxy materially outgrows LVS in premium mass while LVS's margins weaken, rotate relative exposure from LVS toward Galaxy.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- What next for France as riots rattle markets? Three questions facing investors ahead of more protests
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Automating Financial Model Updates: A Source-Controlled Workflow
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts