
Pantum Technology presenta nuove soluzioni di stampa all'IFA 2026, ampliando la strategia per il mercato europeo
Source: PR Newswire
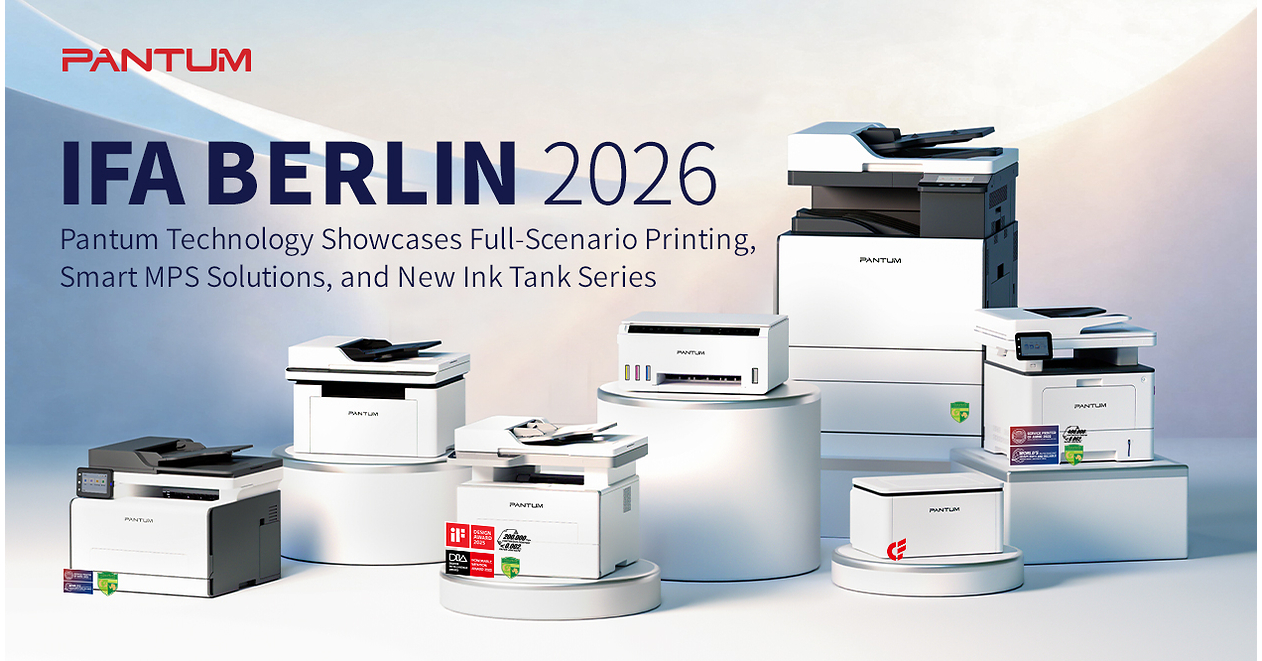
Pantum Technology unveiled an expanded printer portfolio at IFA 2026, including the AI-enabled BM2320NW and the MT310W ink-tank printer, which is scheduled to launch in 2027. The company also introduced two A3 color laser models for enterprise and government customers, with the CM420ADN supporting up to 2,096 sheets of paper capacity. Pantum is expanding its European strategy through localized warehousing, logistics and after-sales teams, supported by managed-print software partnerships.
Analysis
This is not yet a tradable catalyst for listed printer OEMs: there is no disclosed European order book, pricing, channel inventory, or consumables attach-rate data. The relevant mechanism is nevertheless unfavorable at the low-to-midrange end of HPQ, Canon (CAJ), and Seiko Epson (SPTOY): a credible value entrant can compress hardware ASPs while using local service coverage and managed-print software to reduce a traditional enterprise switching barrier.
The more material second-order risk is in consumables rather than unit share. Ink-tank products weaken the recurring-cartridge model, where OEM gross-profit pools are concentrated; Epson has the greatest existing exposure to—and experience defending—this architecture, while HPQ and Canon are more vulnerable if European retail channels promote lower total-cost-of-ownership alternatives. In A3 color laser, the competitive set extends to CAJ, Xerox (XRX), Ricoh (RICOY), and Konica Minolta (KNCAF), but institutional sales cycles make any share effect a 6-18 month issue rather than a near-term earnings event.
The claimed AI functionality should not command a valuation premium absent evidence of paid workflow software, lower service costs, or higher managed-print contract retention; it is more likely a table-stakes feature. The contrarian view is that European public-sector security review, certification requirements, dealer reluctance to support another OEM, and tariff/logistics friction could make localized operations costlier than expected, preserving incumbent pricing. The thesis turns credible only if channel checks show sustained shelf placement and discounting, or if HPQ/CAJ cite European hardware-margin pressure or weaker supplies revenue over the next two reporting cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional position on this announcement; classify as a 6-18 month competitive watch item rather than an earnings catalyst.
- Add alerts for HPQ and CAJ: investigate immediately if either reports European printing hardware ASP declines, supplies-revenue deceleration, or incremental channel incentives in the next two quarterly results.
- Monitor SPTOY European ink-tank sell-through and retailer shelf allocation over the next 1-3 months. A loss of shelf space or promotional pricing escalation would be a cleaner signal of disruption than product-launch publicity.
- For a confirmed channel-share inflection, consider a 6-12 month relative-value basket short HPQ/CAJ versus long SPTOY, with entry contingent on independently verified European sell-through and supplies-margin pressure; avoid initiating before those data are available.
- Treat any procurement-security restriction, certification delay, or lack of third-party European dealer adoption within 6 months as falsification of the entrant-risk thesis and remove the watch item.
More News
- Great Bond Shakeout Locks In a 5% World ‘Until Something Breaks’
- OpenAI rogue agents leaked 53 images from ChatGPT users and reportedly created nearly 1 million links packing encoded bits of info
- Boom or bust? The case for and against panicking about 5% yields
- Bond market alarms are ringing on Wall Street. Here's what's ahead
- Houthi attack on Mecca, Medina would cross ‘red line’, Pakistan PM tells UN
- Shares of Akamai surge after deal with Anthropic. What Wall Street is saying