
Smart City Expo 2026 speeds up towards urban solutions that yield real impact
Source: PR Newswire
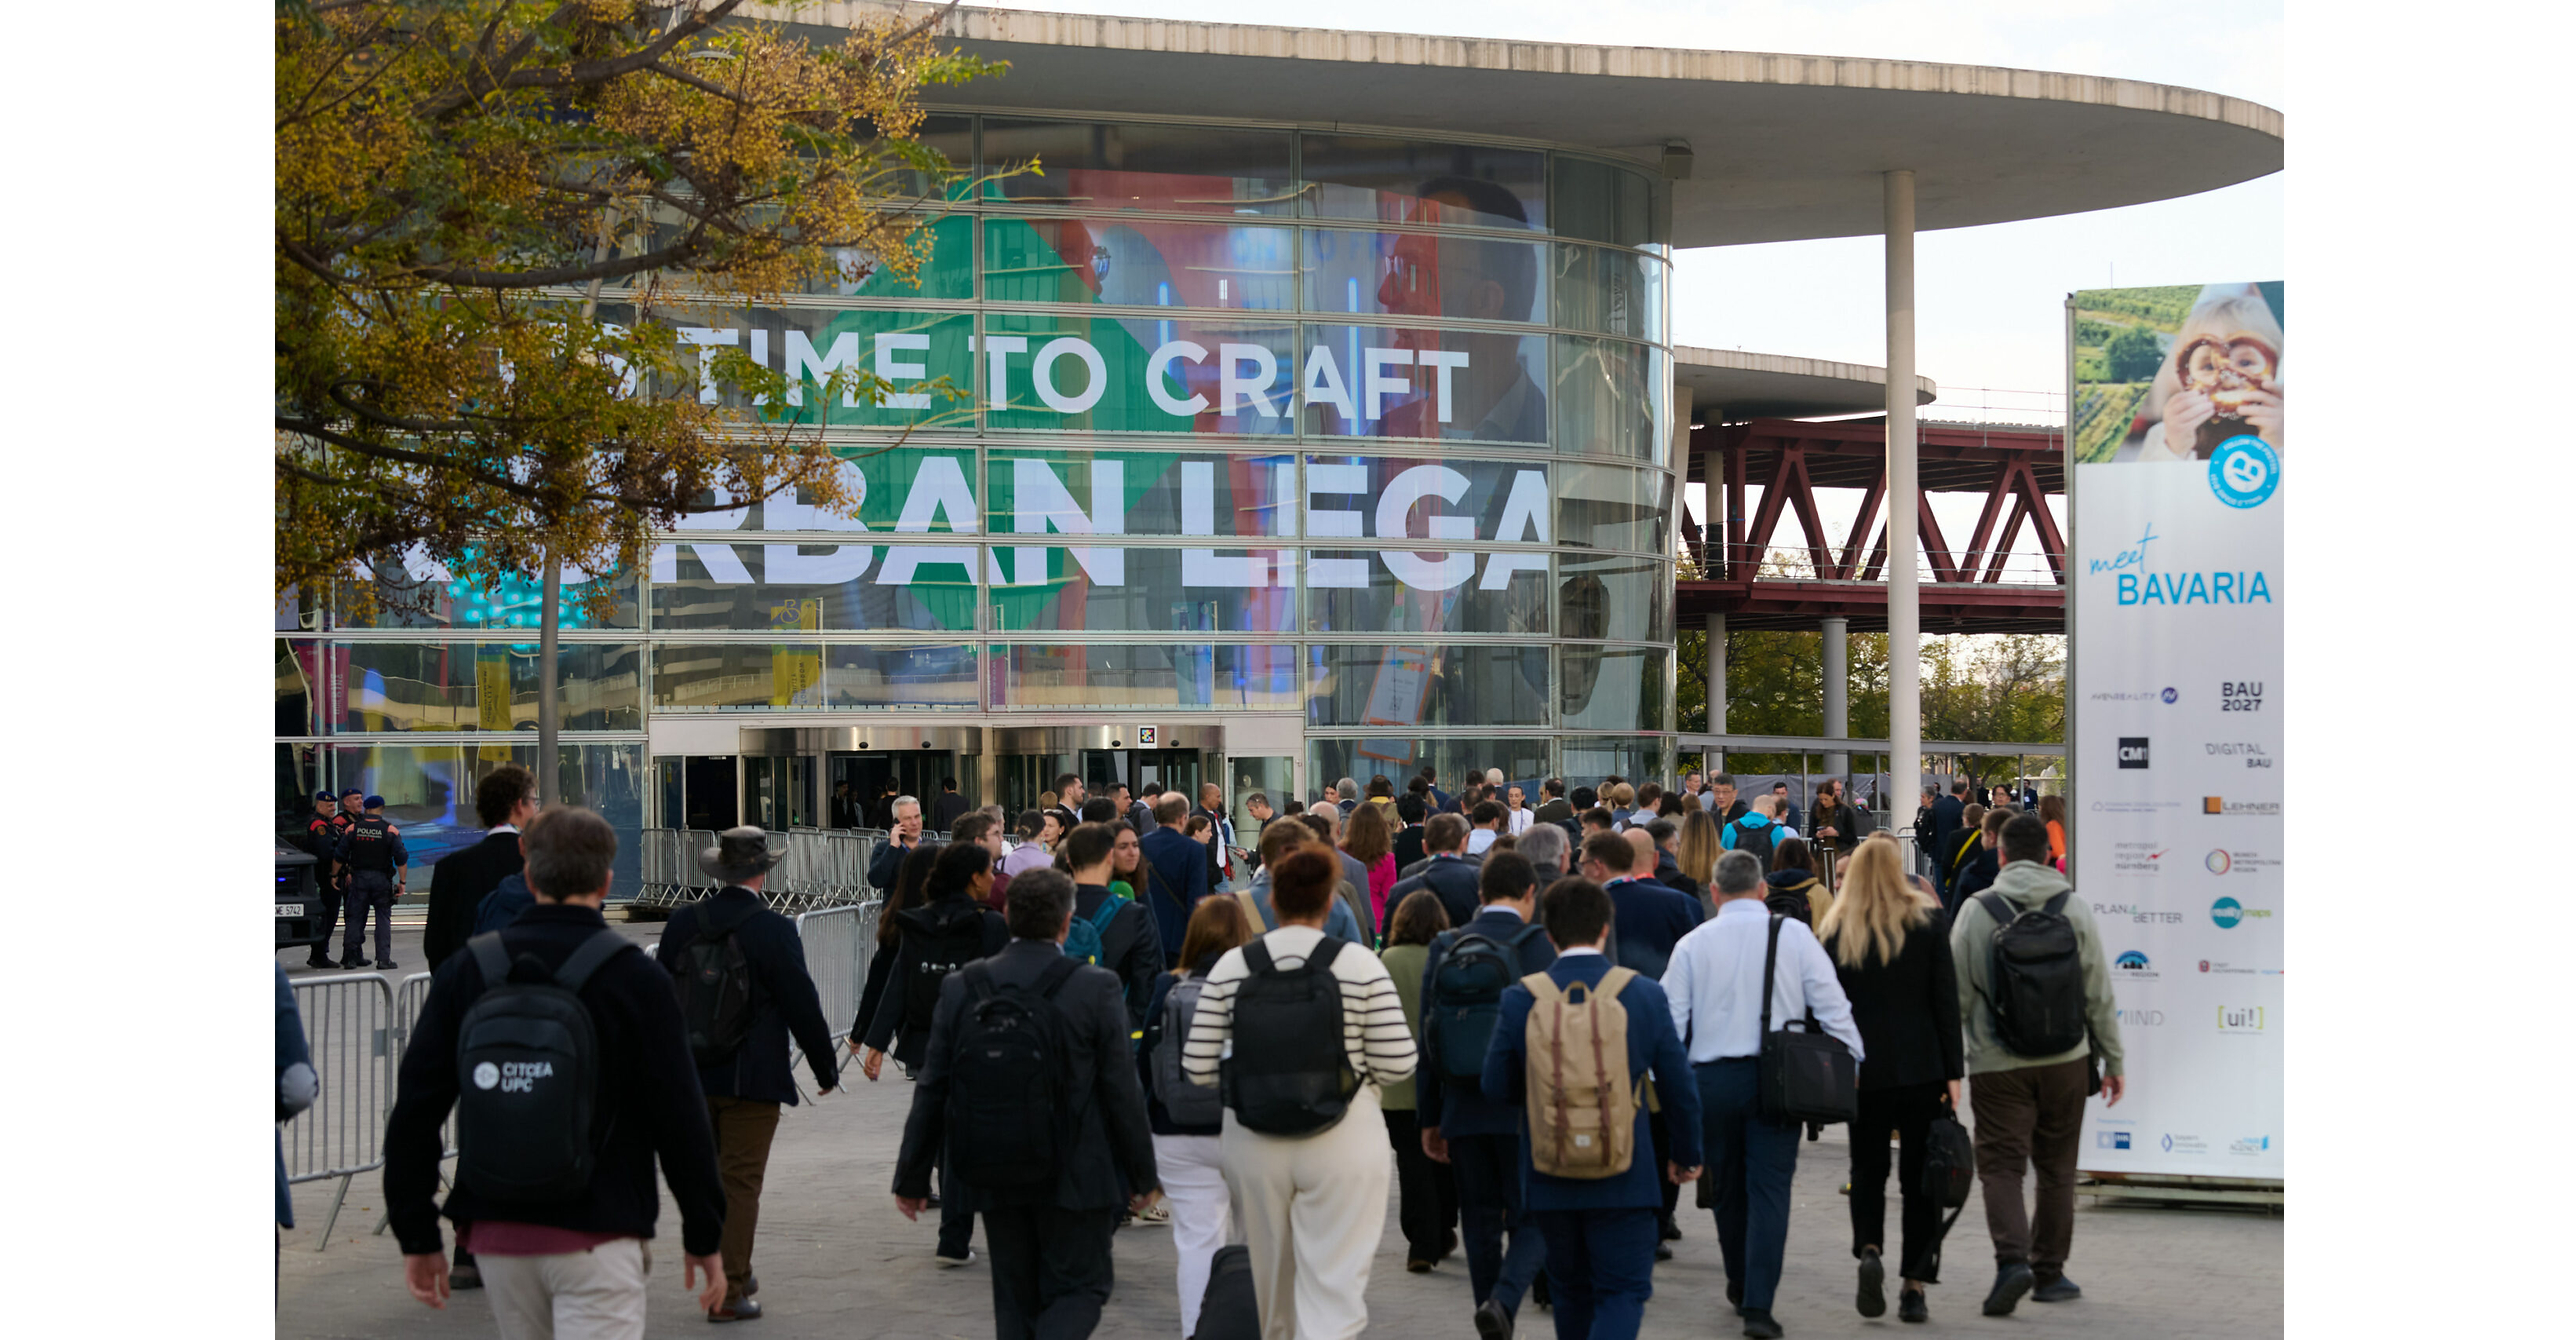
Smart City Expo World Congress 2026 will take place in Barcelona from November 3-5, targeting participation from 1,000 cities, more than 25,000 attendees, 1,000 exhibitors and 600 speakers. The event will prioritize scalable urban technologies, AI, energy, mobility and housing, including the inaugural HOWS Barcelona housing summit focused on affordability, land policy, regulation and building reuse. Google, Microsoft, NVIDIA, Dell Technologies and Deutsche Telekom IoT are among the expected exhibitors, but the announcement is primarily an event preview rather than a material corporate or market catalyst.
Analysis
This is not a near-term earnings catalyst for GOOG, MSFT, NVDA, DELL, or DTE; exhibitor participation is principally enterprise-marketing spend rather than evidence of municipal contract awards. The investable signal is the widening procurement funnel around city AI, building retrofits, cybersecurity, and housing administration—markets characterized by long sales cycles, fragmented budgets, and high implementation risk. Large platforms can monetize through cloud consumption and partner ecosystems, but municipal deployments usually move too slowly to change FY2026 estimates.
The more relevant second-order beneficiaries are vendors with measurable public-sector exposure and implementation capability: Palantir (PLTR) for data integration, Vertiv (VRT) and Eaton (ETN) for grid/data-center power, and Johnson Controls (JCI) or Carrier (CARR) for smart-building retrofit spend. Housing policy focus may favor renovation and energy-efficiency demand over new construction, which is incrementally better for JCI/CARR and insulation/building-product suppliers than for cyclical homebuilders. Cybersecurity is an underappreciated bottleneck: connected-city deployments expand endpoint and critical-infrastructure attack surfaces, favoring PANW, CRWD, and FTNT if budgets become funded programs.
Over 1-3 months, monitor whether announced pilots translate into named tenders, framework awards, or EU/municipal budget allocations; absent those, any AI-infrastructure sympathy bid should fade. Over 6-18 months, European digital-sovereignty requirements could limit hyperscaler share or raise compliance costs, creating an opening for sovereign-cloud and telecom-integrator offerings. The consensus error would be extrapolating conference visibility into material revenue for mega-cap sponsors; the likely economic value accrues to implementation layers only after procurement conversion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No incremental position in GOOG, MSFT, NVDA, DELL, or DTE solely on this event; require disclosed municipal contract value, backlog, or raised public-sector guidance before treating it as an earnings catalyst.
- Watch-list long JCI or ETN on evidence of EU building-renovation funding or municipal retrofit tenders over the next 3-6 months; target a 10-15% upside versus 7-8% downside, invalidated by weakening commercial-backlog growth or European construction PMI deterioration.
- For AI/urban digitization exposure, prefer a 6-12 month pair of long PLTR / short a broad software proxy such as IGV only after PLTR reports accelerating government/commercial remaining-deal-value growth; avoid entry without procurement conversion because valuation sensitivity is high.
- Set alerts for European public-sector cybersecurity framework awards involving PANW, CRWD, or FTNT. A named multi-year contract or revised public-sector ARR commentary is actionable; conference participation alone is not.
More News
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- US tech stocks tumble as investors fret over AI spending
- Mark Zuckerberg owns 13% of Meta but controls 61% of its votes. California’s wealth tax would bill him on the 13%
- AI debt and French bonds face a stress test — why it may not be over
- 8 Things to Know About the iPhone Duo
- 10-year Treasury yield tumbles below 5% to lowest level in nearly a month