
The Second Global Business Summit on BRI Infrastructure to Accelerate the SDGs Held in Singapore
Source: PR Newswire
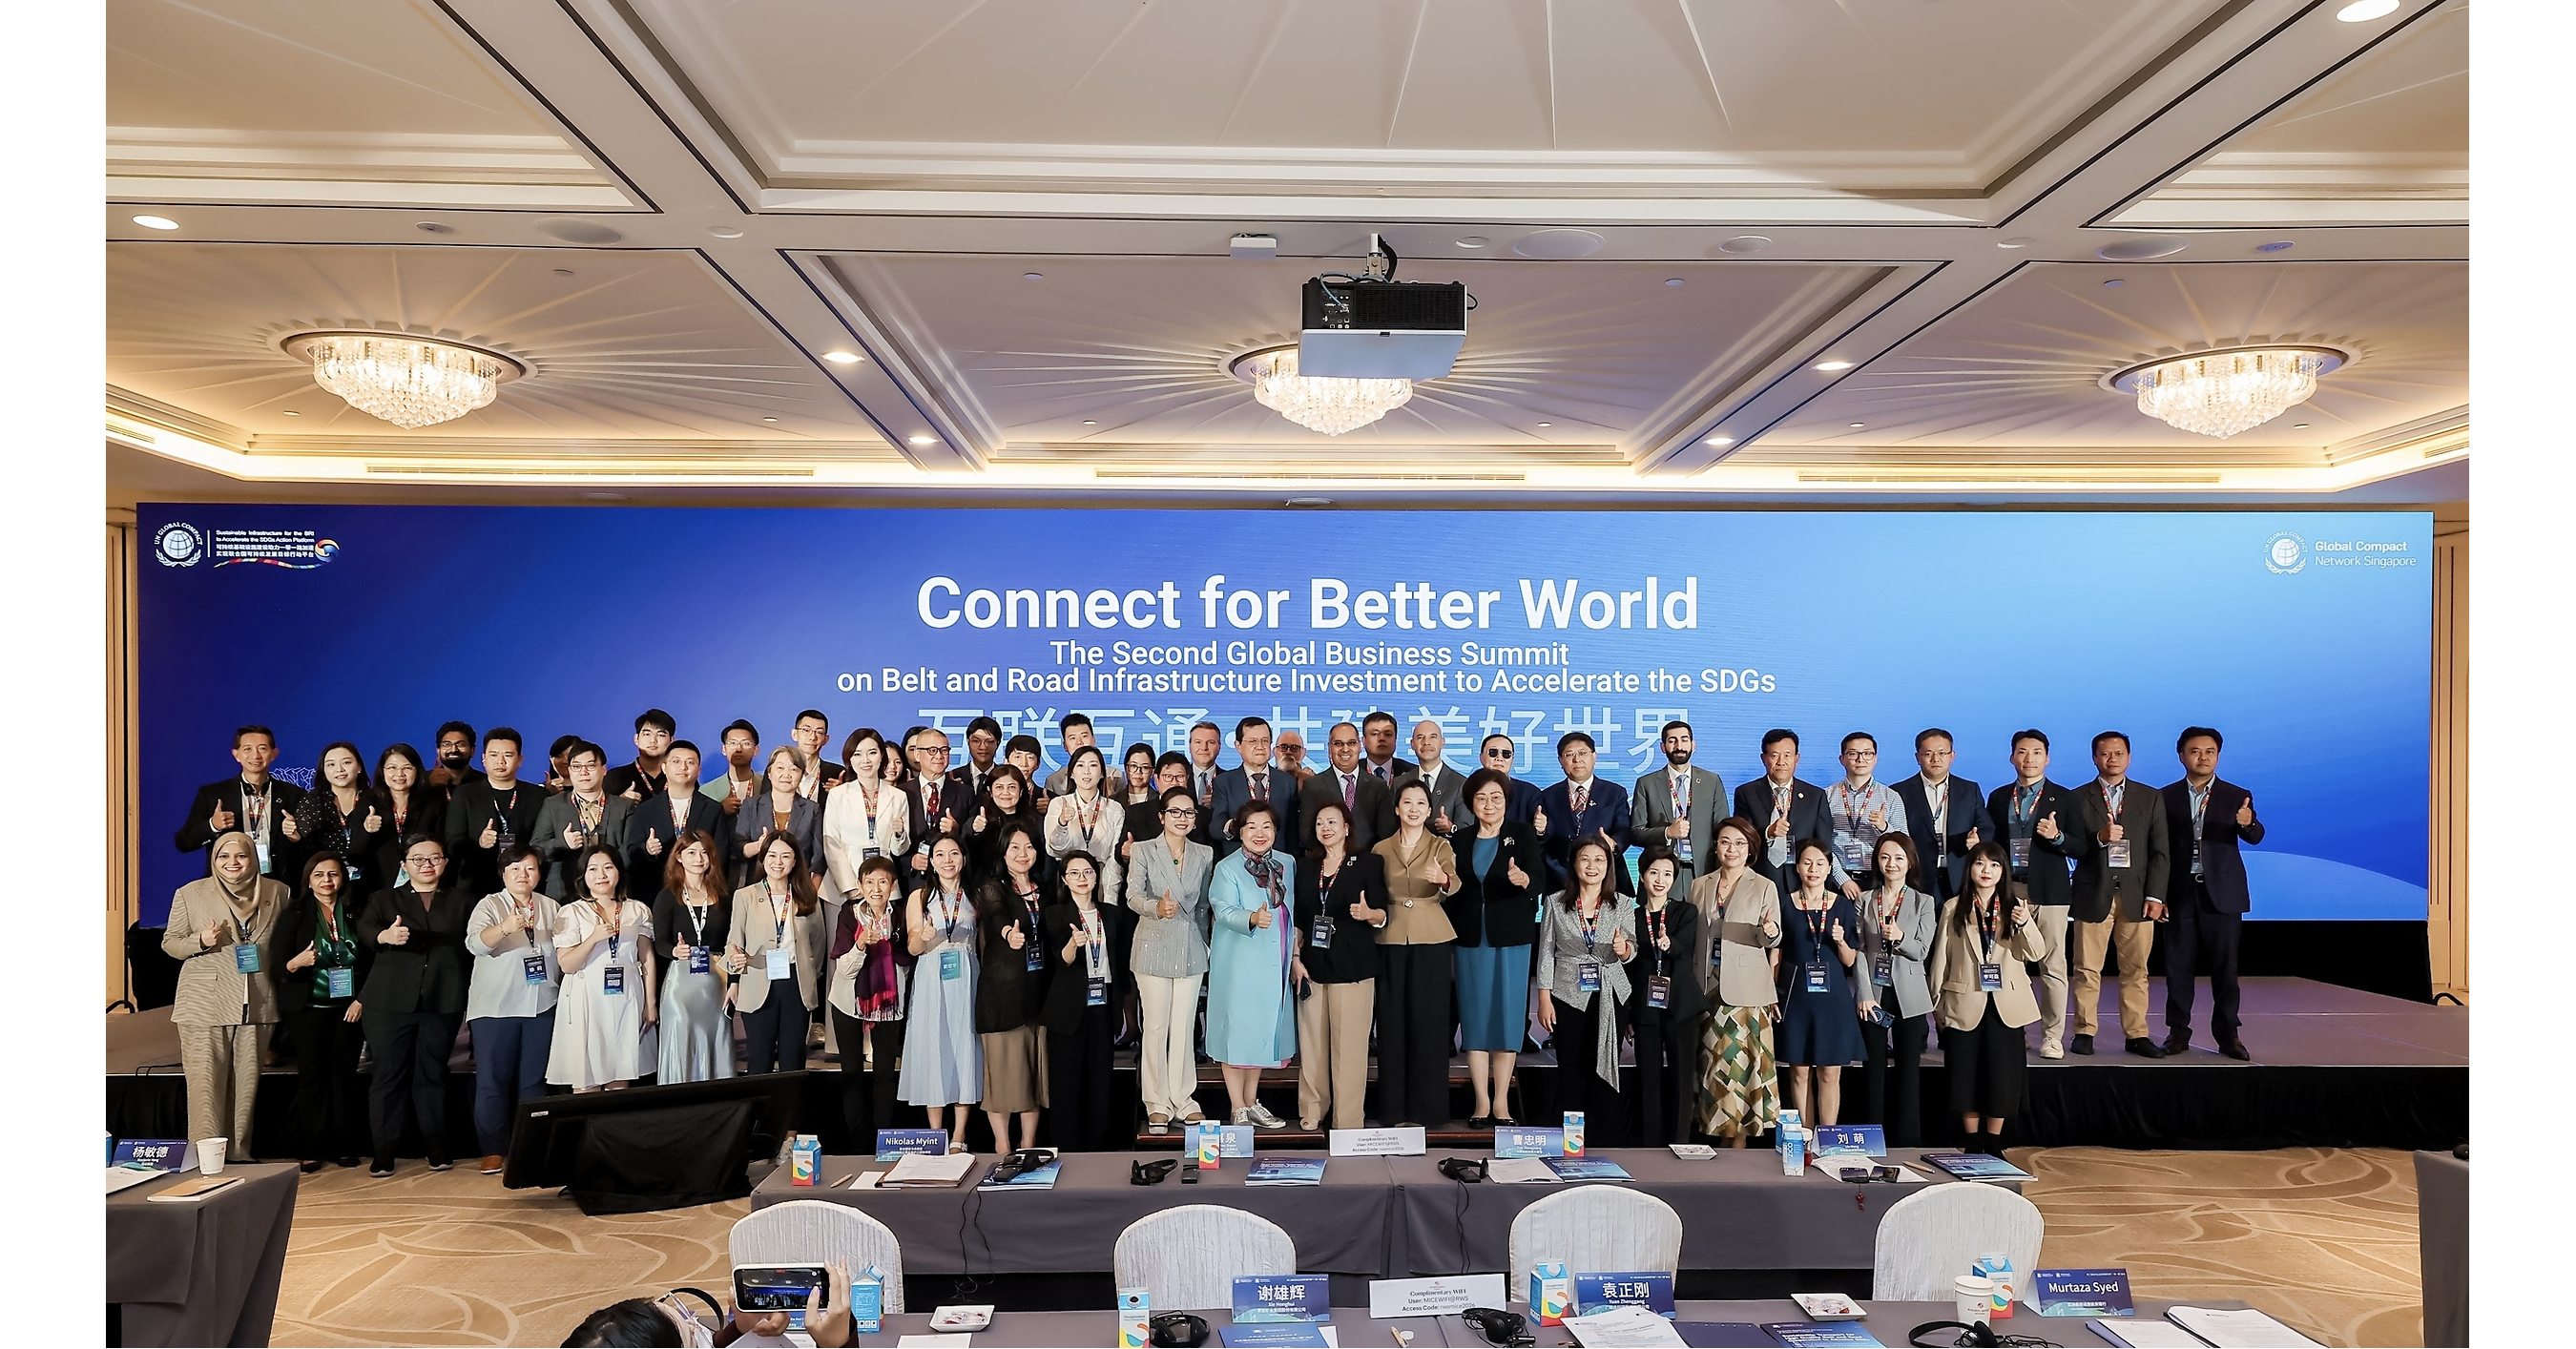
The Summit, convening 300+ senior leaders, launched a dozen sustainability-driven joint actions and expert groups under a BRI-for-SDGs framework, including priorities for responsible AI, green energy transition, resilient global supply chains, and sustainable finance. It also announced 12 SDG-linked outcomes spanning green mining, electricity carbon-footprint standards, biodiversity and ocean protection, sustainable transport, and women’s microenterprise growth. While non-financial, the initiative is positioned to catalyze cross-border cooperation and investment opportunities for sustainable infrastructure over the SDG/2030 horizon.
Analysis
This reads more like a signaling event than a cash-flow event. The investable takeaway is not immediate revenue, but a gradual shift in what gets financed: projects with cleaner disclosure, better carbon accounting, and stronger cross-border governance should get lower funding frictions, while undifferentiated EPCs and commodity-heavy suppliers risk being screened out. In practice, the winners are likely to be large balance-sheet lenders, grid/switchgear vendors, rail/port equipment makers, and data/infrastructure integrators that can package compliance into project finance.
The second-order effect is that ESG framing can raise the bar for BRI capital allocation, which is bullish for quality and bearish for weak operators. That creates a spread trade inside infrastructure: assets with bankable contracts and audited standards can trade at a premium, while smaller contractors may see margin pressure from reporting, certification, and vendor qualification costs. The effect is likely to show up over 1-3 quarters through awards and financing terms, not overnight in earnings.
Contrarian view: the market may overread the rhetoric and underread execution constraints. Without named funding commitments, sovereign guarantees, or project-level procurement, this is mostly option value. The thesis is falsified if there is no pickup in policy-bank lending, cross-border project awards, or capex conversion by the next few quarters; in that case, the event fades and the listed proxies revert to macro beta.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate position in the named micro-caps (CETY, FISI, GSIL, SCPAF, WWRL, YYYH); treat them as watch items only until there is a disclosed contract, financing, or backlog update over the next 30-60 days.
- Tactical relative-value idea: long EEM / short EFA for 3-6 months to express a modest ASEAN/EM infrastructure and supply-chain re-routing benefit; exit if China credit impulse or EM FX weakens materially.
- If you want a cleaner quality-vs-rhetoric expression, pair long industrial infrastructure quality names via XLI or PAVE against a basket of smaller-cap industrials; keep it small because the signal is policy-dependent and likely to mean-revert without project awards.
- Set an alert for policy-bank lending and fixed-asset investment data in China over the next 1-2 quarters; if those do not inflect, fade any ESG/BRI enthusiasm and avoid paying up for thematic multiples.
More News
- Jio’s Record $3.2 Billion IPO Puts India’s Market Muscle to the Test
- Asia stocks rebound as SpaceX, Super Micro results lift chipmakers
- Australian data center operator NextDC's shares plunge 40% after it slashes earnings forecast
- Philip R. Lane: Euro liquidity lines and the international monetary system
- Australian AI data centre operator NextDC shares shed 44% on revenue delay
- Tesla supplier CATL shares plunge after disappointing Q3 results