
Enstructure Completes Acquisition of LOGISTEC's Marine Services Division, Creating One of North America's Largest Terminal and Logistics Networks
Source: PR Newswire
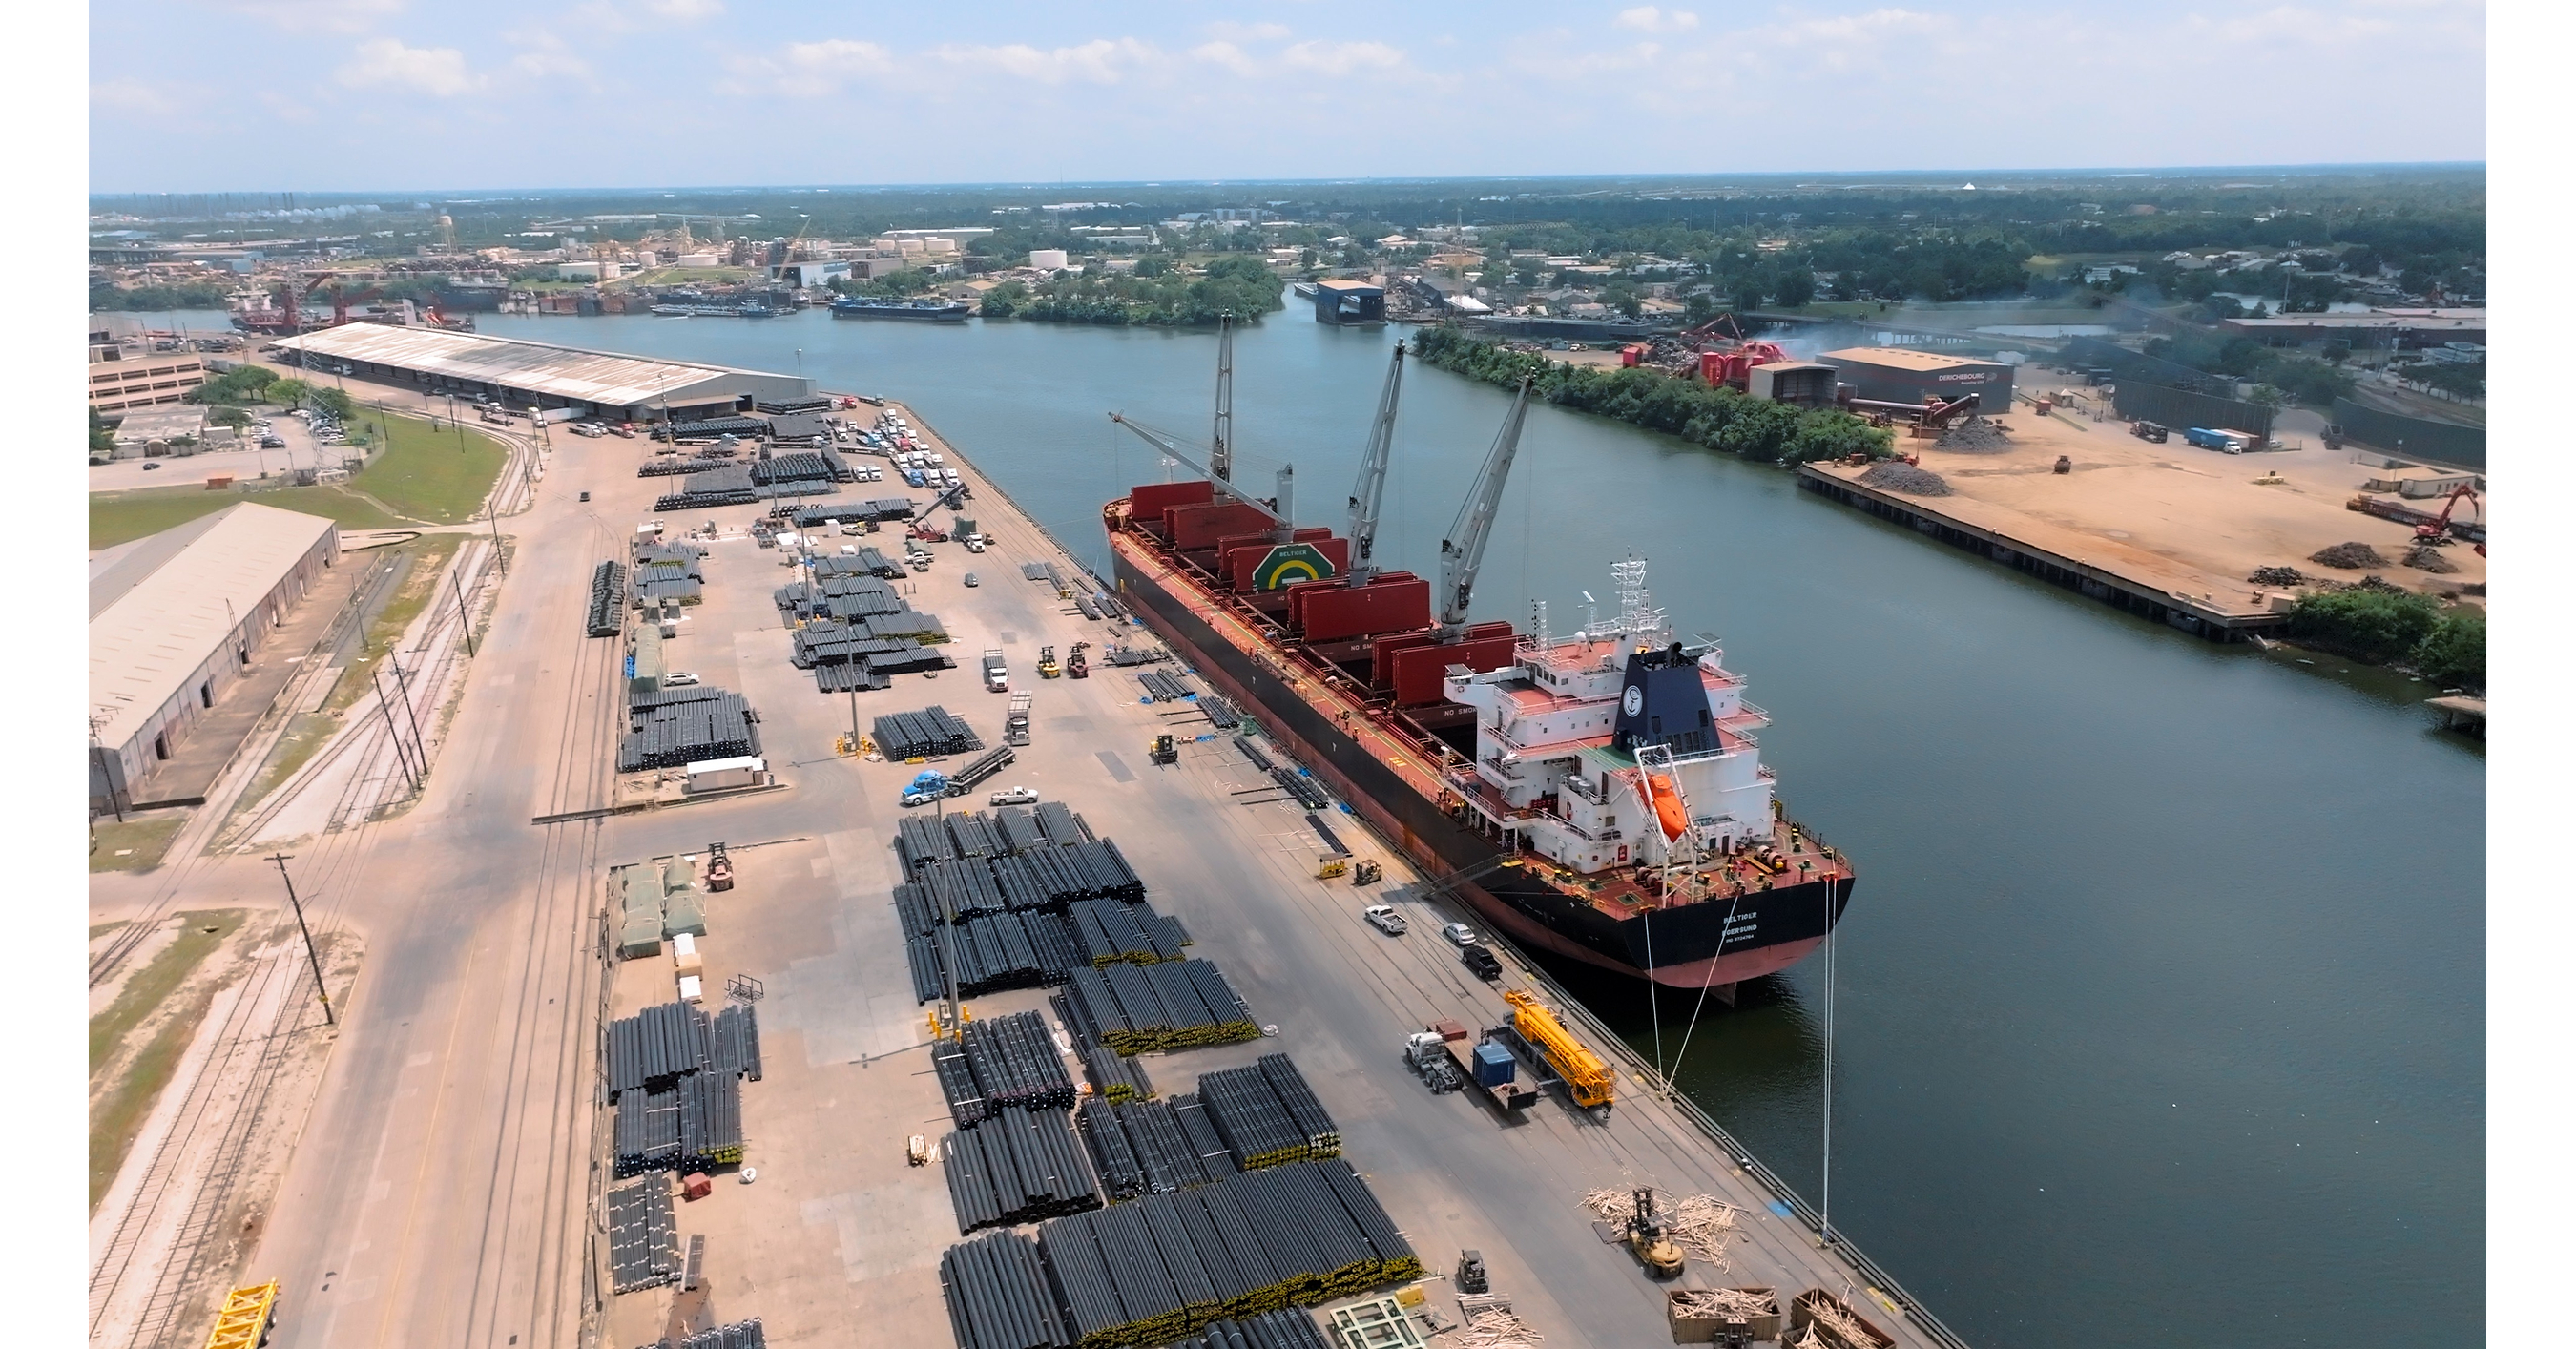
Enstructure completed its acquisition of LOGISTEC’s marine services division, creating a combined marine terminal and logistics network of 106 terminals across 30 states/provinces and ~6,000 employees. The expanded footprint spans 3,000+ waterfront acres, including ~12.5M sq. ft. of industrial warehousing, and supports ~70M tons of cargo annually, across multimodal services (stevedoring, cargo handling, warehousing, trucking). Financial terms were not disclosed, but the deal is positioned as a step-change in market access and supply-chain resilience for North American trade corridors.
Analysis
This is more a capital-allocation and network-pricing story than a near-term earnings catalyst. A larger, denser terminal footprint can raise switching costs for shippers that value reliability, which tends to favor integrated operators over fragmented local port assets and lower-service 3PLs. The second-order winner is the adjacent warehousing/trucking layer: once cargo is trapped inside a bigger network, the margin pool shifts toward storage, drayage, and multi-modal coordination rather than pure handling.
For BX, the direct public-market benefit is modest but real: it reinforces the investable thesis that infrastructure/private-credit capital can finance roll-ups of hard assets with durable cash flows. That said, the stock should not be expected to re-rate on the headline alone unless the deal translates into higher fee-related earnings or a visible path to realizations. The more important signal is that Blackstone’s capital stack is being used in an asset class where operating leverage and refinancing optionality can compound over 6-18 months.
The contrarian risk is execution, not demand: larger networks often look powerful on paper but can dilute discipline via labor complexity, capex creep, and slower customer response times. The thesis is falsified if post-close KPIs fail to show margin expansion or if leverage rises faster than throughput. Near term, there is likely no broad public-equity readthrough; the market may be overestimating how much listed transport names benefit from a private terminal consolidation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Small tactical long BX on weakness over the next 3-6 months; treat this as a quality-credit validation trade, not a high-conviction catalyst trade. Upside case is low-single-digit stock outperformance if infrastructure/private-credit fundraising and realizations remain strong.
- Relative-value watch: BX vs KKR for the next 1-2 quarters. Prefer BX only if subsequent disclosures show better infrastructure/credit fundraising or carry conversion; otherwise skip the pair.
- Do not force a short in transport/logistics equities immediately. Wait 1-2 quarters for post-close evidence on utilization, customer retention, and leverage before touching names like JBHT or CHRW.
- Set an alert on the combined company’s first post-close operating update: if margins or throughput do not improve and capex guidance rises, fade any bullish readthrough and reassess BX as well.
More News
- Major earnings reports are due next week, but strong results may not be enough to quell market fears
- Anthropic offers Blackstone double-digit yield in chip-financing deal, FT reports
- Iran-backed Houthis strike Yemen’s Aden: What that means
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Palantir patient data tech rejected by many NHS trusts in England
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More