
Inside and Out: Hampton Inn by Hilton South Plainfield-Piscataway Reveals it's All New Look
Source: PR Newswire
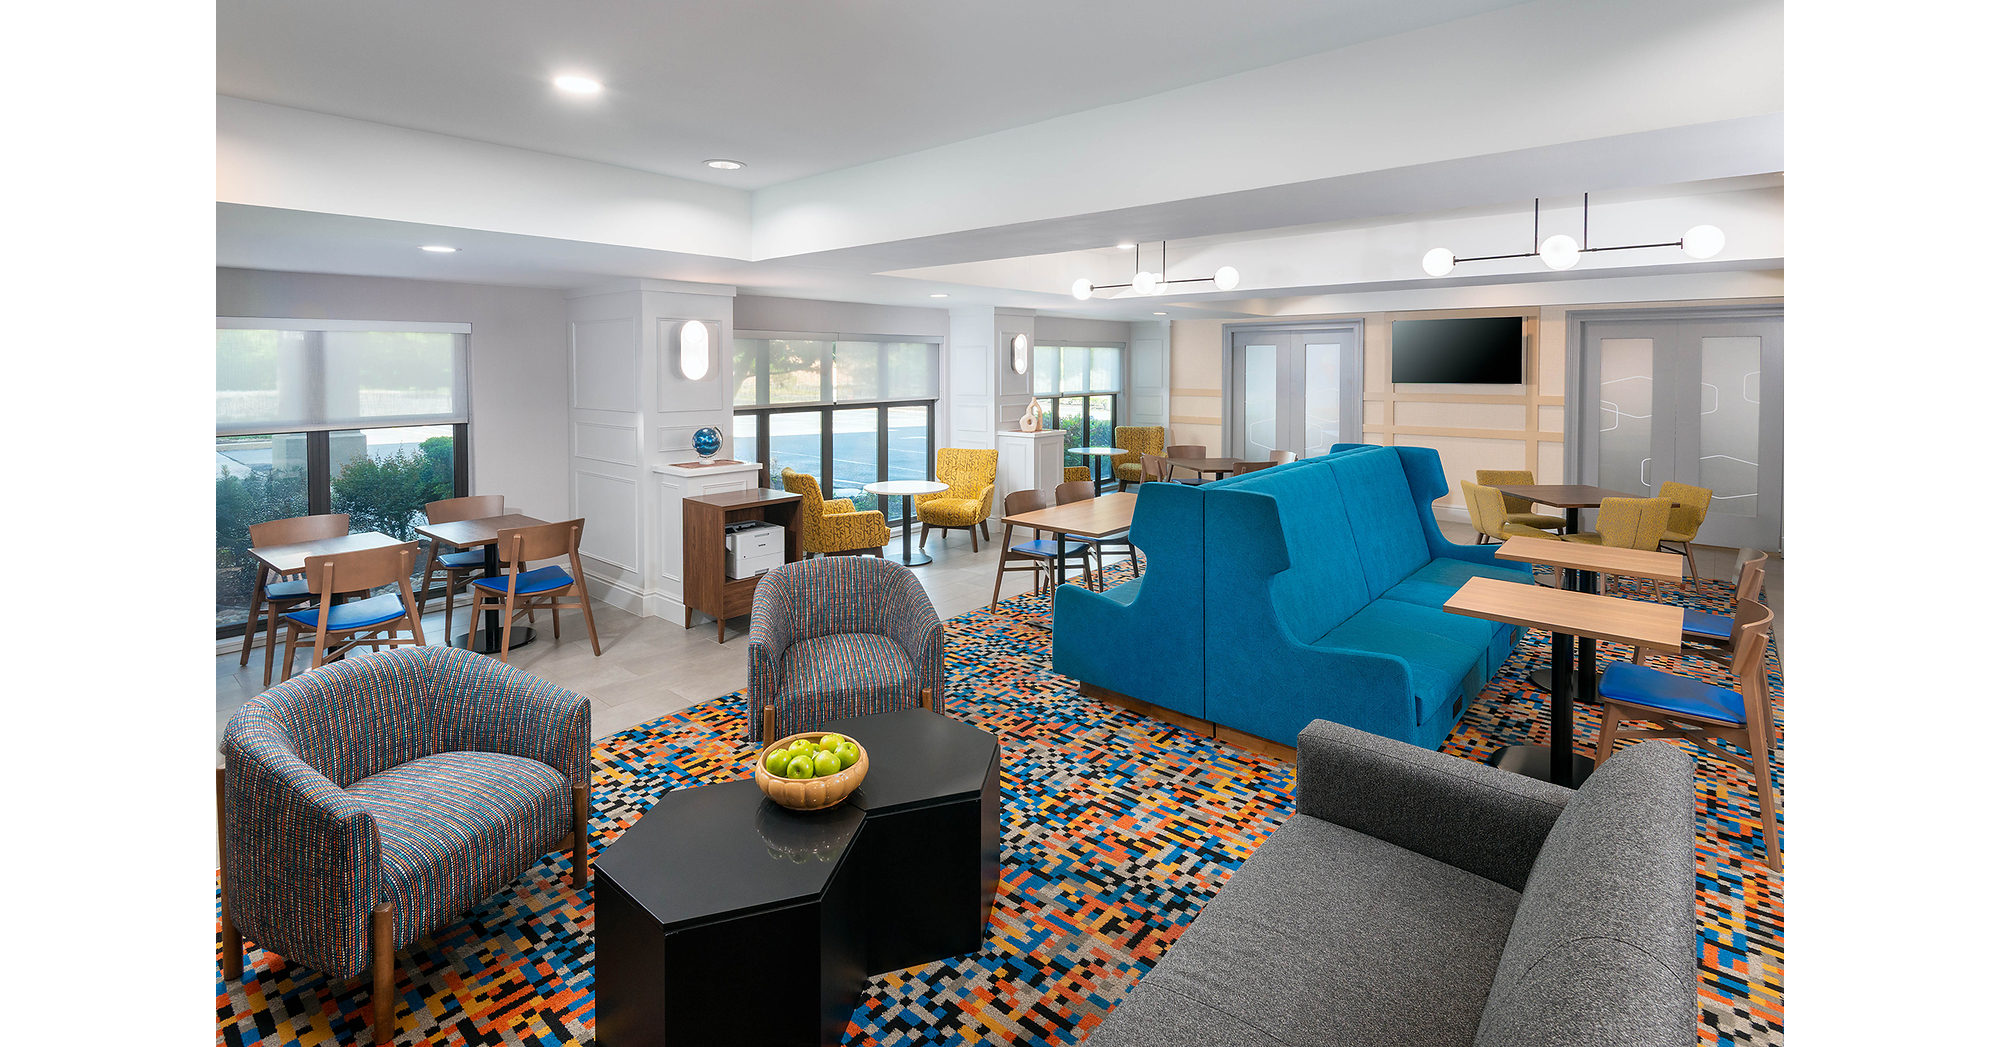
Buffalo Lodging Associates announced completion of a major renovation of the 5-story, 107-room Hampton Inn by Hilton South Plainfield-Piscataway, including fully remodeled guest rooms and upgrades to the lobby, fitness center, exterior, and meeting spaces. No financial figures, guidance, or performance metrics were provided, so the update is mainly an operational/product improvement intended to enhance the guest experience. Overall impact is likely limited to local demand and property-level competitiveness rather than broader market repricing.
Analysis
This is incrementally positive for the Hilton franchise ecosystem, but the economics are mostly captured by the owner/operator, not the brand. The mechanism matters: refreshed product tends to lift ADR and review scores before it lifts occupancy, so the near-term benefit is better rate integrity in a competitive midscale corridor rather than a step-change in demand.
The second-order read-through is competitive, not company-specific. Renovated select-service inventory can pull share from older independents and weaker suburban hotels that cannot finance similar capex, which over 1-3 quarters can compress spreads for nearby non-upgraded assets. For public equities, that modestly supports asset-light royalty models like HLT more than hotel owners with heavier maintenance burdens.
Contrarian view: a renovation press release can also be defensive, not confident. If management is spending to keep the box relevant, the payback depends on stable corporate travel and weekend event demand; if those soften, the capex simply delays margin pressure rather than creating it. The key falsifier is regional lodging data: if Northeast RevPAR and Hilton fee growth do not improve over the next 1-2 quarters, this should be treated as noise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- No direct trade in SCPAF on this item; the signal is too localized to justify capital deployment unless subsequent quarterly data show measurable ADR/RevPAR outperformance.
- Conditional long HLT on a pullback over the next 1-3 weeks if Hilton guidance or channel checks confirm stable Northeast business-travel demand; expect a 6-10% upside path over 3-6 months if system fee growth inflects.
- Pair: long HLT / short HST for a 1-2 quarter relative-value expression of brand-led fee growth versus hotel-owner capex burden; stop if HST prints stronger-than-expected RevPAR or HLT misses on net unit growth.
- Set an alert for NJ/NYC corridor lodging data and Hilton commentary next earnings cycle; if RevPAR decelerates or management signals softer group demand, fade any bullish read-through quickly.
More News
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- India calls JD Vance's comments about immigrants 'deeply offensive'
- The AI race may be decided by financing—not just better chips
- Why is Verizon stock sliding today?