
Civitas Closes $104 Million Senior Loan for 164-Unit Class A Multifamily Community in Colorado's Vail Valley
Source: PR Newswire
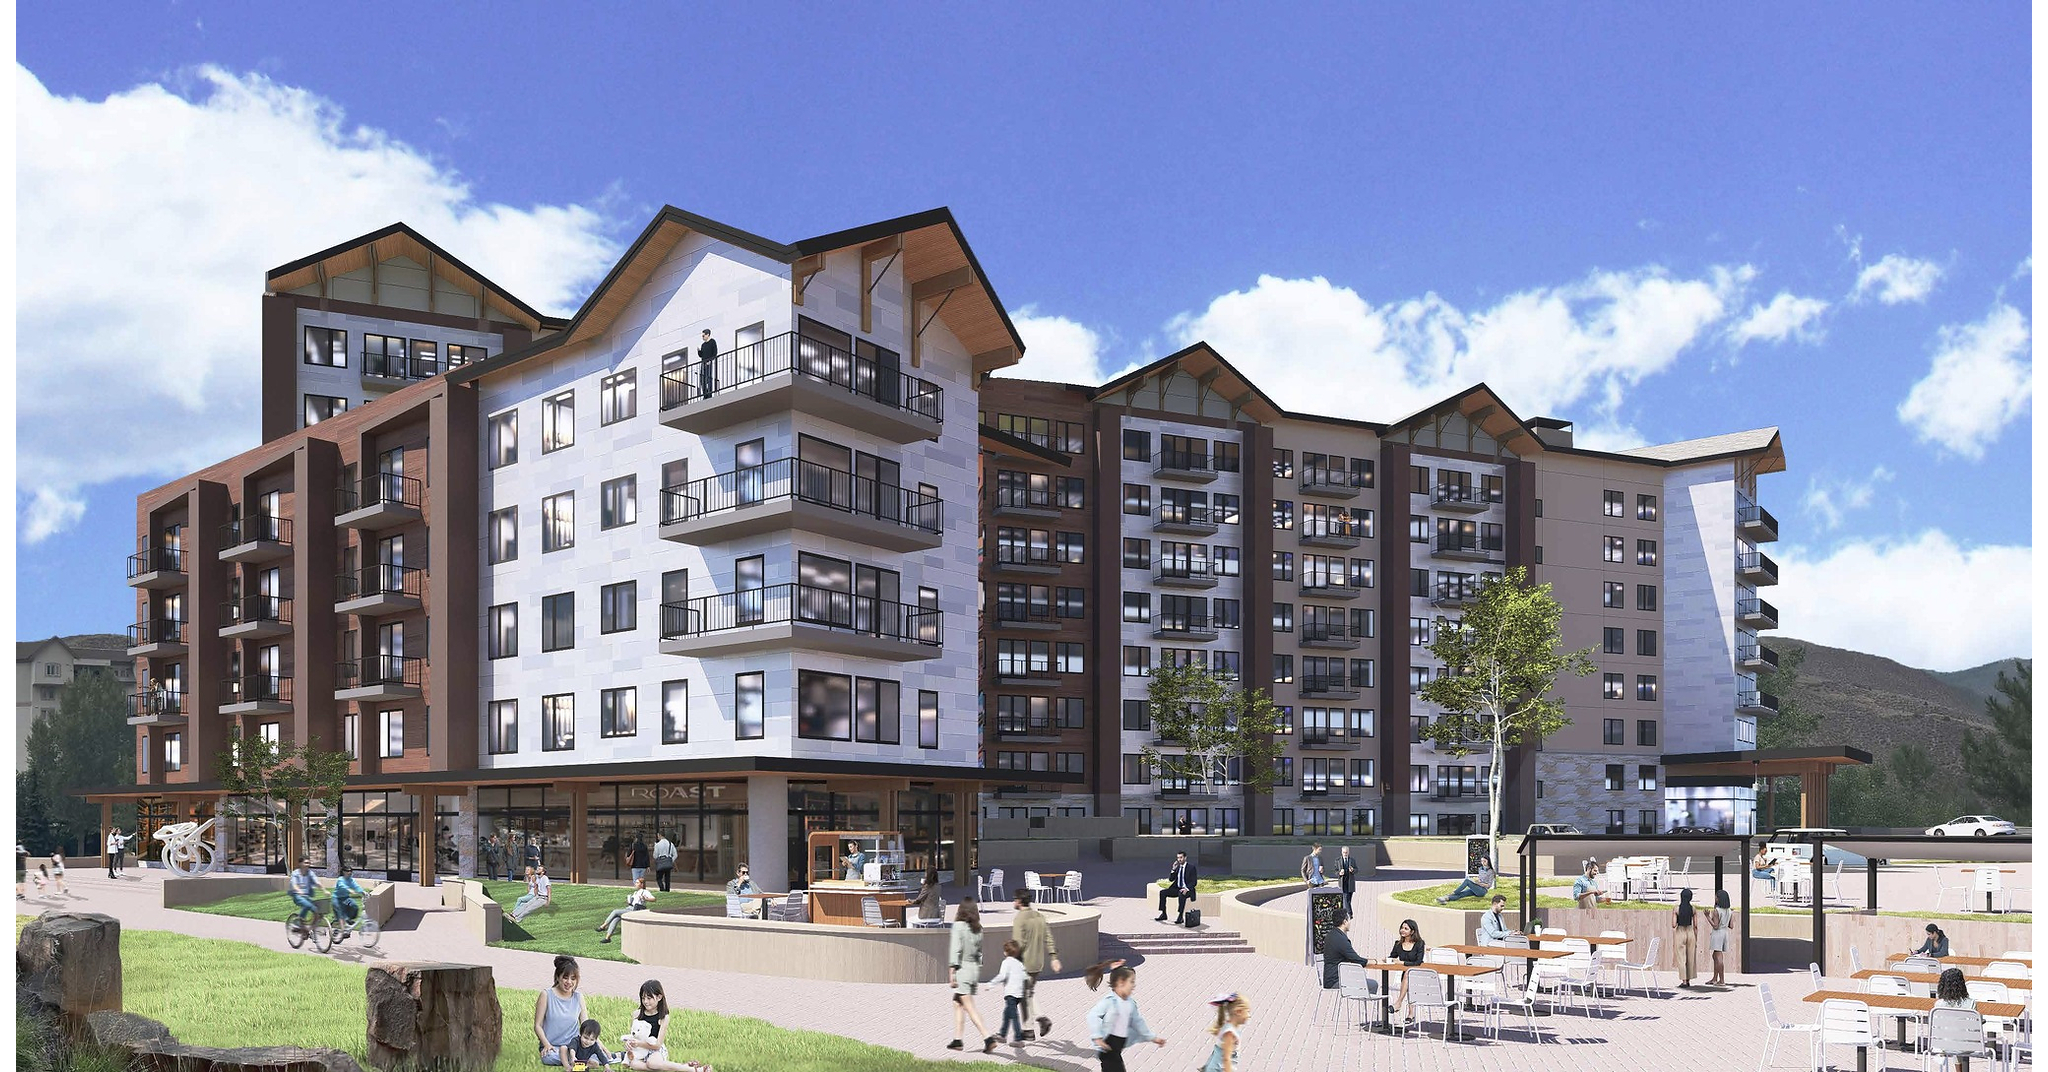
Civitas Capital Group closed a $104 million senior construction loan to finance The Summit, a 164-unit Class A multifamily project in Avon, Colorado, with construction slated to begin in Q3 2026. The deal leverages rural EB-5 TEA status to enable a reduced $800,000 investment level and priority processing, while the Town of Avon will contribute up to $11.84 million in public financing. With 144 market-rate and 20 affordable units (plus ~5,000 sq. ft. of commercial space), the news is credit/real-estate positive for Civitas’ EB-5 platform and signals strong local housing demand.
Analysis
The investable read-through is not the loan itself; it is the signal that resort-town housing remains financeable only with subsidy and immigration-linked capital. That usually supports incumbent labor-intensive operators because each incremental unit of workforce housing reduces turnover, wage escalation, and seasonal staffing risk — a margin tailwind that shows up with a lag, not at announcement.
For public comps, the nearest beneficiary is MTN: better employee housing in the Vail corridor should modestly improve resort operating leverage over 6-18 months if it helps keep lifts, hotels, and ancillary services fully staffed. The counterpoint is that new supply in a chronically tight market is more likely to cap rent growth for existing local landlords than to reset the market; the project is too small to change the regional housing narrative, but it can validate a broader pipeline.
The real risk is execution and policy, not demand. EB-5 projects are vulnerable to construction delays, cost overruns, and USCIS processing hiccups; if any of those worsen, the cash-flow benefit to local employers gets pushed out beyond the next ski season. The consensus may be overestimating immediacy: this is a structural, incremental positive for mountain operators, not a near-term catalyst for a re-rating.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.30
Key Decisions for Investors
- MTN: bias modestly long on pullbacks over the next 3-6 months; use this as a slow-burn margin-support thesis, not a headline trade. Risk/reward is favorable only if management continues to cite labor retention as a constraint.
- MTN Jan-2027 call spread as a low-cost way to express improving operating leverage from housing availability; size small because the project impact is incremental and timing uncertain.
- Do not short local mountain-town multifamily/REIT proxies on this announcement alone; 164 units in a supply-starved market is insufficient to derail rent growth, so the downside from new supply is likely overstated.
- Set an alert on EB-5 policy/USCIS processing times: if rural priority processing is slowed or visa reserve rules change, reprice the entire funding model and reduce any MTN-related thesis.
- If you want a relative-value expression, long MTN vs. a broad discretionary basket (e.g., XLY) only after the next earnings call confirms staffing/turnover relief; otherwise the trade is too indirect.
More News
- Nvidia and Visa Have Little in Common. I'd Split $1,000 Between Them and Hold Until 2035.
- The IEA wants to empty its oil reserves faster. A federal watchdog says the US isn’t ready for what comes next
- Take Five: Bangkok blues
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- UK Chancellor Healey Must Find £35B Ahead of Budget, IFS Warns
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Family Offices: A Stack by Decision Type
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs