
Lennar Unveils The Farm, a New Community Rooted in the Inland Empire's Outdoor Lifestyle
Source: PR Newswire
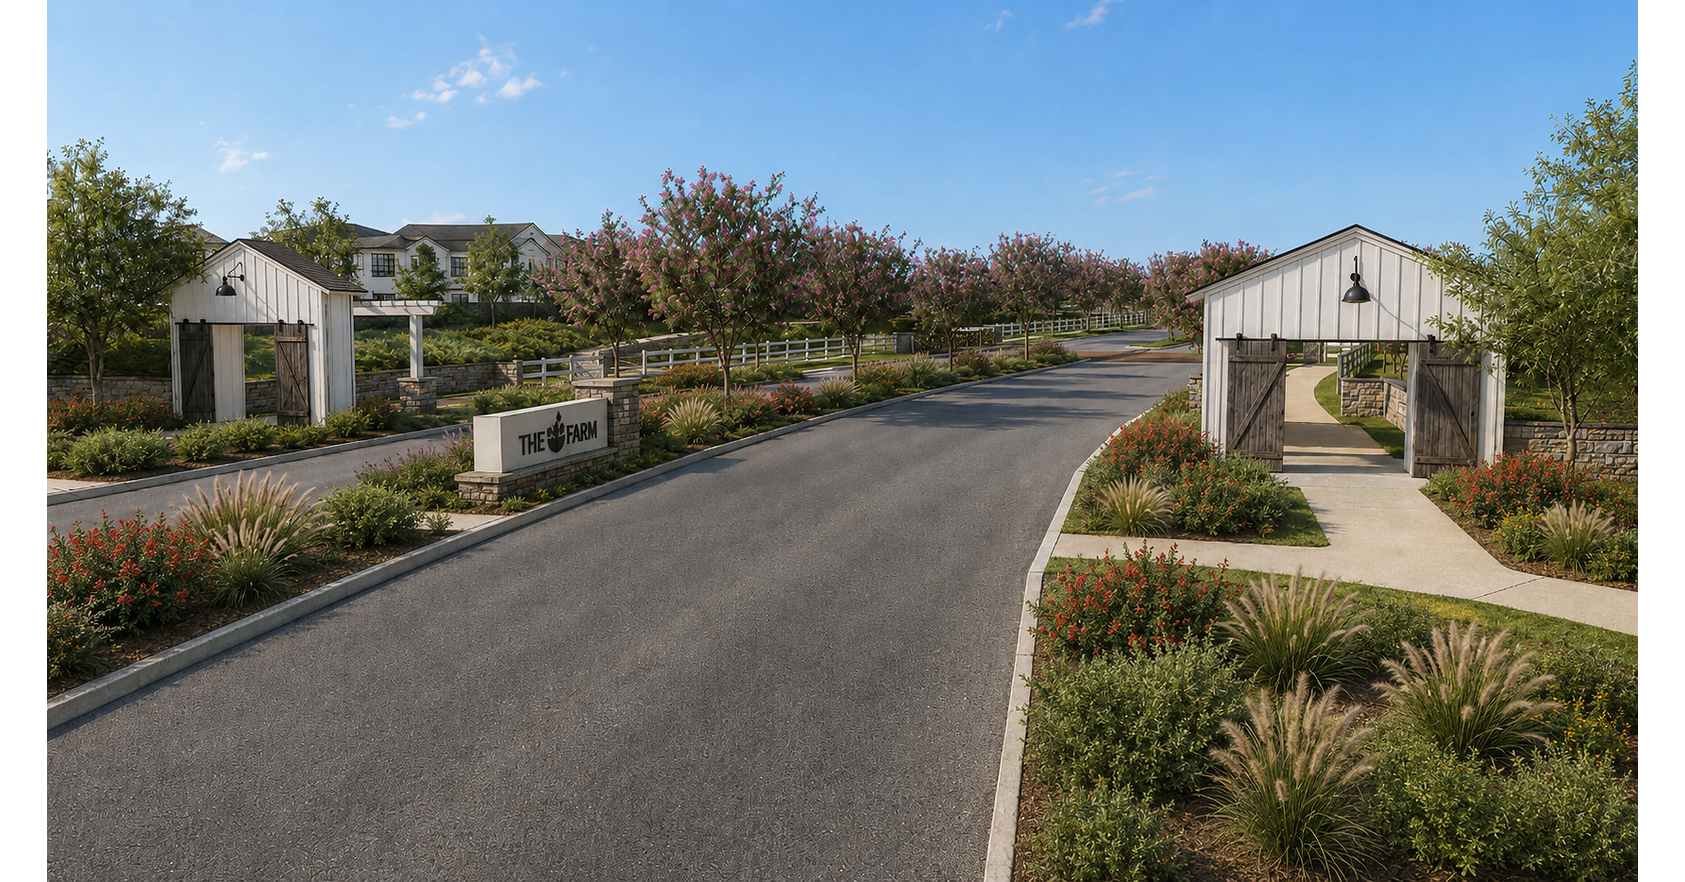
Lennar launched The Farm, a new Jurupa Valley, California community with 16 condominium and single-family floorplans priced from the high $400,000s. Homes range from 845 to 2,869 square feet and include Lennar's Everything's Included features, while the development offers resort-style amenities and access to key Inland Empire highways. The announcement is a routine product/community launch with limited expected impact on Lennar's shares.
Analysis
This is not independently material to LEN earnings absent community count, lot-control economics, absorption pace, and incentive levels; it should not alter estimates or justify a directional position. The relevant signal is strategic: LEN is broadening its product ladder within a rate-sensitive Southern California submarket, which can support capture rates through its mortgage affiliate but may require heavier buydowns if resale inventory or competing new-build supply rises. Near-term equity sensitivity remains overwhelmingly tied to mortgage rates, cancellation trends, gross-margin guidance, and the company’s ability to maintain sales pace without incremental concessions.
Competitive pressure is most relevant for KBH, DHI and local private builders with overlapping Inland Empire buyer cohorts. LEN’s scale can convert amenity spending and included features into a sales tool, but that advantage becomes margin-dilutive if competitors match incentives rather than price; the second-order read-through would be weaker land residual values and slower lot monetization across the region. Over 6-18 months, California affordability constraints favor builders with lower-cost product formats and captive financing, but also increase exposure to payment-shock demand elasticity if mortgage rates remain elevated.
Consensus may overread any new-community announcement as evidence of incremental volume rather than a normal deployment of existing land inventory. The more useful catalyst is the next earnings release: sustained order growth alongside stable gross margin would validate pricing power, while declining margin or a rising incentive rate would show that apparent product differentiation is being funded by concessions. Falsify a constructive LEN view if management reduces community-level absorption expectations, guides to materially lower gross margin, or mortgage rates rise enough to weaken monthly-payment affordability.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release; treat it as an operational watch item until LEN discloses community count, expected deliveries, sales pace, and incentive/buydown assumptions.
- For a 1-3 month housing expression, prefer a modest long LEN / short KBH pair only if LEN’s next order update shows stable gross margin and stronger California absorption; the thesis is LEN’s financing and scale advantage, not this project. Exit if LEN’s gross-margin guidance deteriorates or the pair underperforms by 8-10%.
- Maintain a rates trigger rather than chase housing-beta: a sustained decline in mortgage rates would improve payment affordability and favor LEN, DHI and XHB; a renewed rate backup should shift the bias toward reducing builder exposure before cancellation and incentive data weaken.
- Monitor KBH and DHI regional incentives and available-inventory disclosures over the next two quarters. Broad-based concession increases would be a negative read-through for LEN’s margin, even if unit orders initially appear resilient.
More News
- Lennar earnings outlook: two consecutive misses and a stock near multi-year lows
- Here's what 5% bond yields mean for the stock market — and which stocks to buy
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Americans' incomes rose and poverty fell in 2025, Census Bureau says
- Factbox-Private equity, foreign investors fuel Aussie M&A activity in 2026
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid