
Skylight Expands Credit Facility to $75 Million to Help Families Share the Load Through Every Stage of Life
Source: PR Newswire
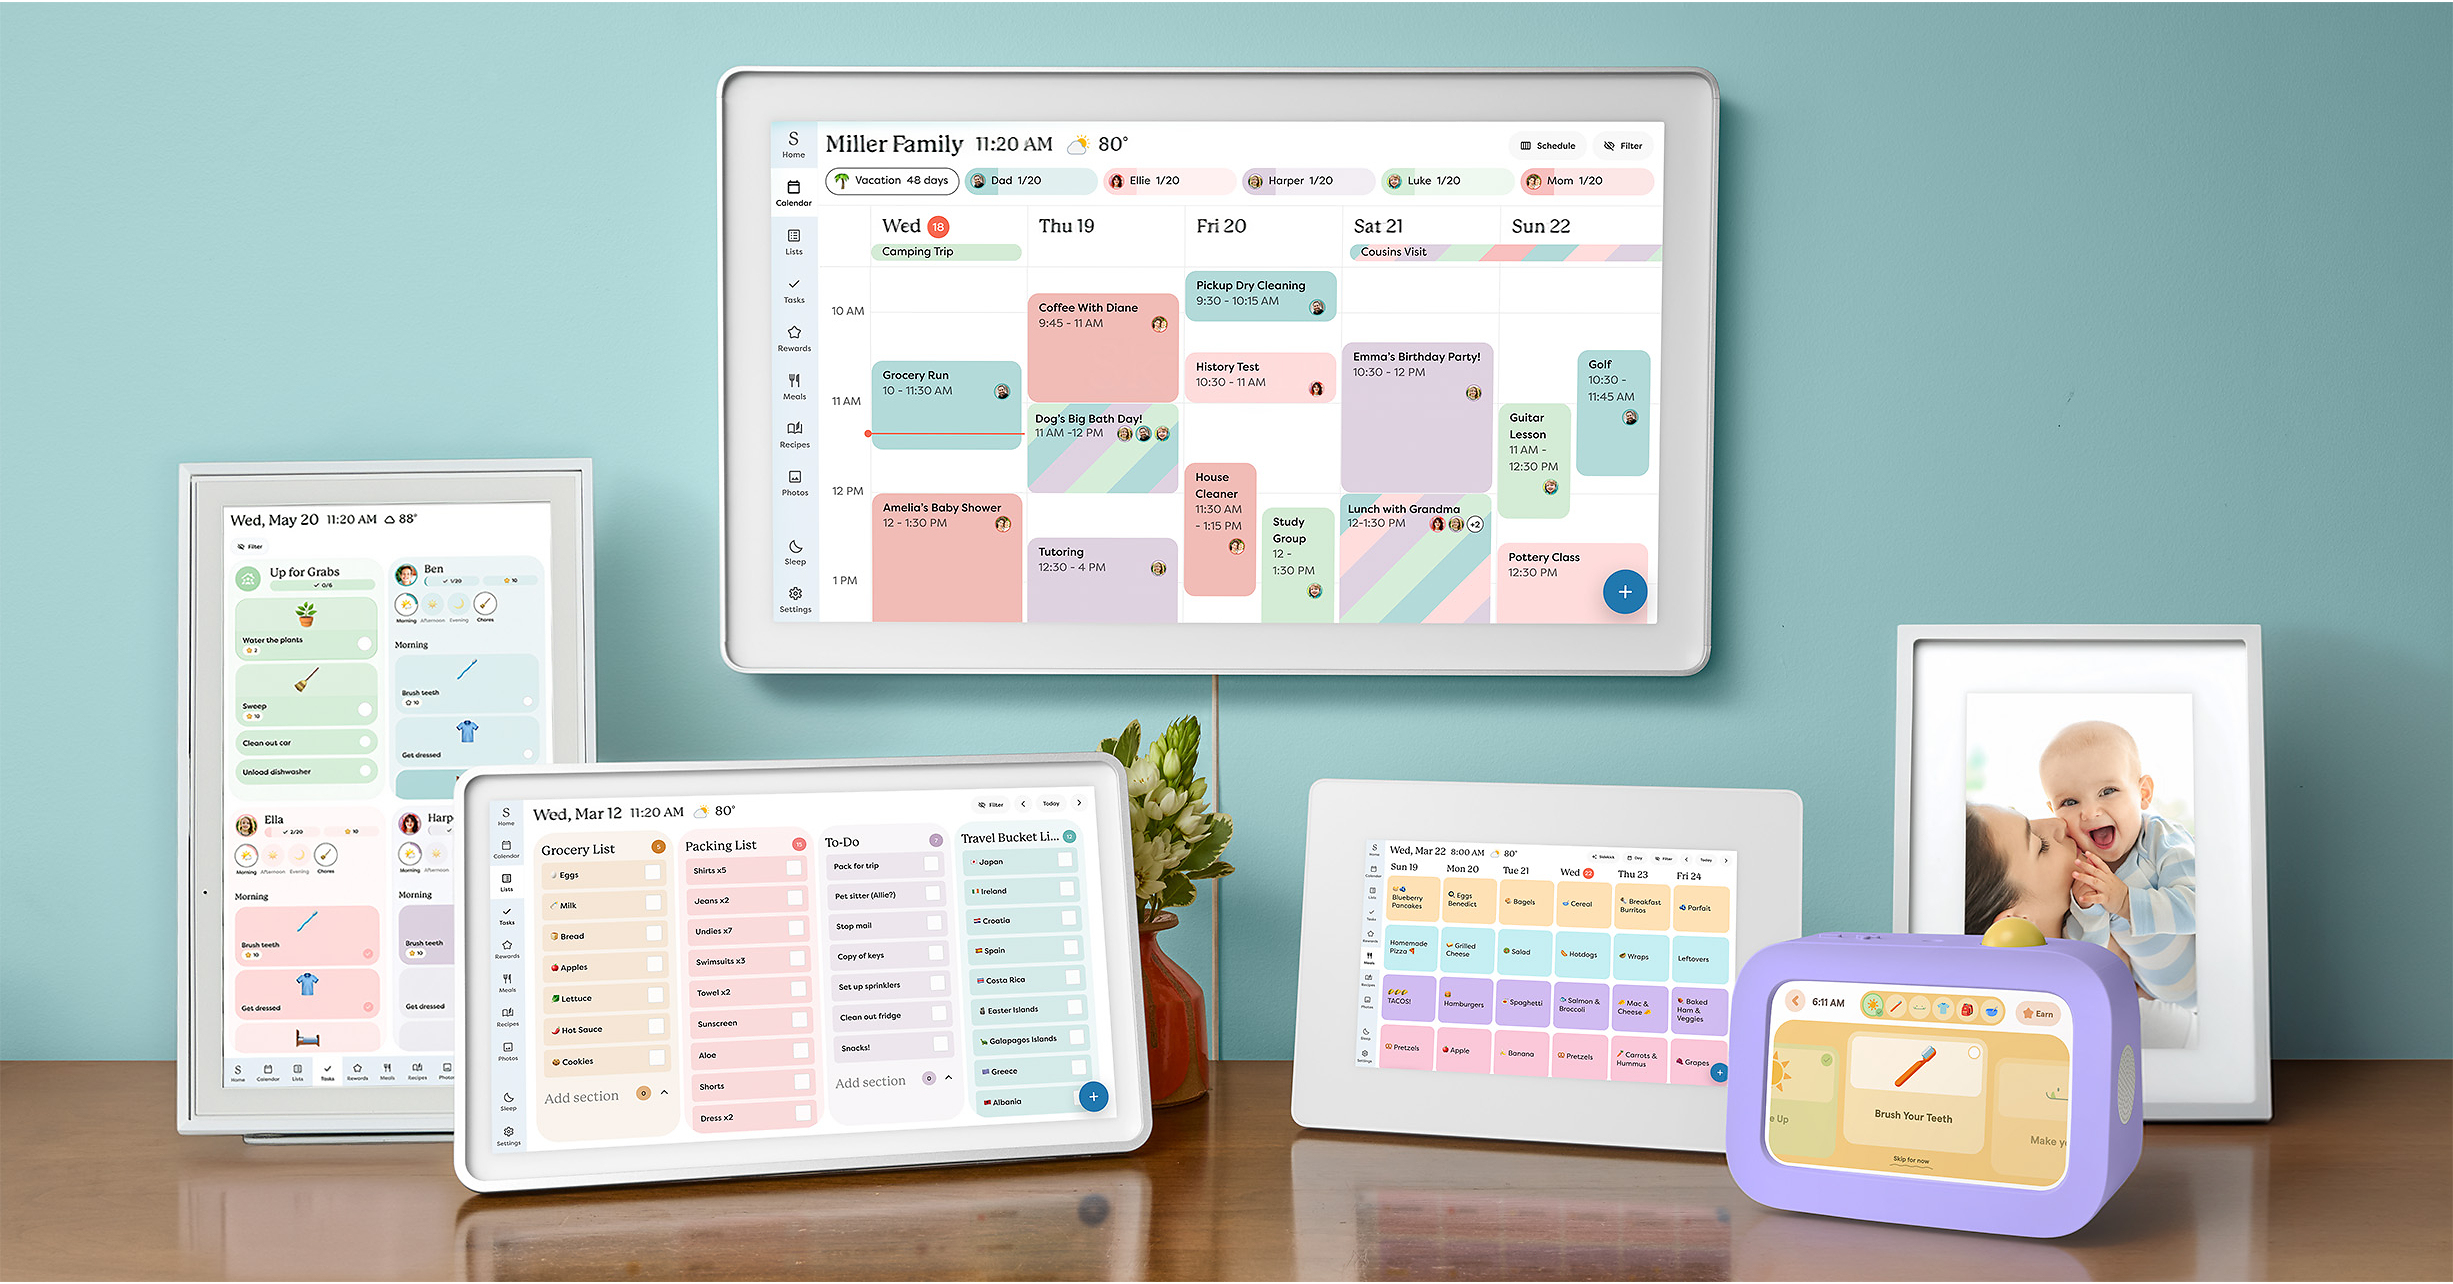
Skylight expanded its credit facility by $25 million to $75 million, funded by SG Credit Partners and Wingspire Capital, to broaden its product range and distribution. The bootstrapped family-technology company said it doubled in its largest year yet and now reaches more than 12 million customers, including 1.7 million Skylight Calendar households. Funding will support products including Skylight Buddy, which sold out within a week of launch, and further development of its AI-powered Skylight Assistant.
Analysis
This is not a meaningful earnings catalyst for either OBDC or OWL: a single lower-middle-market credit exposure is immaterial against their diversified capital bases, and the release provides no pricing, advance rate, collateral, maturity, or hold-versus-syndicate information. The relevant signal is qualitative: lenders were willing to extend additional capacity to a consumer hardware/platform business, suggesting acceptable recent underwriting performance and collateral availability rather than proving durable profitability or demand.
For OBDC, the second-order issue is credit quality, not originations. Consumer-device growth typically requires inventory financing and customer-acquisition spend; if sell-through weakens after channel expansion, receivables and inventory recoveries can deteriorate quickly, especially where AI-product investment raises cash burn before recurring revenue is established. Any benefit to OBDC depends on Wingspire retaining economically meaningful exposure and on loan yields exceeding incremental funding costs, neither of which is disclosed.
Over the next 1-3 months, the news should have negligible standalone price impact. Over 6-18 months, a broader pattern of private-credit lenders funding consumer hardware companies at expanding facilities would be modestly supportive for BDC deployment, but could also signal late-cycle underwriting drift if leverage is rising faster than verified cash flow. The contrarian read is that facility expansion is often interpreted as validation; it can equally reflect a lender protecting an existing relationship while increasing collateral controls.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No standalone position in OBDC or OWL on this announcement; expected fundamental impact is below the threshold for a tradable earnings revision.
- Maintain OBDC on a credit-watch list: review the next portfolio disclosure for Wingspire exposure, non-accrual migration, weighted-average yield, and consumer/retail concentration. A rise in non-accruals or a >50 bp sequential decline in portfolio yield would invalidate any constructive read-through.
- For existing OBDC holders, retain only if the discount to NAV compensates for consumer-credit exposure; reduce on a sustained NAV premium if quarterly credit marks weaken, since BDC multiple compression can exceed the direct loss from a small impaired position.
- Use OWL rather than OBDC for a broad private-credit fundraising thesis only after fee-related earnings or permanent-capital inflows accelerate; this facility alone does not establish incremental management-fee revenue or realizable AUM growth.
More News
- AI infra firm Accelevation valued at $3.9 billion as shares fall in Nasdaq debut
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Asian stocks dip, bonds in focus after torrid September
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- California Gov. Gavin Newsom bans AI 'robo bosses' in landmark state law, reversing his earlier veto
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data