
Zoomlion renforce son ancrage en Europe grâce à un renforcement de la collaboration en matière de services, de production et de technologie
Source: PR Newswire
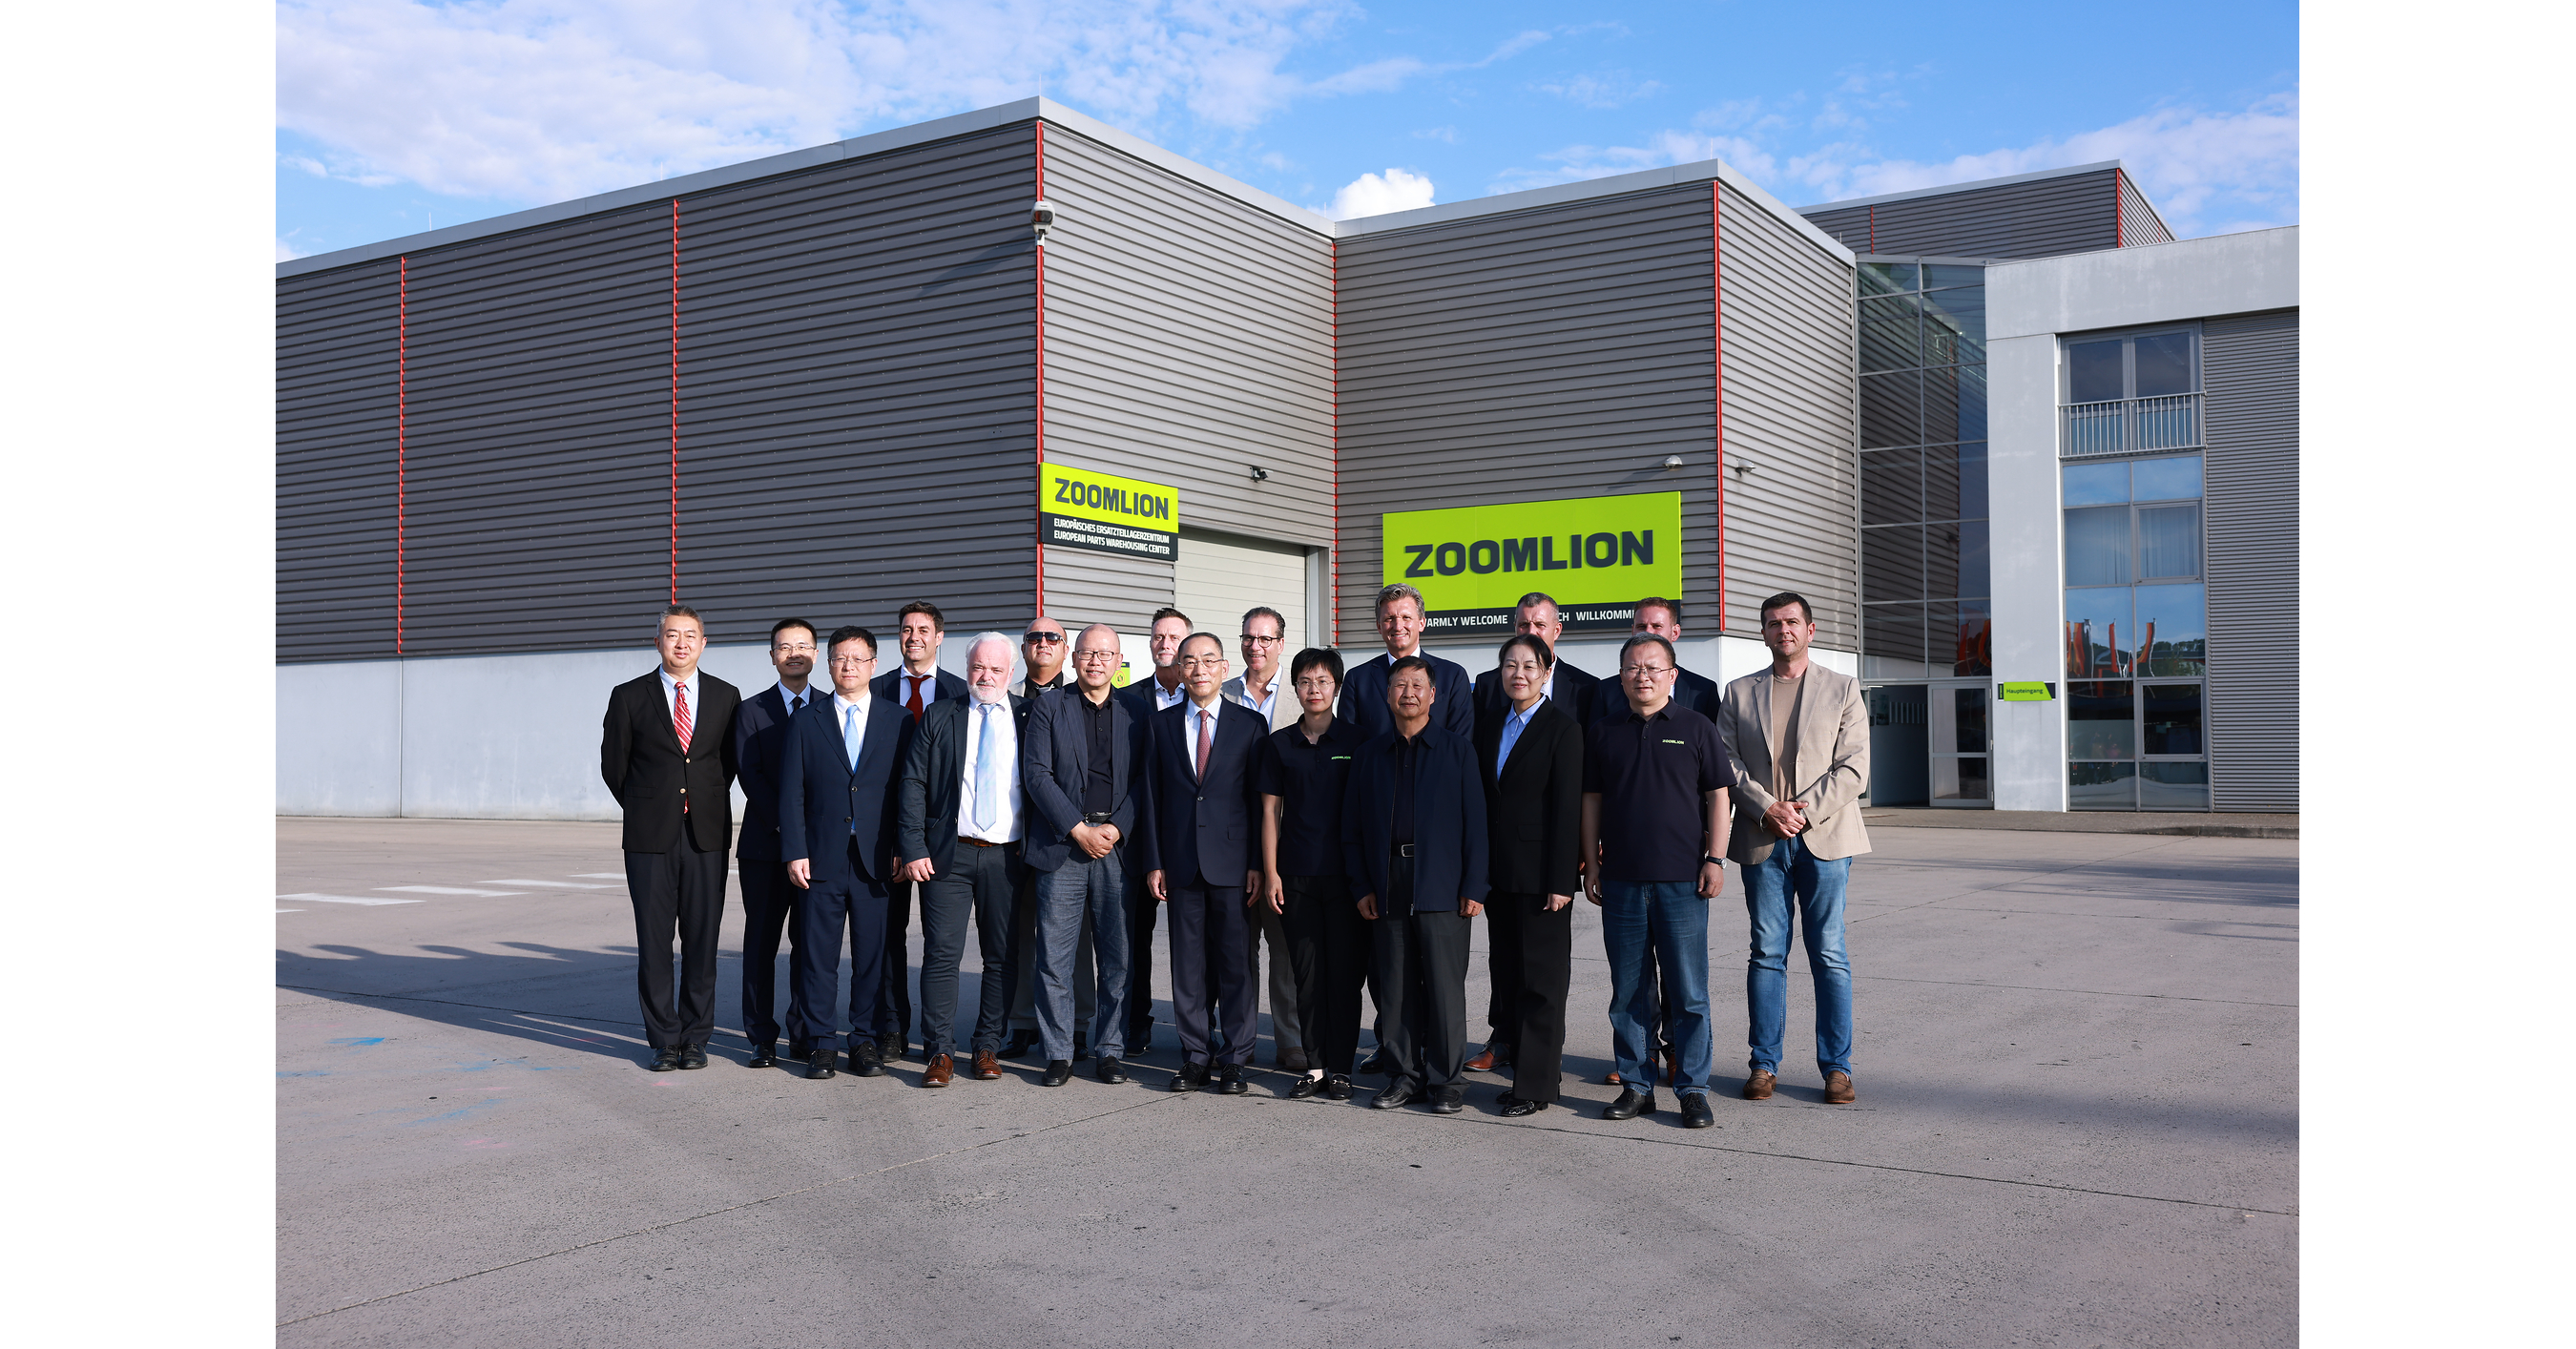
Zoomlion highlighted its Europe localization push following a 19 août meeting with partners in Germany, focusing on expanded local sales, manufacturing, spare-parts availability, and faster after-sales service responsiveness. The company plans to roll out a digital services platform to automatically assign and track maintenance interventions, and it intends to further support its German subsidiary m-tec, including R&D collaboration tied to 3D-printing applications. The update is operational and strategy-oriented, likely incremental for markets rather than immediately price-moving.
Analysis
This is more credible as a long-duration competitive positioning update than a near-term earnings event. In construction equipment, Europe is one of the few geographies where aftermarket density and parts uptime can still decide share; a stronger local service network lowers the biggest barrier for a non-Western OEM: perceived execution risk, not product specs. That makes the strategic threat less about headline machine sales and more about incremental leakage in spare parts, service revenue, and fleet replacement decisions for entrenched incumbents.
The second-order effect is on mid-tier European rivals and distributors rather than CAT/Deere at the top end. If Zoomlion can really shorten repair times and localize assembly, it can compress the moat of regional players in attachments, lifting platforms, and mortar/materials-handling niches where customer switching is already price-sensitive. The flip side is that this likely pressures margins before it drives meaningful volume: local plants, inventory buffers, and digital service infrastructure are capital intensive, so the equity story only improves if European revenue growth outpaces the fixed-cost buildout over the next 4-6 quarters.
Contrarian take: the market may be overestimating how quickly brand trust converts into share in Europe. Construction customers care about uptime and residual values, and those take multiple replacement cycles to reprice. The more important catalyst is not this announcement but the next two earnings prints: if Europe mix rises while gross margin stays intact, the thesis becomes real; if not, this reads as a defensive PR campaign amid slowing China demand and export pressure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No immediate chase in ZLIOY: treat this as a 6-18 month share-gain watch item, not a day-1 catalyst; only add on evidence of European revenue acceleration and stable gross margin in the next 2 earnings releases.
- Use a pair trade if you want to express the thesis: long ZLIOY / short a Europe-exposed equipment incumbent basket (e.g., CETV/CONG? if unavailable, use CAT or Volvo CE proxies via CAT/Volvo ADRs) only if Zoomlion prints outsized Europe order growth; otherwise the signal is too weak.
- Watch European aftermarket names and distributors for pressure rather than pure OEMs: if Zoomlion’s service/parts network scales, the first earnings leakage should show up in spare-parts intensity and service margins at regional peers over the next 2-4 quarters.
- Set a falsifier: if Europe revenue does not accelerate over the next 6-12 months or if localization capex depresses margins, assume this is strategic noise and fade any enthusiasm toward ZLIOY.
More News
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- China’s National Team Signals Return With Heavy ETF Inflows
- FDA approves Enspryng for thyroid eye disease treatment