
Bitmine Immersion Technologies (BMNR) annuncia che le partecipazioni in ETH hanno raggiunto 6,03 milioni di token e che il valore complessivo delle disponibilità in criptovalute, liquidità e titoli negoziabili ammonta a 16,2 miliardi di dollari
Source: PR Newswire
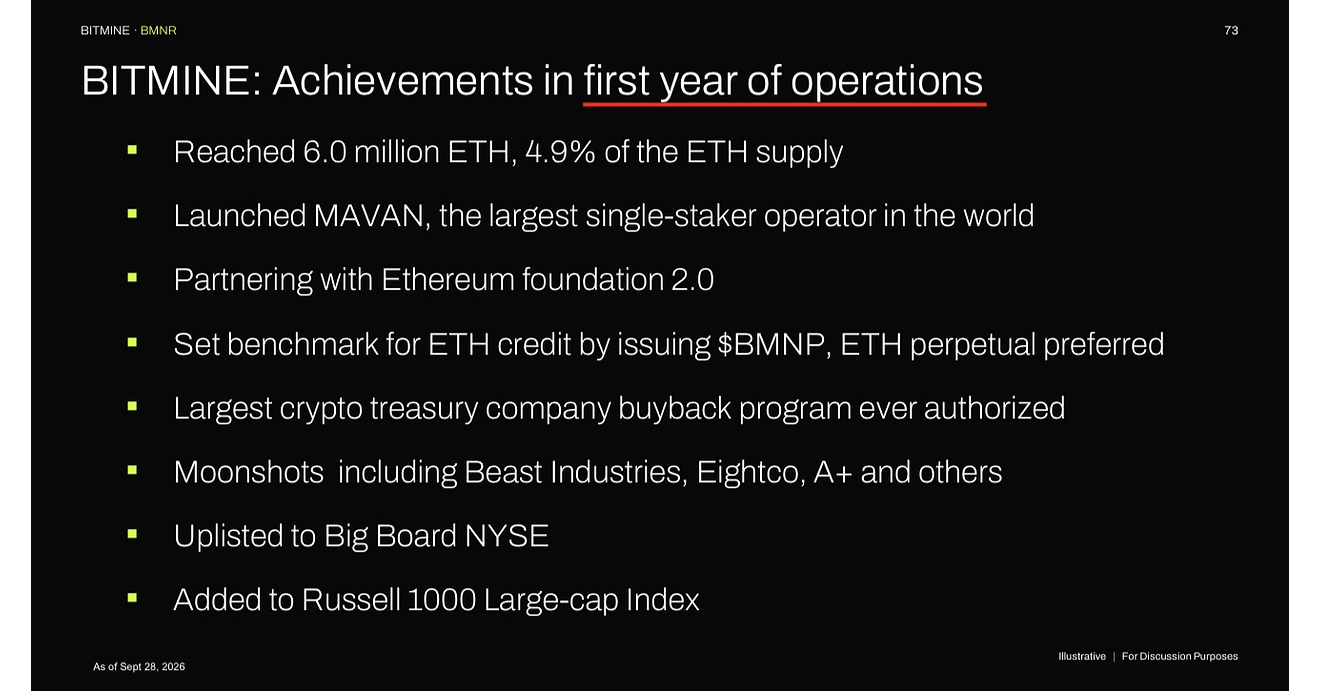
Bitmine reported total crypto, cash, marketable securities and “moonshot” investments of $16.2 billion as of October 11, 2026, including 6,028,946 ETH valued at $2,544 each—4.9% of ETH supply—and 5,067,309 ETH staked, worth $12.9 billion. The company said it bought 12,532 ETH in the latest week and is at 99% of its 5%-of-supply accumulation target; management estimates staking revenue of $336 million annualized currently and about $400 million at full staking, based on a recent seven-day yield. Chair Thomas Lee also said BMNP had gained 24% since issuance, while noting that crypto-market and staking outlooks are forward-looking and subject to significant risks.
Analysis
The key question is whether BMNR’s equity value reflects ETH exposure at a premium to liquid NAV, and whether that premium can survive once the “5%” accumulation milestone is reached. Completion may deliver a near-term headline catalyst, but it also risks removing the recurring purchase narrative that has supported the stock. A large ETH treasury is not automatically a durable moat: the concentration can amplify drawdowns, and staking most holdings may make operational, custody, or protocol incidents more consequential even if the tokens remain economically owned.
The claimed staking run-rate should not be capitalized as stable earnings. It is based on a short measurement window and variable protocol rewards; external MAVAN customers, fee economics, uptime, and slashing exposure are not established here. If MAVAN wins institutional business, it could build a less price-dependent revenue stream and compete with service providers such as Galaxy Digital; evidence of third-party customers matters more than internal staking scale. BMNP’s perpetual dividend is a separate capital-stack risk: lower ETH prices or a wider funding market could raise the effective cost of capital and increase pressure on common equity, irrespective of staking performance.
The contrarian risk is that “treasuries permanently remove supply” is not a one-way mechanism. Falling asset prices, financing needs, or changing strategy can turn treasury holders into sellers. The release is issuer-authored; validate holdings, encumbrances, dilution, dividend coverage, and staking returns in filings. ORBS’s disclosed relationship is an investment exposure, not evidence of material operating or earnings linkage. Over 1–3 months, watch the accumulation milestone, equity premium/discount to liquid NAV, and capital raises; over 6–18 months, the test is whether external staking revenue offsets crypto-cycle dependence.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Do not chase BMNR solely on the milestone or management’s bull-case framing. Before taking a view, calculate fully diluted liquid NAV per share, including preferred claims, and compare it with BMNR’s market price; missing share-count, liability, and encumbrance detail is a watch item.
- Conditional relative-value setup: if BMNR’s premium to liquid NAV expands materially while ETH exposure is unchanged, consider short BMNR against long ETH to isolate premium compression. Exit or reassess if verified third-party MAVAN revenue grows or the premium is supported by improving per-share NAV; no entry until the premium and borrow are checked.
- Treat BMNP separately from BMNR: monitor dividend coverage, trading price versus par, and any financing or dividend disclosures. A sustained deterioration in coverage or widening yield spread would challenge the preferred-equity stability narrative.
- Falsifiers and catalysts: verified sustained external MAVAN fees would weaken the treasury-only thesis; material share issuance, reduced ETH purchases, staking disruption, or a sharp ETH drawdown would strengthen it. Track SEC filings and ETH holdings rather than relying on annualized short-window reward claims.
More News
- Why is Strategy stock sliding today?
- Why is Samsung Electronics stock plunging today?
- SK Hynix plunges 8% amid Asia tech rout as Fed rate hike fears, AI funding worries mount
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'