
Laboratoires Pierre Fabre Appoints Nicolas Zombré CEO of U.S. Dermocosmetics Business, Signaling Next Phase of Growth
Source: PR Newswire
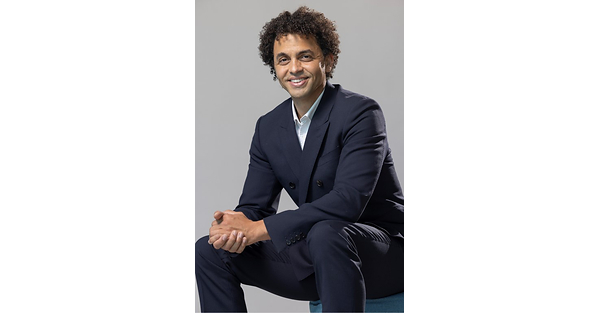
Laboratoires Pierre Fabre appointed Nicolas Zombré as CEO of its U.S. dermocosmetics operations to scale brands including Avène, René Furterer and Klorane. The company highlighted Avène’s double-digit U.S. year-over-year growth, with Cicalfate+ Restorative Protective Cream up +32%, supported by momentum with major retail partners (Amazon, CVS, Target, Ulta, Walgreens, and Walmart). R&D and investment positioning is ongoing, with this management change framed as a step toward strengthening Pierre Fabre’s U.S. market footprint.
Analysis
This reads more like a distribution signal than a fundamental earnings event. In prestige/dermocosmetics, the retailer wins are driven by repeat purchase, search intent, and replenishment cadence, which structurally favors AMZN and WMT over slower-moving physical chains if the brand truly scales in the U.S. CVS and TGT still benefit from incremental basket lift, but they are also the most exposed to promotional funding and vendor slotting economics, so the margin capture may be modest even if unit growth is strong.
The key catalyst is third-party proof over the next 1-3 months: scanner data, search/share-of-voice, review velocity, and beauty-category comps at the named retailers. If the growth is real, it should show up first in online conversion and repeat rates, then in retailer earnings a quarter or two later; if not, this is just an assortment story that fades. The downside tail is that dermocosmetics often requires expensive education and paid media in the U.S., so margin-accretive growth can quickly become trade-spend intensive.
Contrarian view: the market may overestimate the portability of a strong European pharmacy brand into the U.S. without a step-up in marketing and dermatologist endorsement. The biggest second-order loser is not necessarily a named retailer but adjacent skincare labels competing for the same shelf space and search keywords; for listed names, ULTA is the most vulnerable if the brand’s pull is more utilitarian than prestige. Falsifiers: weak Amazon/Walmart sell-through, no uplift in beauty comps, or evidence that launch support is margin-dilutive rather than self-funding.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade; treat this as a watch item until 4-8 weeks of third-party scanner/search data confirm that U.S. growth is broadening beyond one retailer or one hero SKU.
- Pair idea for 1-3 months: long WMT / short TGT on the thesis that mass-premium skincare scale is more durable in Walmart’s omnichannel model; target modest upside if beauty comps inflect, cut if Target’s discretionary traffic reaccelerates.
- Tactical long AMZN on pullbacks only if channel checks show repeat purchase strength; the convexity comes from high-frequency replenishment and low-friction search, but the trade should be exited if review velocity stalls or returns rise.
- Stay neutral ULTA until there is evidence that the brand is incremental to prestige skincare traffic rather than cannibalistic; a failed expansion would argue for underweighting ULTA relative to retailer peers with stronger search-driven demand.
- Set an alert on CVS front-store margin and beauty comps: if premium skincare lifts basket without a trade-spend spike, CVS becomes a cleaner beneficiary; if not, avoid chasing the story.
More News
- Is AI the new China Shock?
- Wall St futures gain as oil slips; telecoms pressured by SpaceX spectrum deal
- OpenAI projected to bring in $20bn less in revenue than expected
- New data shows Starbucks turnaround is working, but Chipotle takeover report slams shares
- Trump admin suspends green cards to Microsoft as Vance accuses the company of replacing laid-off workers with ‘foreign indentured servants’
- This cybersecurity stock is already growing revenue at a 20% clip. And now here comes the AI boost
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI for Sell-Side Models, Estimates, and Internal Data
- How to Write an Investment Memo with AI: A Decision-Record Template