
La China International Big Data Industry Expo 2026 se inaugura en Guiyang
Source: PR Newswire
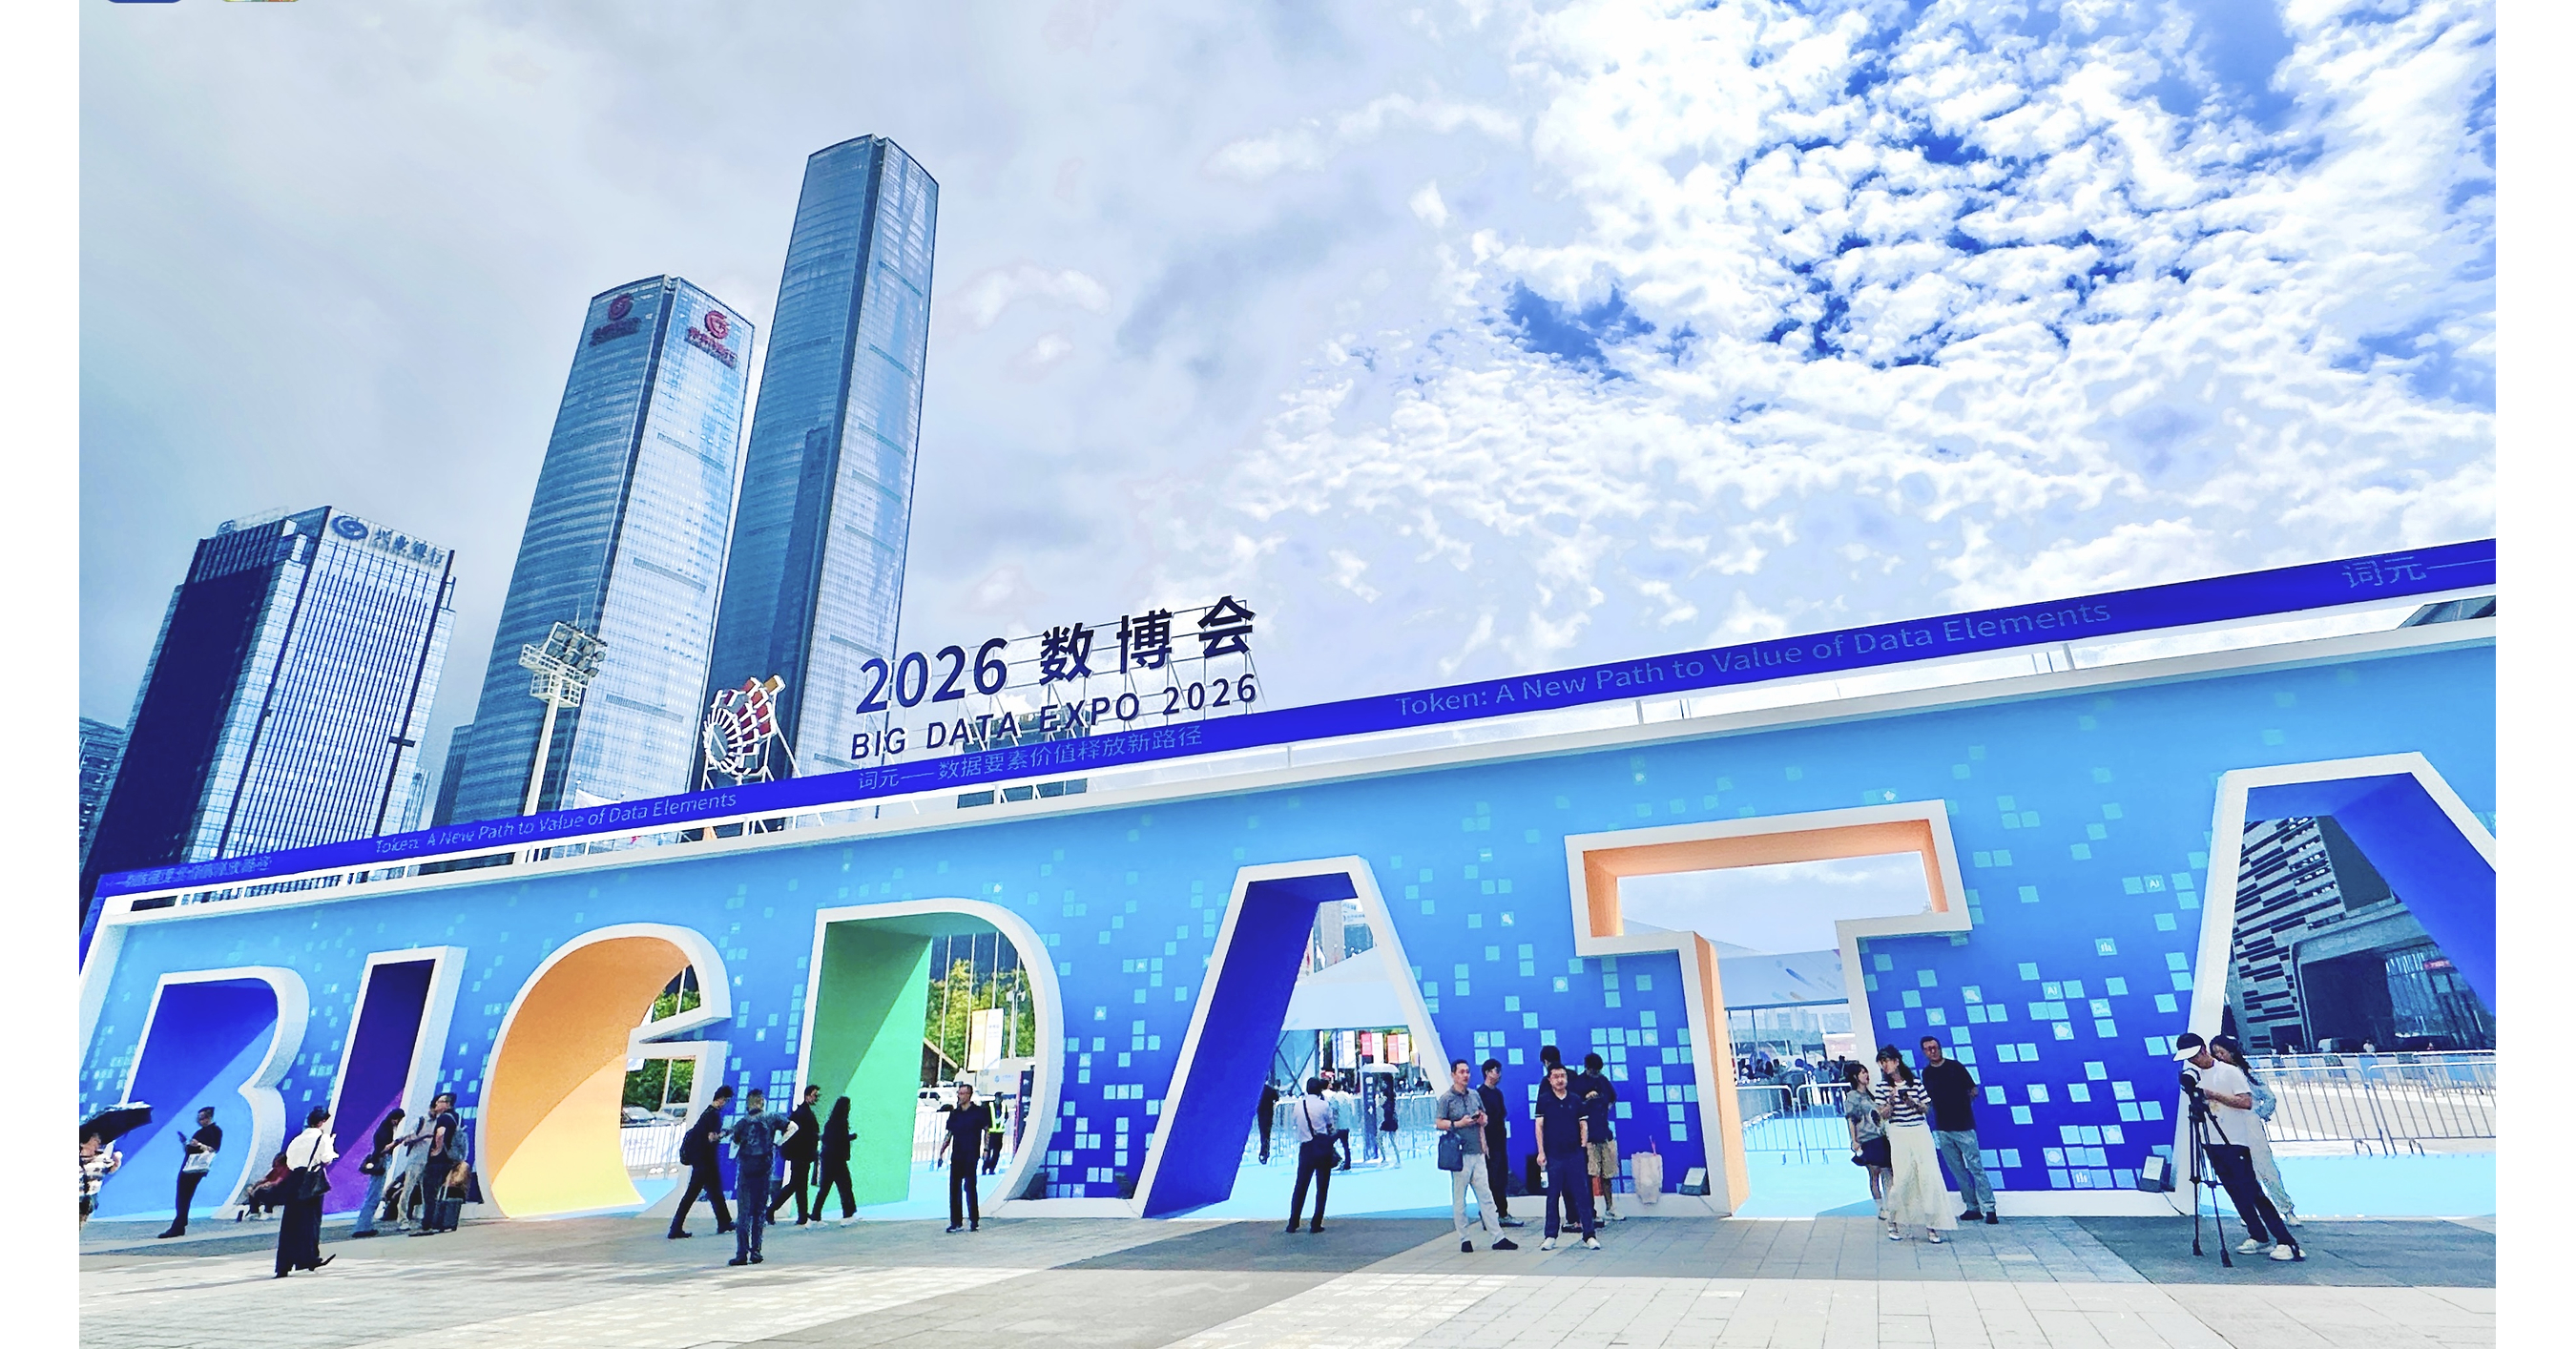
La China International Big Data Industry Expo 2026 se inauguró en Guiyang (28 de agosto), con el lema “Token: un nuevo camino hacia el valor de los elementos de datos”, reuniendo a más de 300 expositores. La región reporta 26 centros de datos con capacidad de cómputo total superior a 174 EFLOPS, con PUE promedio bajo de 1,19 y “computación inteligente” representando más del 98% del total. Además, los ingresos del sector de software y servicios TIC en la zona superan los 100.000 millones de yuanes, señalando un impulso a la economía digital, aunque el impacto directo en mercados financieros es limitado.
Analysis
This reads more like a policy-capex signal than a revenue event. The investable implication is not the expo itself, but the implied willingness of local and central stakeholders to keep subsidizing compute-heavy infrastructure in lower-cost inland regions, which is bullish for vendors tied to power delivery, cooling, racks, and security rather than pure app-layer software. The marginal winner is the ecosystem that monetizes watts and uptime—data-center operators, electrical equipment, and thermal-management suppliers—because the headline economics are driven by utilization and PUE, not by conference optics.
The second-order effect is competitive displacement inside China’s digital buildout. If Guizhou/Gui'an continues to absorb AI training and storage load, it can pull demand away from higher-cost coastal hubs and compress pricing for commoditized colocation, while improving economics for operators with the best financing and grid access. That tends to favor scale players and state-backed infrastructure channels, and it is mildly negative for smaller operators that cannot match sub-1.2 PUE performance or secure low-cost power contracts.
The contrarian point is that this may be more supply-push than demand-pull. A large installed base does not automatically translate into monetizable workloads if utilization stays soft or if model-training spend decelerates; in that case, returns on invested capital can lag the buildout by 12-24 months. The real falsifier is not the rhetoric around data-tokenization, but evidence that AI server utilization, lease-up rates, and power draw are not rising in the next two quarters. If that happens, the market will likely re-rate the entire China AI-infra complex as overbuilt rather than strategic.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- Watchlist, not a high-conviction trade: prefer China data-center scale names (GDS, VNET) only on confirmation of utilization and funding improvement; otherwise avoid chasing the headline because capex intensity can dilute equity value before cash flow inflects.
- Relative-value idea: long electrical/power-cooling beneficiaries versus generic China internet exposure over 3-6 months; the clearest earnings transmission is into grid equipment, UPS, liquid cooling, and monitoring vendors, not into consumer internet multiples.
- If you want AI-infra exposure without China policy risk, express it through global colo/power proxies (EQIX, DLR) on weakness only if U.S. demand remains strong; the article is a reminder that compute scarcity is global, but China policy can accelerate domestic capacity buildout and cap pricing power abroad.
- Set a falsifier alert: if local PUE or utilization data fails to improve by the next earnings cycle, fade any rally in China AI-infrastructure names; that would indicate the market is pricing strategic intent faster than cash earnings.
- Avoid an outright bullish sector basket until there is evidence of contracted workloads; absent that, the better trade is a patient pair: long selected power/cooling suppliers, short a weaker China colocation operator if financing costs or occupancy trends deteriorate.
More News
- Huge profits at tech and energy companies are masking this key trend
- Why this little known Chinese chipmaker has caused a global stock rout
- Apple releases HomeView smart home hub with screen as showcase for Siri AI
- Microsoft Eyes First Record in Nearly a Year as AI Rally Builds
- Why did investors react so negatively to Schneider-PTC deal? M&A expert weighs in
- French fridge fright: Why supermarkets have become target for hackers
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Capital IQ Alternatives for Research and Deal Work
- Research Workflows, Report Format Selection, and Interactive Synthesis