
SANY registra un crecimiento de más del 300 % en sus ingresos internacionales en WindEnergy Hamburg 2026
Source: PR Newswire
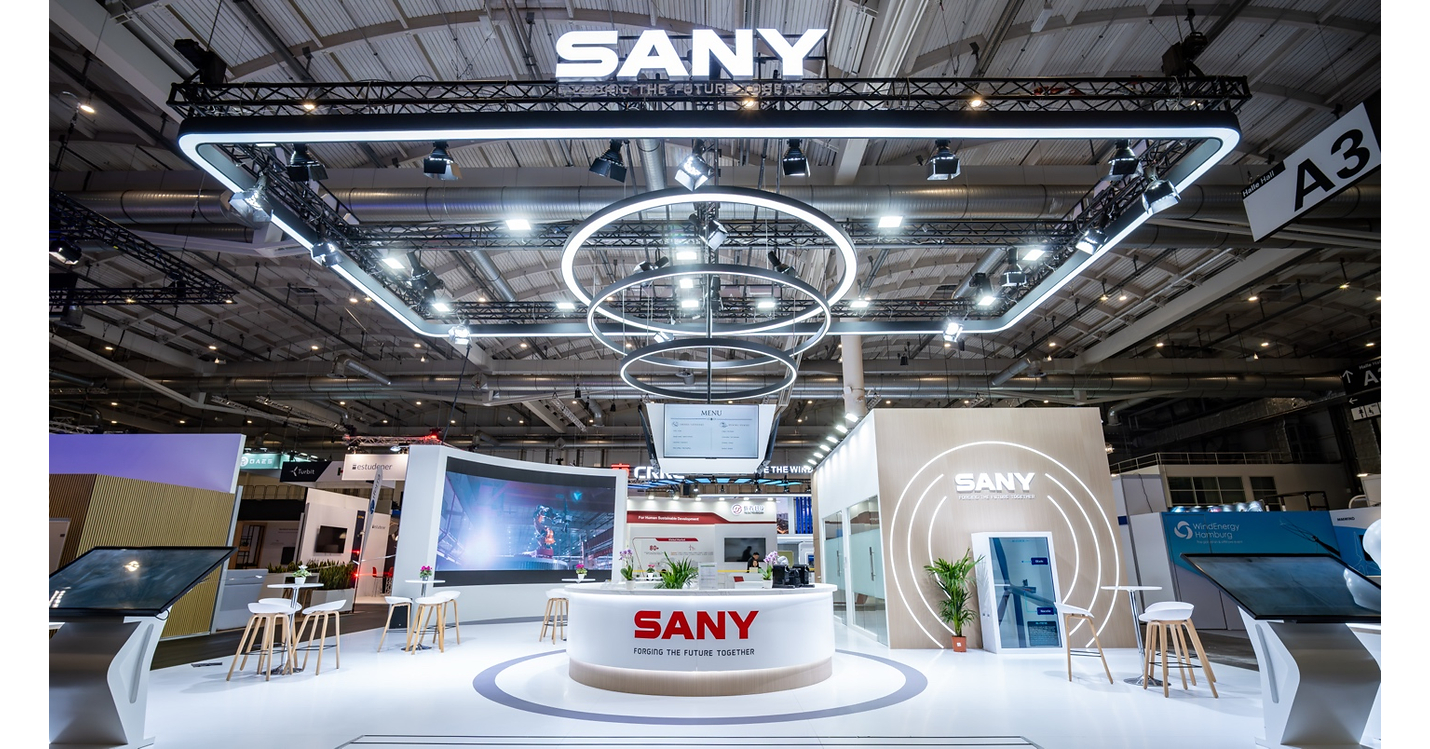
SANY Renewable Energy reported that first-half 2026 overseas revenue rose more than 300%, while signed international orders approached 5 GW. The company received DNV European certification for its SI-17578EU wind turbine and has reached 1,462.35 MW of installed overseas capacity across Europe, Latin America and Asia. Its global expansion is supported by 10 MW turbine technology, a 35 MW testing platform, AI-based blade-clearance modeling and financing due-diligence support for project developers.
Analysis
The relevant equity implication is not SPGI; its supplier-ranking product has negligible earnings sensitivity to a single entrant. The more important read-through is that a Chinese OEM is reducing a key barrier to competing for European and internationally financed projects: lender and insurer acceptance. If conversion follows, the pressure falls most directly on Vestas (VWS.CO), Nordex (NDX1.DE) and Siemens Energy (ENR.DE), where service attach rates and pricing discipline—not just turbine deliveries—support valuation. A lower-cost qualified alternative could force concessions on warranty terms, availability guarantees and long-term service agreements, with margin effects appearing before material share-loss data is visible.
The near-term signal remains low quality: a trade-show release, certification and signed orders do not establish backlog quality, cancellation risk, project financing, or profitability after localization, logistics, tariffs and warranty reserves. Over the next 1-3 months, monitor disclosed European order wins, financing close announcements, and evidence that Western developers accept the OEM on non-recourse financing terms. Over 6-18 months, sustained penetration would be structurally bearish for European turbine OEM gross-margin recovery, but potentially positive for developers and independent power producers whose project IRRs benefit from lower turbine capex.
Consensus may overstate the immediacy of disruption. European procurement remains constrained by local-content preferences, trade-defense risk, cybersecurity scrutiny and the high cost of an unproven long-duration service record. The thesis is falsified if incumbent order pricing and service margins hold through the next two reporting cycles, or if EU tariff/procurement restrictions materially raise delivered Chinese-turbine costs; in that scenario, this is primarily competitive signaling rather than an investable share-shift.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- No direct position in SPGI: the cited ranking/certification ecosystem is not large enough to move estimates. Treat any SPGI price reaction as noise unless management identifies incremental recurring data, ratings or sustainability-revenue contribution.
- Set a 1-3 month alert for European project awards or financing closes involving Chinese turbine OEMs. If two or more independently financed EU awards emerge, initiate a tactical pair: long ENPH or EDPR.L / short VWS.CO, targeting 8-12% relative return over 6 months; stop if Vestas maintains service-margin guidance and reports stable order pricing.
- For existing longs in VWS.CO, NDX1.DE or ENR.DE, reduce exposure into the next order-intake updates unless management demonstrates stable average selling prices and warranty provisions. The risk/reward is asymmetric where market expectations already embed margin normalization but low-cost competition has not yet been reflected in estimates.
- Watch EU trade-policy announcements and European turbine tender bid spreads over the next 6 months. A formal tariff/local-content escalation would invalidate the near-term competitive threat and support covering any OEM shorts; absent that, widening price dispersion is an early warning that margin pressure is becoming real.
More News
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- SpaceX Can't Join the S&P 500 Before June 2027 -- and Its Losses Could Keep It Out Longer
- Nvidia's Demand Is Outpacing Its 70% Growth Forecast, and That Is Just the Beginning
- Market sees next Fed hike in October, following Barr comments and hot inflation reading
- Business Activity in the Euro Area Reaches Three-Year High
- The Economy Is Booming, So the Market Indexes Fell. Go Figure.