
Pudu Robotics Unveils "One Brain, Multiple Embodiments" Strategy and Showcases Full Portfolio in European First
Source: PR Newswire
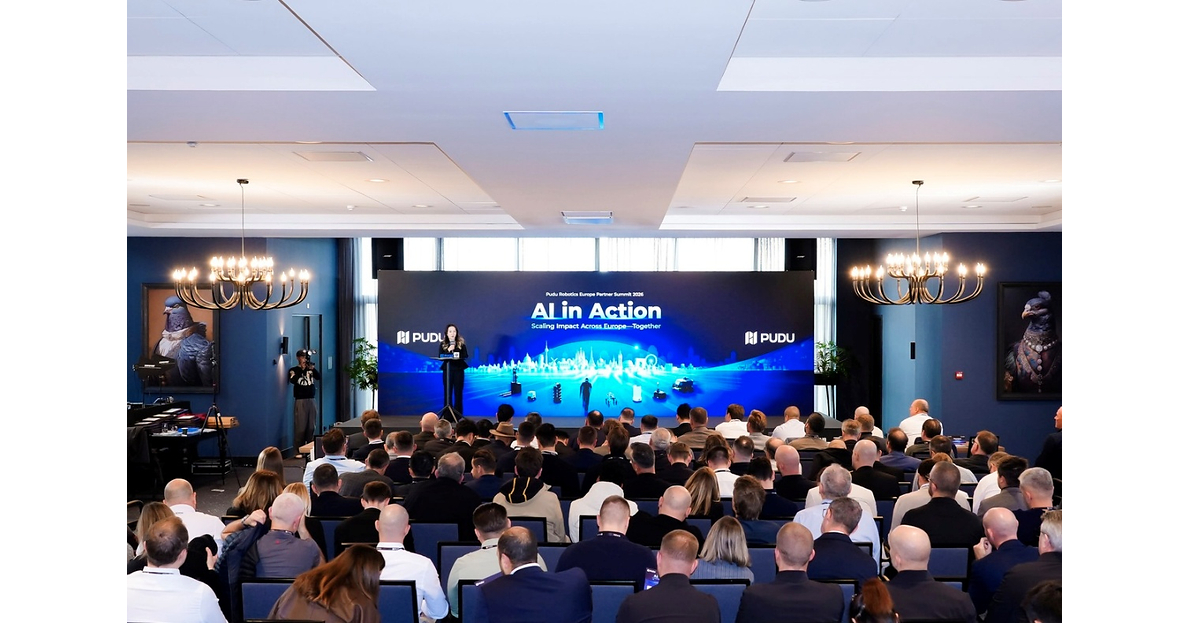
Pudu Robotics unveiled its “One Brain, Multiple Embodiments” strategy and six-line product ecosystem at its first large-scale European partner summit, expanding its offering across commercial, industrial, embodied-AI and home robotics. European revenue grew by an average of more than 60% annually over the past two years, and Pudu operates in more than 20 European countries; it also announced a German headquarters on October 30. The announcement highlights product and regional expansion, but provides no financial guidance or market reaction.
Analysis
The investable signal is not the breadth of the lineup; it is whether common software genuinely lowers the cost of deploying and supporting very different machines. Reusable perception and fleet-management layers could improve engineering leverage, but separate hardware, motion control, safety validation, and field service may still leave unit economics highly product-specific. A six-line portfolio also risks diluting engineering and channel capacity before any one new category reaches repeatable scale.
Europe’s reported growth is encouraging but does not establish attractive economics: absolute revenue, starting base, gross margin, customer retention, and support costs are undisclosed. The new regional infrastructure may strengthen a service moat, while adding fixed costs and parts inventory ahead of proven utilization. The consumer lawn-care launch is a different risk profile again—retail acquisition, seasonality, returns, and warranty burden—not simply another enterprise deployment.
Near term, the announcement is a weak standalone catalyst; it is promotional and supplies no independently verifiable adoption or profitability data. Over 1–3 months, watch for paid deployments, repeat orders, utilization, service response costs, and evidence that software is shared across products rather than merely branded as a platform. Over 6–18 months, successful localization could help defend against lower-priced service-robot competitors, while weak utilization or expensive field support would undermine the scale thesis. European safety, privacy, and AI compliance requirements are potential deployment friction, not an automatic barrier.
Contrarian read: investors may overvalue “embodied AI” optionality while underweighting implementation labor and customer payback periods. No mapped ticker or sufficiently pure public exposure is provided, so the announcement alone does not justify a directional trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- No trade on the release alone. The company identity data supplies no ticker; verify investability and any public-market exposure before building a position.
- Place on a 1–3 month diligence watch: seek product-level revenue, gross margin, repeat-order rates, customer utilization, and deployment/service cost—especially for Europe and the consumer lawn-care line.
- Treat evidence of rising support costs, weak repeat orders, or no measurable cross-product software reuse as thesis-falsifying; evidence of improving utilization and repeat deployments would strengthen the longer-term platform case.
More News
- Magnificent 7 loses $1 trillion. The most eye-popping stats from Thursday's tech stock plunge
- Tech stocks are suffering their biggest selloff since Covid, as investors see premature end to AI datacenter boom
- Wall Street’s best post-midterm rally in 44 years lasted just one day—then $3 trillion vanished as chip stocks plunged over AI fears
- How Wall Street's postelection rally got obliterated — and what's next
- AI stocks plunge after election, driving down US markets
- Elon Musk's Tesla and SpaceX lose over $420 billion in combined market cap after midterms