
Fourth-Generation Model of the Award-Winning LDS Series of Mobile LED Displays from ViewSonic Now Shipping
Source: PR Newswire
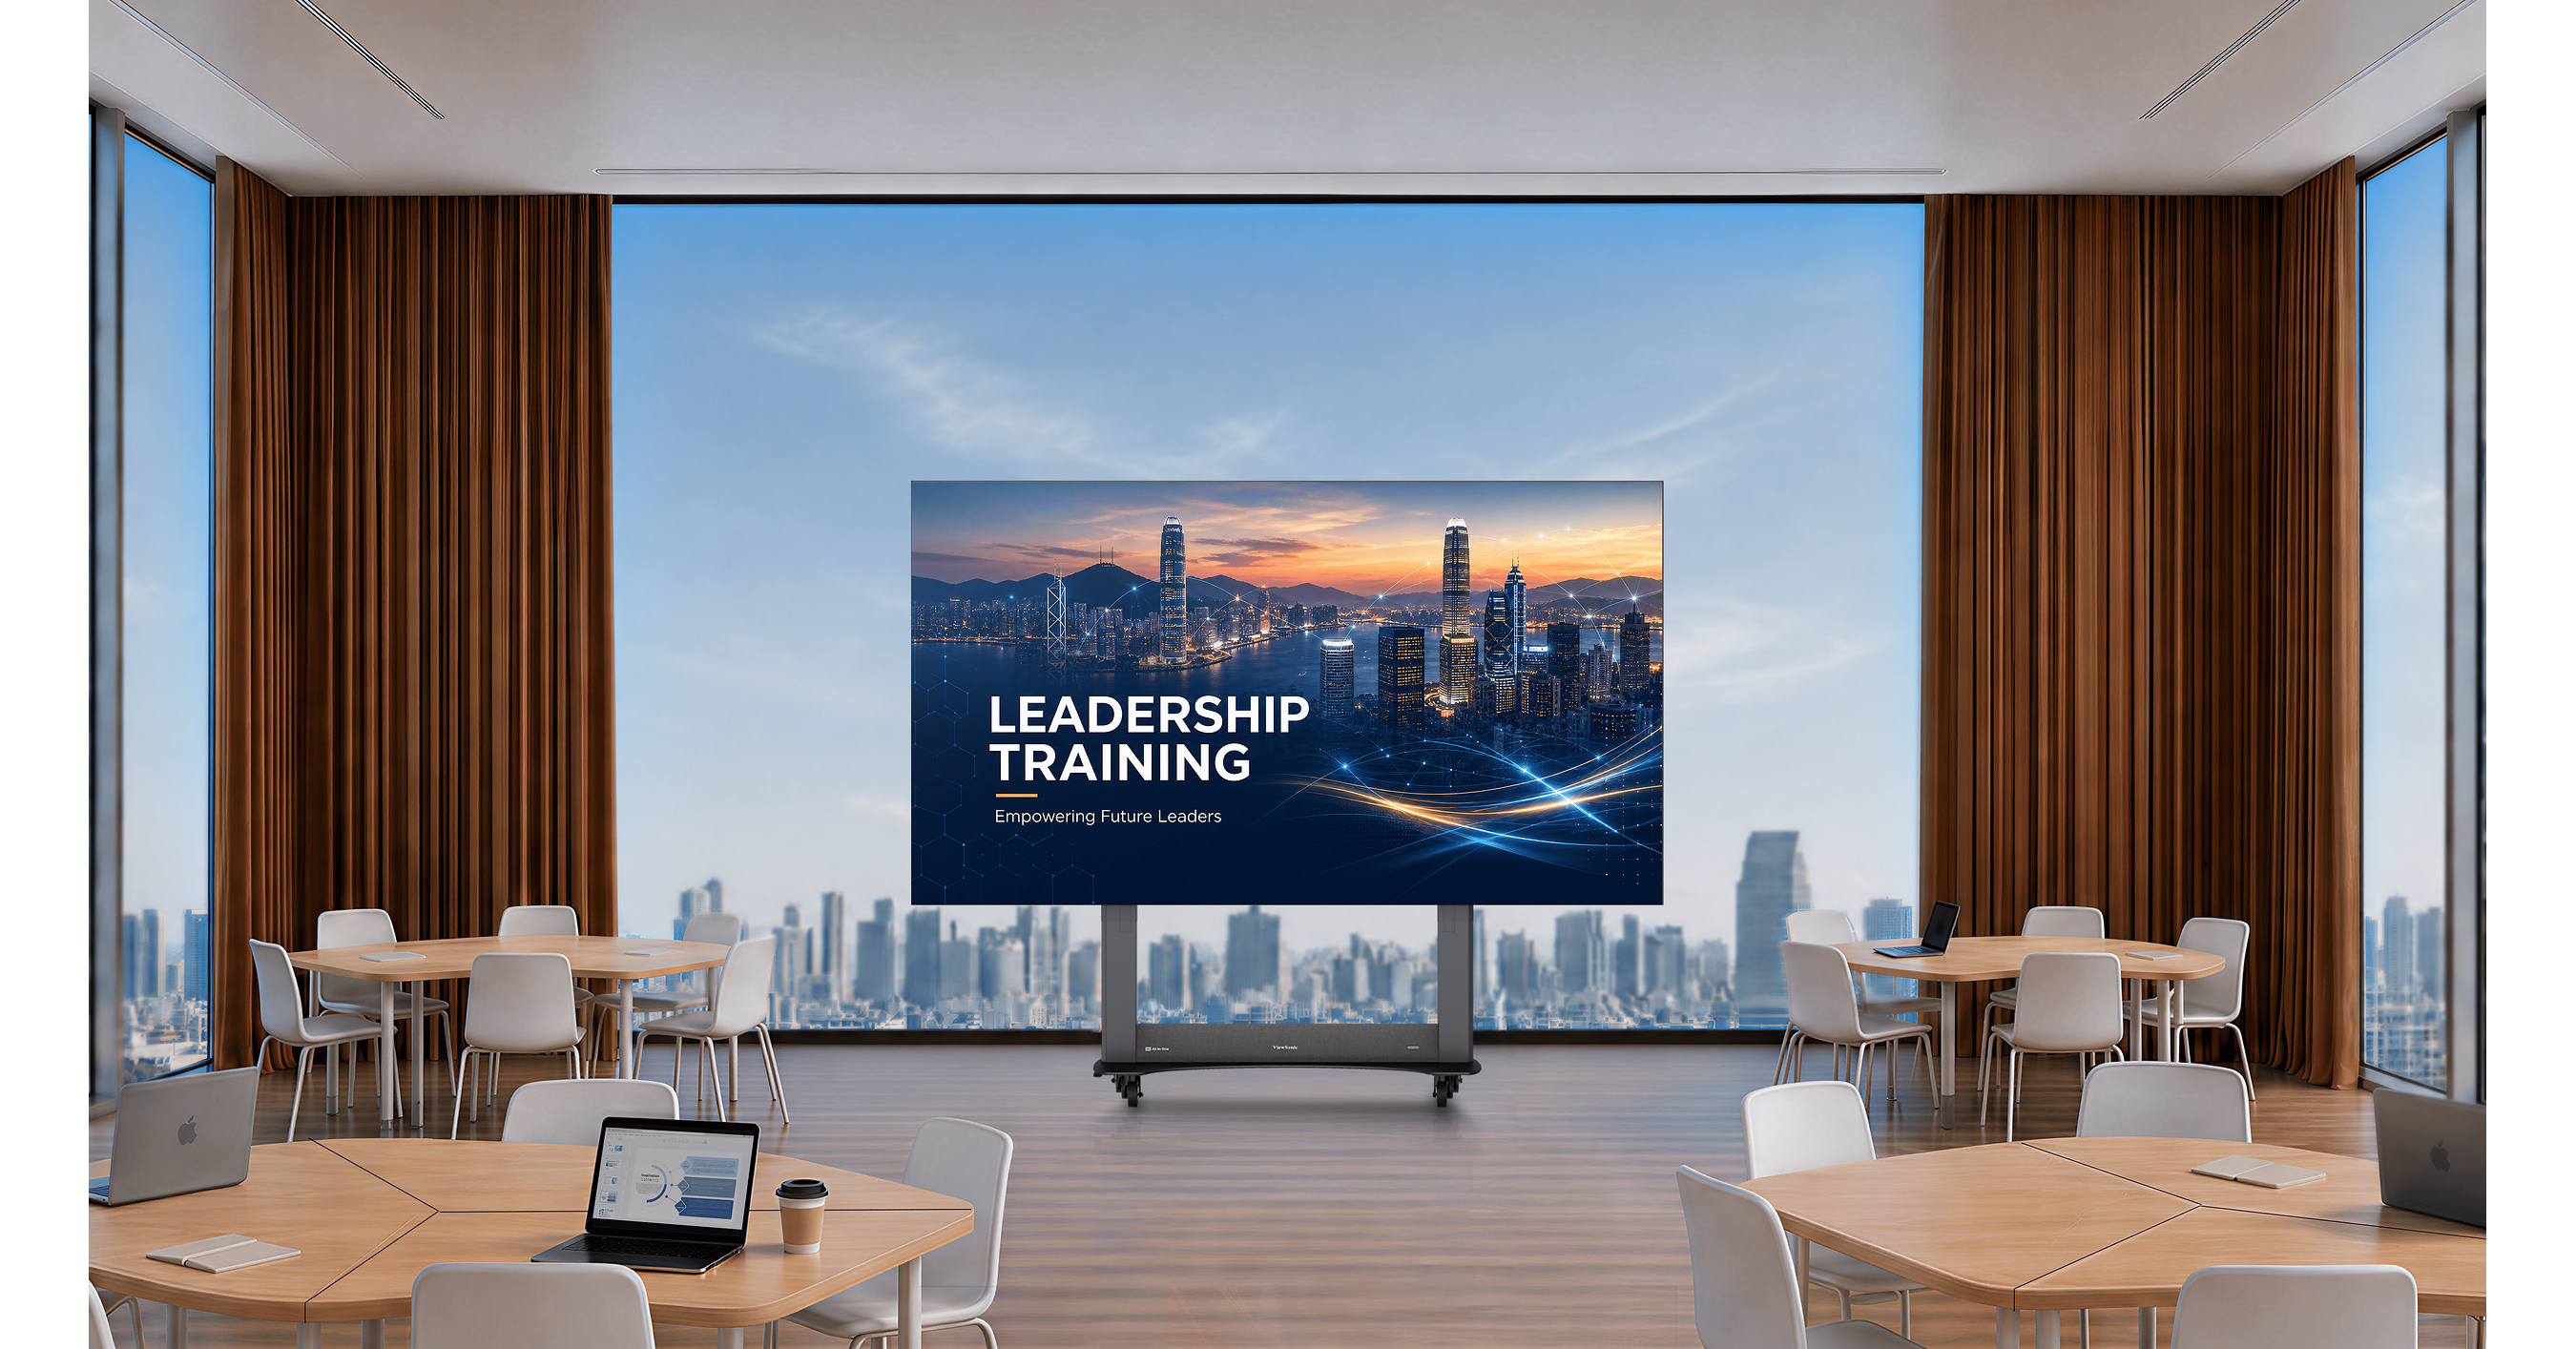
ViewSonic has begun shipping its fourth-generation LDS136-152, a pre-assembled, foldable 136-inch mobile Direct View LED display. The product adds a motorized stand with 3.7 feet of vertical adjustment, IP65/IK06 durability ratings, 1080p resolution, 600-nit brightness and wireless sharing capabilities. The launch aims to lower deployment complexity and installation costs for AV/IT users, but no pricing, sales outlook, or financial impact was disclosed.
Analysis
This is not investable on its own: ViewSonic is private and the supplied ticker, ONE, has no identifiable operating linkage to the announcement. The relevant read-through is that portable all-in-one dvLED is shifting competition away from panel specifications toward deployment labor, rental flexibility, control-system interoperability, and field-service economics. That favors vendors with channel coverage and installed-base software/control ecosystems—Samsung Electronics (005930 KS), LG Electronics (066570 KS), and Sony (6758 JP)—rather than creating a near-term public-equity catalyst.
The product category could marginally pressure projector demand in premium corporate events, education, hospitality, and protected-building retrofits, where installation cost and physical modification are the binding constraints. Epson/Seiko Epson (6724 JP) has the clearest theoretical exposure, but mobile dvLED remains a high-ticket, niche substitute; any revenue impact would require evidence of tender wins or rental-fleet orders over the next 1-3 quarters. Conversely, stronger mobile LED adoption can support AV integrators and control vendors such as Crestron’s private ecosystem, but there is no disclosed volume, pricing, backlog, or customer commitment to underwrite a financial estimate.
Consensus may overvalue the stated total-cost-of-ownership savings: a preassembled product reduces installation labor but transfers durability, logistics, repairability, and financing risk to the manufacturer/channel. The key falsifier for a broader category thesis is whether mobile LED deployments expand beyond event/rental use into recurring enterprise standardization; monitor quarterly commercial-display commentary from Samsung, LG, Sony and Epson, plus European AV tender data, over 6-18 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No position in ONE: confirm the ticker identity and any commercial relationship before treating the release as a catalyst; current data assigns zero company-specific impact.
- Set a 1-3 quarter watch alert on Seiko Epson (6724 JP): consider a tactical short only if management cites sustained weakness in high-lumen installation projectors alongside evidence of mobile dvLED tender displacement. Cover on stable projector backlog or improving corporate-event demand.
- Maintain a relative-value watchlist of long Samsung Electronics (005930 KS) or LG Electronics (066570 KS) versus Seiko Epson (6724 JP), not an immediate trade. Initiate only after two sequential quarters of commercial-display growth and corroborating projector-margin pressure; absent that evidence, category size is too small for a meaningful pair catalyst.
- For 6-18 months, monitor European public-sector/hospitality retrofit procurement and AV rental-fleet capex. A material increase in no-installation display awards would favor large display vendors with service networks, while failure to convert pilots into fleet orders would invalidate the portability-led adoption thesis.
More News
- China's AI chip blitz arms Xi with a message for Trump: 'You can't choke us off'
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Meta's standoff with Amazon over Muse could be a sign of things to come
- Mark Zuckerberg debuts $1,299 Meta VR Glasses and Muse Charm pendant amid AI agent push
- Meta Debuts $349 Camera-Free Ray-Bans and Brings Muse to Glasses