
Ampera y Lawrence Livermore National Laboratory anuncian una alianza estratégica
Source: PR Newswire
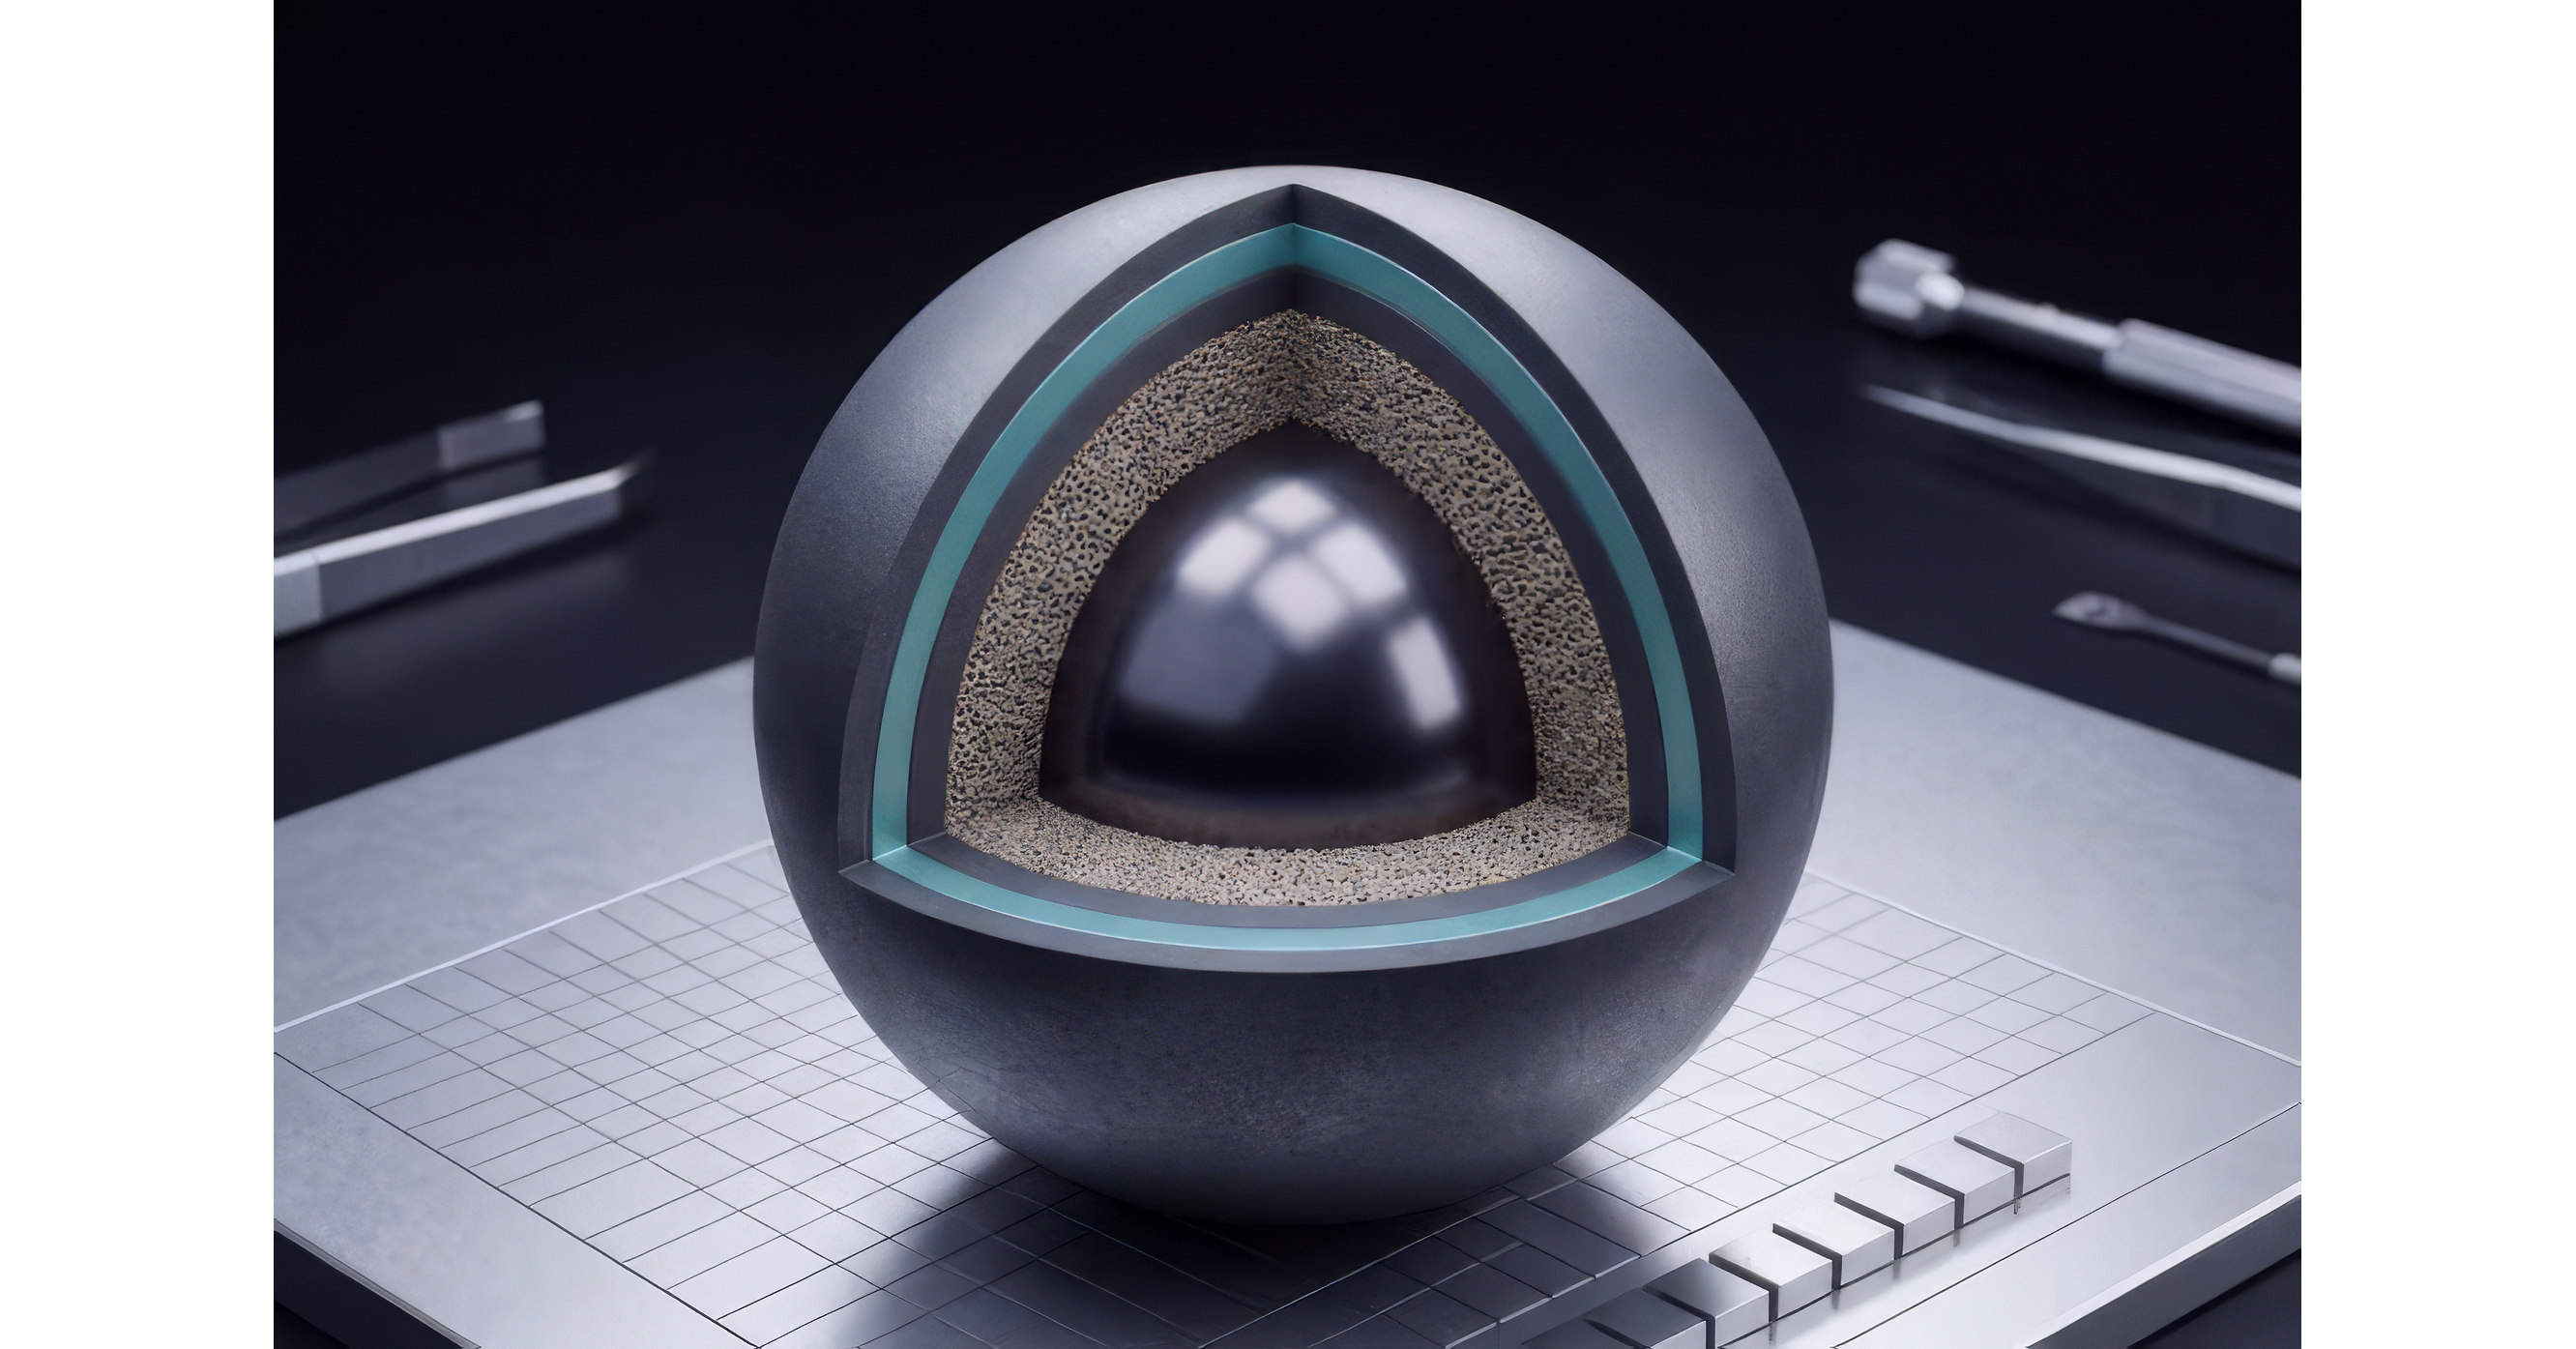
Ampera anunció una alianza estratégica con Lawrence Livermore National Laboratory para desarrollar combustible nuclear avanzado TRISO, incluyendo la optimización de tecnología de inyección de metal líquido para núcleos esféricos de torio-232. El proyecto contempla modelización computacional, ensayos de materiales a alta temperatura, caracterización de partículas y transferencia de procesos escalables, apoyándose en una base de IP (más de 60 patentes) y en la futura integración vertical de la cadena de suministro. La colaboración busca acelerar la fabricación resiliente y reducir costes/riesgos para habilitar sistemas compactos y subcríticos con hasta 30 años de operación sin recarga de combustible.
Analysis
This is more validation than monetization: the near-term winner is not the private company, it is the domestic nuclear supply chain that can already sell fabrication, fuel handling, and qualification services. The market should read this as incremental evidence that advanced fuel for defense/data-center use cases is moving from concept to procurement logic, which is constructive for BWXT and, at the margin, LEU-type fuel-cycle exposure. The second-order effect is a stronger "sovereign supply" premium: if customers start valuing U.S.-based fuel assurance over cheapest-feedstock economics, foreign enrichment and commodity uranium become less important than conversion, HALEU handling, and specialized manufacturing capacity.
The immediate equity reaction can be noisy, but the real catalyst path is 1-3 quarters, not days: follow-on DOE money, pilot-line economics, and any early customer LOIs matter far more than this announcement. The biggest falsifier is a slip from lab-scale optimism to industrial bottlenecks — materials compatibility, QA yield, hot-cell throughput, and licensing friction can easily turn a strategic partnership into a science project. Also, the subcritical design still depends on external neutron source infrastructure, which means the "30-year no refuel" pitch does not eliminate operating complexity; it just shifts risk into a different part of the stack.
Contrarian view: the market may overpay for "nuclear optionality" while underappreciating that the winners are often the boring suppliers, not the reactor developers. If this theme persists, public names with existing revenue and federal relationships should outperform pre-revenue concept stocks, because qualification work tends to reward incumbency and balance-sheet endurance. Over 6-18 months, the opportunity is less about a sudden reactor buildout and more about a multi-year buildout in fuel fabrication, testing, and licensing services.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Long BWXT vs short a speculative advanced-reactor basket (e.g., OKLO/SMR) over 1-3 months: BWXT has nearer-term revenue capture from fuel qualification and DOE-adjacent work, while the shorts remain valuation-sensitive to any commercialization delay. Stop if the speculative basket gets a fresh federal funding or licensing milestone.
- Initiate a tactical long LEU on any pullback after the announcement, targeting a 2-3x upside on a sustained domestic HALEU/fuel-cycle rerate over 3-6 months. Falsify if DOE funding or enrichment/processing demand does not follow within the next quarter.
- Use URA as a lower-beta expression if you want theme exposure without single-name execution risk; better for 6-12 month horizon than a one-day trade. Reduce if uranium/feedstock prices rally without corresponding fuel-cycle capex commitments.
- Avoid chasing the private-company narrative; treat this as a watch item until there is a signed customer contract, pilot throughput data, or regulatory milestone. No trade if those data points do not emerge within 1-2 quarters.
- If you want a relative-value hedge, pair long nuclear suppliers with a short in a broader utilities ETF (XLU) only if rate cuts stall and clean-energy multiples reflate; otherwise the cleaner trade is inside the nuclear supply chain, not against defensives.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- India unveils tough curbs on dollar demand to defend rupee
- Bank of America is bullish on these top stocks ahead of earnings
- Stocks were up this week. Here are the names that are now overbought
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: In-App Tutorials, Futures Data, and Watchlist Enhancements
- AI Tools for Independent Research Firms: A Publishing System