
Scheidt & Bachmann USA Selected by NEORide Through Competitive Procurement to Provide Cash Farebox Systems to Member Agencies
Source: PR Newswire
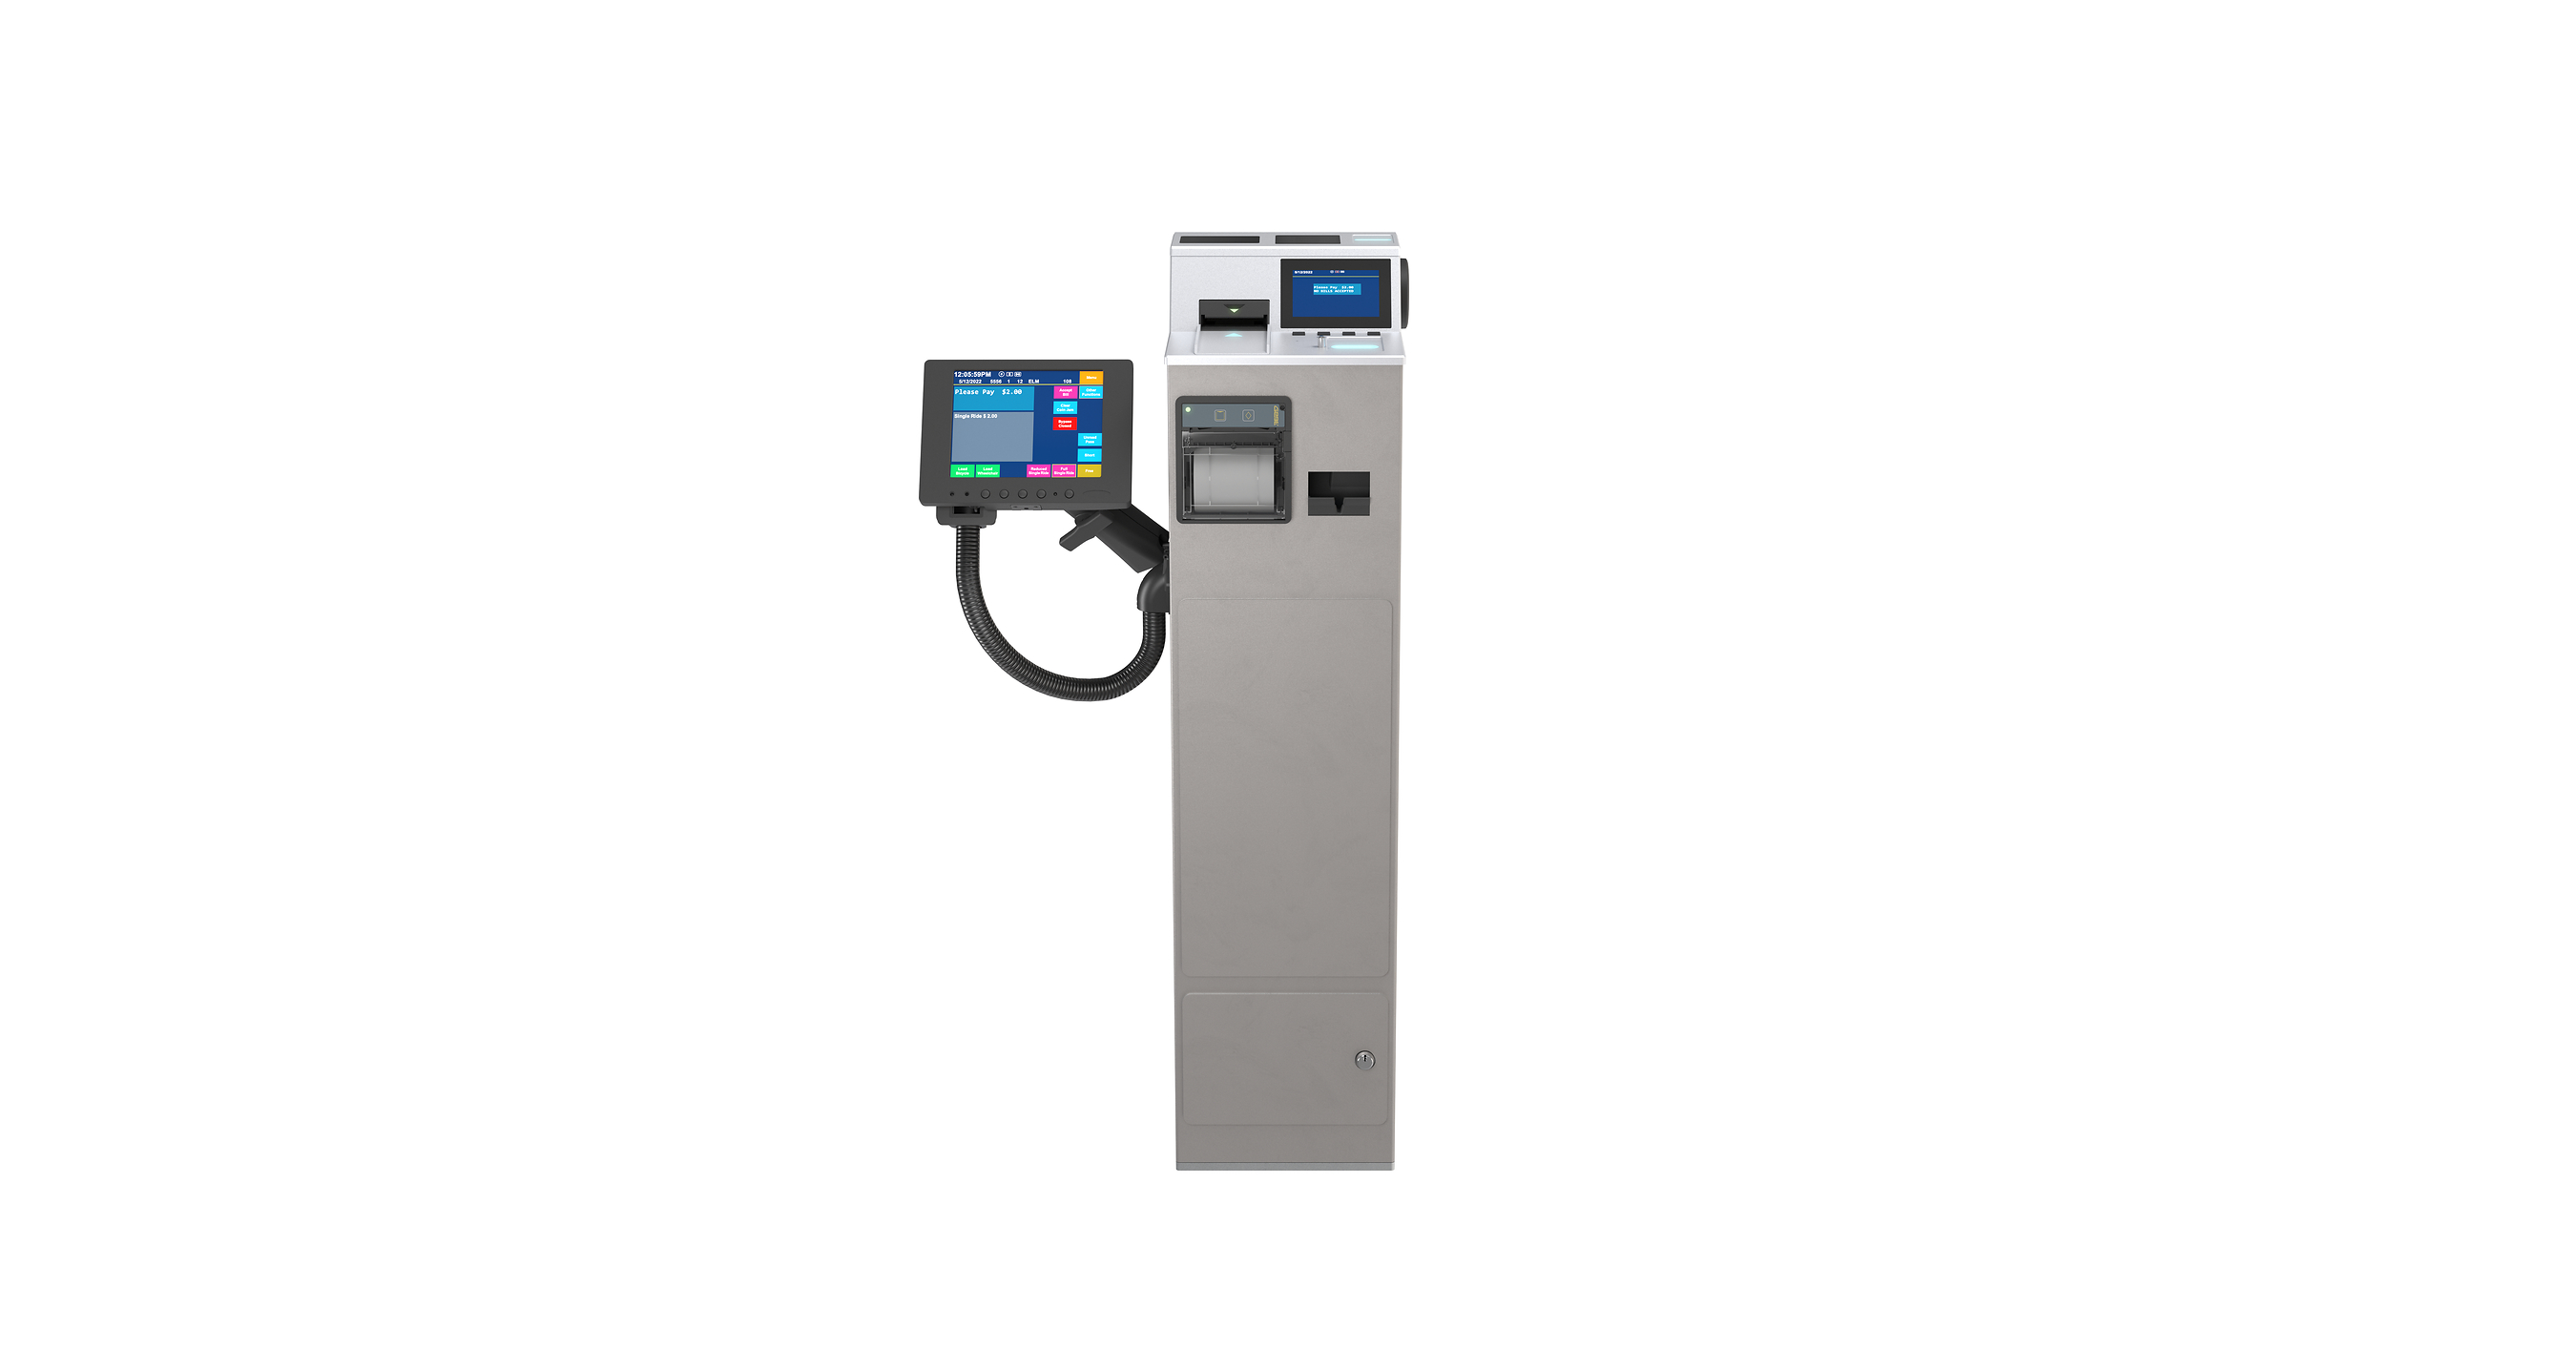
Scheidt & Bachmann USA was selected by NEORide to supply cash farebox systems to NEORide’s 45 public transit agencies across 13 states. The article frames the win as validation of reliable, scalable, and “future-ready” fare collection technology, aimed at supporting cash-paying riders. This is a positive but likely company-specific contract update with limited market-wide impact.
Analysis
This reads more like a signal about procurement durability than a true earnings event. In the near term, the market should treat it as confirmation that legacy fare acceptance infrastructure is not disappearing as fast as digital-payment narratives imply; that is supportive for the small set of transit-tech vendors with installed bases and service relationships, but the order economics are likely too small and too episodic to matter for broad equity valuation.
The second-order effect is on competitive positioning inside transit modernization budgets. If one vendor becomes the default on a multi-agency procurement path, it can create a service and replacement funnel over 1-3 years, which is more valuable than the initial hardware sale; that tends to favor incumbents with field service networks and spare-parts revenue, and it disadvantages smaller integrators that rely on one-off deployments. For agencies, keeping cash acceptance alive also raises operating friction, so the upside for vendors is matched by a slow but persistent cost burden for operators.
The key risk/catalyst is whether this is a placeholder award versus a real roll-out with measurable capex. Without contract value, deployment timing, or minimum volume commitments, there is no reliable way to size upside; if agencies pivot to open-loop/contactless fare systems or receive modernization grants tied to cash reduction over the next 6-18 months, the thesis weakens quickly. A reversal would likely show up first in procurement language and pilot conversions, not in quarterly reported revenue.
Contrarian take: consensus may be over-reading the strategic significance because legacy farebox systems are often procurement-maintenance businesses, not growth businesses. The market is more likely to miss the installed-base maintenance tail than to underappreciate a new logo win. Net/net, this is a watch item, not a conviction trade, unless subsequent disclosures show a meaningful multi-agency rollout with recurring service revenue.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Key Decisions for Investors
- No immediate public-equity trade; treat this as a procurement signal only until contract value, deployment cadence, and recurring-service terms are disclosed.
- Set an alert for any follow-on announcement showing multi-agency purchase orders or blanket pricing under the NEORide umbrella; only if the disclosed value is material would this become a positive read-through for transit-tech vendors.
- Watch listed transit/payment-adjacent names for secondary confirmation of legacy fare infrastructure demand; if contactless adoption commentary accelerates instead, fade any bullish read-through on hardware-heavy vendors.
- If you need a proxy exposure, prefer a small, tactical long in a transit-tech beneficiary only after confirmation of recurring service economics; otherwise stay flat because the initial hardware win is likely too small to move fundamentals.
More News
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Trump says he’s evaluating whether the U.S. should join Saudi Arabia’s fight against Iran-backed Houthi rebels in Yemen after fresh attacks on Riyadh
- World condemns deadly Houthi attack on Saudi Arabia’s Riyadh airport