
Nirvik Singh to Join Monks International Leadership Team and, as a First Step, Lead EMEA Business, Accelerating Regional Growth and Real-Time Marketing
Source: PR Newswire
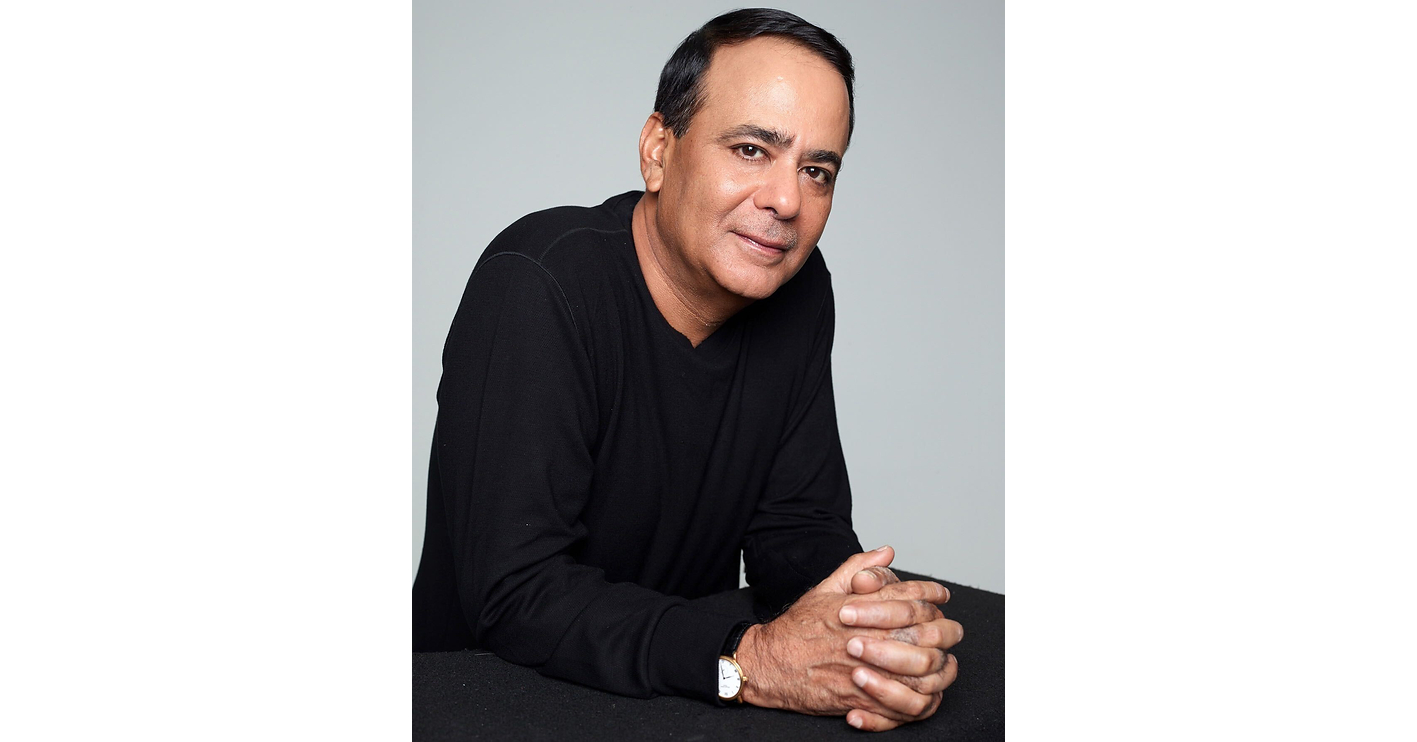
S4Capital's Monks appointed former Grey Group Global COO and President International Nirvik Singh as CEO of EMEA Marketing Services, effective 1 October 2026; Singh will leave S4Capital's board to assume the executive role. The appointment is intended to accelerate EMEA commercial growth and unify regional operations around Monks' integrated creative, media and technology model. Looking into 2027, Monks plans a broader rollout of its Monks.Flow AI and workflow platform, though the release provides no financial targets or quantified outlook.
Analysis
This is principally an execution signal rather than an earnings catalyst: EMEA remains too small in S4 Capital's revenue mix for a leadership change alone to alter FY26 estimates. The relevant read-through is that management is allocating senior operating capacity to a region where multinational client consolidation can improve account density and utilization; if successful, incremental revenue should carry better margins than broad-based hiring because the platform already has regional infrastructure. The board-to-operator transition also raises the bar for disclosed EMEA new-business wins and retention metrics over the next two reporting periods.
The competitive pressure is more meaningful for WPP than for client companies such as PG, KO, HLN, or VOLCAR.B. Monks' integrated proposition targets the portion of agency budgets exposed to roster rationalization, production automation, and performance-media measurement; incumbent holding companies face price compression unless they can demonstrate comparable workflow integration without sacrificing creative quality. Conversely, widespread AI-enabled content production may reduce industry revenue per asset, so S4's upside depends on capturing a larger share of client workflow—not merely delivering more content at lower unit prices.
Consensus may overvalue the management narrative while underweighting proof requirements. Enterprise marketing contracts have long sales cycles and procurement-led savings often precede agency consolidation, implying limited near-term P&L impact; the 6-18 month opportunity is credible only if S4 converts named global relationships into multi-country scopes and raises Technology Services mix. A reversal would be signaled by continued organic net-revenue weakness, declining gross margin despite automation claims, or further deterioration in net debt/EBITDA and free-cash conversion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on the appointment alone; treat SFOR as a 1-3 month catalyst watch. Add only after the next results show improving organic net revenue and stable-to-higher gross margin, with EMEA wins quantified rather than described qualitatively.
- Maintain a tactical relative-value watch: long SFOR / short WPP only if SFOR demonstrates two consecutive periods of relative organic-growth improvement and no leverage deterioration. The thesis is share capture from integrated global mandates; stop if SFOR guidance is cut or WPP's retention/new-business disclosures materially improve.
- For existing SFOR exposure, require evidence that automation is expanding contribution margin rather than accelerating pricing pressure: monitor revenue per head, utilization, gross margin, Technology Services mix, and operating cash conversion over the next 6-18 months.
- Avoid using PG, KO, HLN, or VOLCAR.B as direct beneficiaries of this development. Any client-side benefit from lower agency spend is unlikely to be material versus their broader marketing budgets and would not be a stock-specific catalyst.
More News
- Morgan Stanley's top picks list trounced the S&P 500 the last 12 months. Here are the new members
- Salesforce wants to charge for AI outcomes, but first it needs to figure out how
- Warren Buffett once called Berkshire Hathaway the ‘dumbest’ stock he ever bought—after 60 years, he’s stepped down with a $145 billion net worth
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Jamie Dimon says hyperscaler AI spending could hit $1 trillion next year