
Home Depot Is Down 24% From Its High. Here's Why I'd Hold It for a Decade.
Source: fool.com
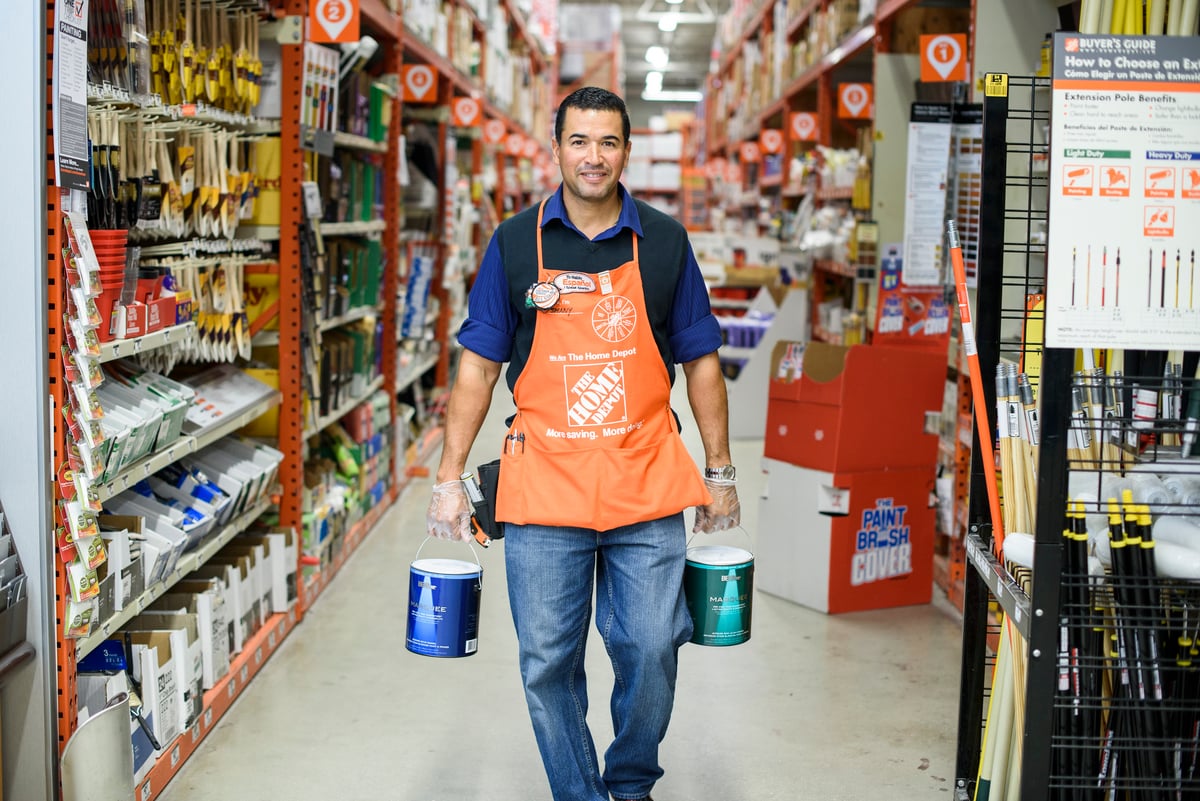
Home Depot shares are down 11% over five years, but the article argues the retailer is positioned for a long-term recovery as housing activity rebounds. It cites an estimated U.S. housing shortage of around 4 million homes, a forecast operating margin of 12.5% versus a historical level closer to 15%, and 2025 return on invested capital of 25.7%. The company is expanding its professional-contractor business through its SRS Distribution acquisition and combines growth potential with dividends and buybacks.
Analysis
The key underwriting risk is not whether housing is structurally undersupplied, but when that need converts into transactions and discretionary projects. Lower mortgage rates could first revive home sales without immediately restoring remodel spend: owners may prioritize moving, while high home prices and financing costs still constrain project budgets. Treat rate cuts as a potential catalyst, not a near-term earnings guarantee.
Home Depot’s pro push could help offset weak DIY demand, but it also increases exposure to contractor activity and makes the SRS integration a more important execution test. Watch pro sales, comparable sales, and operating margin together; growth bought through lower margins or weaker returns would undermine the quality premium. The article’s longer-run margin recovery case is conditional, not evidence of a near-term inflection.
Amazon is unlikely to displace a store-based model for bulky materials, but digital convenience can still pressure price transparency and customer acquisition costs. The more immediate competitive issue is whether Home Depot converts its fulfillment footprint and pro relationships into share gains versus Lowe’s and local distributors.
The contrarian point: an eventual housing recovery may already be embedded in a blue-chip valuation, while the timing and mix of recovery remain uncertain. Over the next 1–3 months, earnings evidence matters more than housing-shortage estimates; over 6–18 months, transaction volumes, contractor demand, and SRS execution determine whether earnings leverage materializes.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Avoid treating lower rates or housing-supply estimates alone as a buy signal. Before adding HD, verify sequential improvement in comparable sales and pro demand, alongside stable or improving operating margin.
- For existing exposure, hold only if the thesis is long-duration and position sizing tolerates a delayed housing recovery. Reassess if management cuts its outlook, pro sales weaken, or margin recovery depends on demand that has not appeared.
- Use the next earnings report as a catalyst checkpoint: track comparable sales, transaction versus ticket trends, pro customer performance, and SRS integration disclosures. A sales improvement accompanied by material margin deterioration would falsify the quality-of-recovery thesis.
- No compelling standalone trade is established by this article. If seeking a relative-value expression, compare HD with Lowe’s after checking valuation, recent category growth, and pro exposure; do not assume the duopoly makes either stock inexpensive.
More News
- Stocks started the week with promise but ended in despair. Our take on the big reversal
- AWS grows 39% and Amazon will spend even more on AI in 2027
- OpenAI pares fundraising goal, now seeking up to $20 billion in latest round
- Fears over $828 billion AI capex spending spree help erase $1 trillion in market value
- AI boom hits a wall on Wall Street as OpenAI cuts fundraising target while Meta gets a credit warning over its cash flow, spending and monetization
- From Karl Marx’s vampire to Warren Buffett’s moat, the crumbling gothic castle has been capitalism’s favorite metaphor for 250 years