
Coming soon: InHand Networks Previews the IR602 5G RedCap Industrial Router for the U.S. Market
Source: Newswire
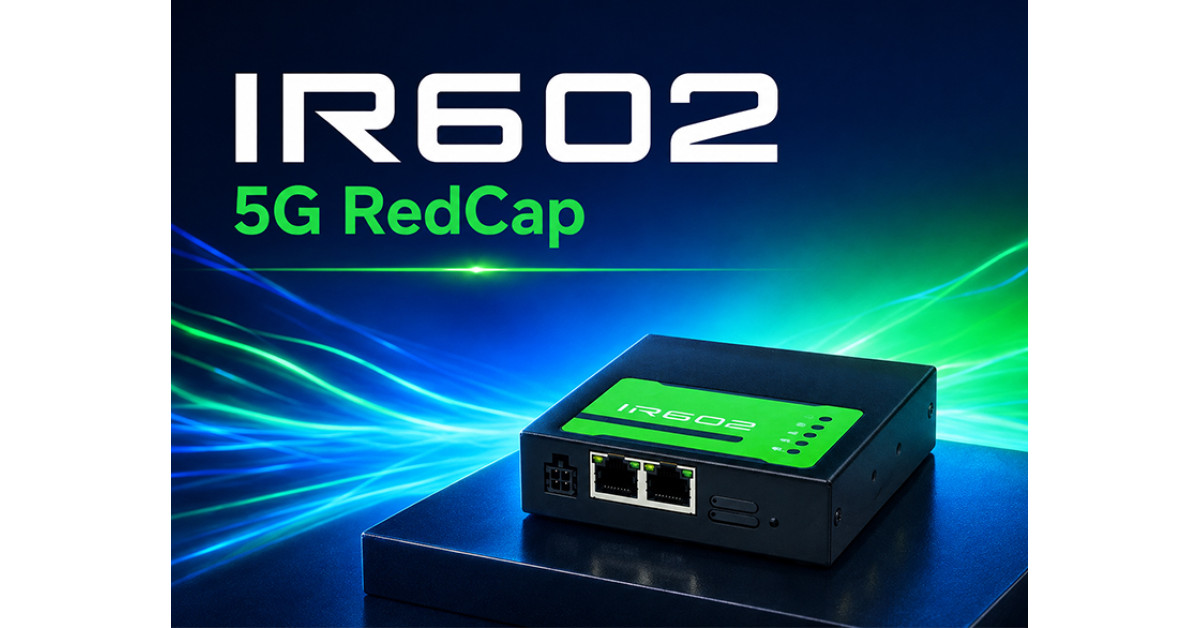
InHand Networks previewed the IR602 5G RedCap industrial router, targeting medium-data-rate IoT with up to 223 Mbps down/123 Mbps up on 5G RedCap and dual-band Wi‑Fi 6 plus 2.5GbE. The unit includes multi-WAN link management (dual-SIM hot backup, health checks, load balancing), VPN support (IPsec/L2TP/WireGuard/OpenVPN), and remote monitoring/OTA management via DeviceLive. Commercial availability in the U.S. is planned after certification/approval, with U.S. pricing and certified SKUs to be announced separately.
Analysis
This is more important as a standards-to-productization signal than as a single-router launch. RedCap lowers the cost/power barrier for industrial 5G, which expands the addressable market for distributed edge connectivity where LTE was previously “good enough.” The first-order winner is the 5G ecosystem that monetizes more endpoints; the first-order loser is the low-end industrial router/gateway layer, where pricing power erodes once comparable SKUs are broadly certified.
Near term, the gating item is not engineering capability but U.S. certification, carrier approval, and channel readiness. That means the earnings impact is likely muted for 1-2 quarters; the real catalyst is whether this converts into repeatable fleet deployments and recurring cloud/device-management attach. If the management layer stays optional, the hardware becomes a commodity box and margins compress quickly.
The contrarian risk is that the market may overrate adoption speed. Industrial buyers care about coverage, uptime, and install simplicity more than peak throughput, so hybrid LTE/Wi-Fi remains sticky until standalone 5G coverage is ubiquitous and RedCap chipsets are broadly supported. If certifications slip or carrier support is narrow, this is a marketing event rather than a demand inflection; that would favor fading enthusiasm in small-cap industrial networking names rather than chasing a thematic long.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate trade in the launch itself; wait for U.S. certification, carrier compatibility, and pricing before underwriting any revenue inflection. Falsifier: if certified SKUs are delayed beyond the next 90 days, treat this as a watch item only.
- Relative-value idea: long QCOM / short a basket of low-end industrial networking names such as DGII and LTRX for 3-6 months. Thesis: RedCap expands modem content modestly, but the bigger effect is commoditizing router hardware pricing. Risk/reward is roughly 2:1 if RedCap adoption broadens; thesis breaks if carrier SA rollout stalls.
- Watch VZ, T, and TMUS for private-wireless and enterprise-connectivity commentary on upcoming earnings. Use any booking or ARPU acceleration as confirmation that RedCap is translating into monetizable deployments rather than one-off device sales.
- If the market overreacts to launch headlines, consider a tactical short in DGII/LTRX on strength rather than buying industrial IoT beta. The upside case depends on fleet-scale adoption and cloud attach, which are not yet visible.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Faraday Copper completes acquisition of BHP’s San Manuel project
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- Ukraine to resume strikes on Russian refineries, shattering hopes of an 'energy ceasefire'
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Can Hedge Funds Use ChatGPT? A Control Framework
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash